Can You Be Addicted To Adrenaline? Understanding The Thrill-Seeker’s Mind
October 16, 2025
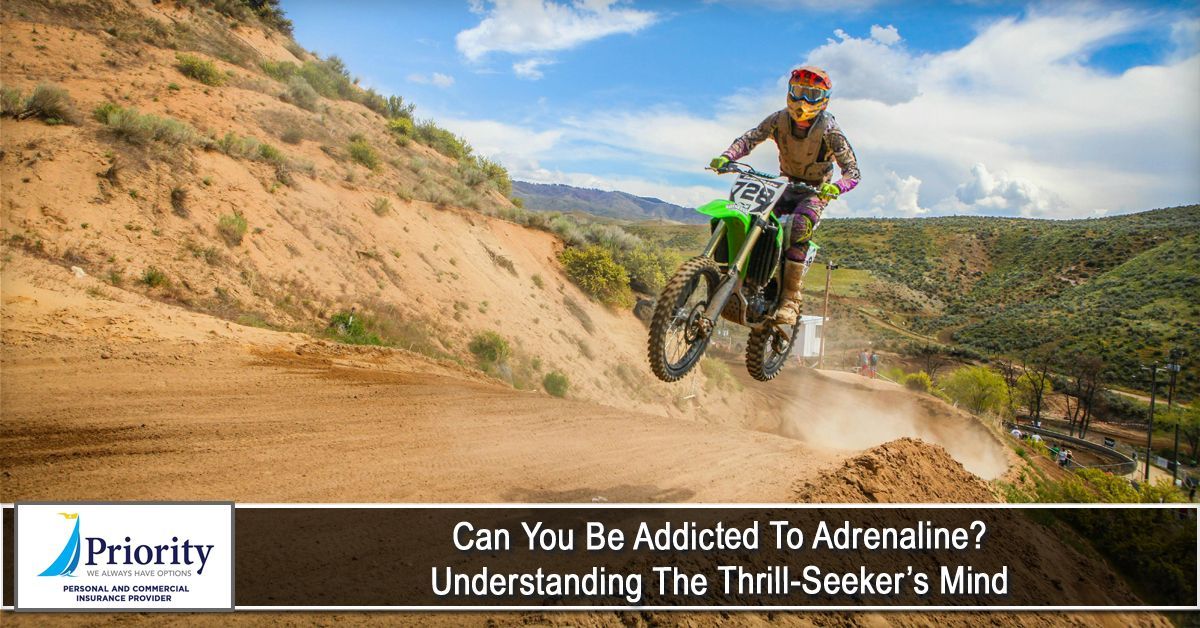
A motocross rider in mid-air, on a dirt path with a green bike.

Reduced pain sensitivityFrom skydiving and mountain biking to racing motorcycles at high speeds—many people crave the rush of excitement that comes from taking risks. That exhilarating feeling comes from adrenaline, a powerful hormone that prepares the body for action. But for some, chasing that rush can become more than a hobby—it can turn into a lifestyle.


So, can you actually be addicted to adrenaline? Let’s explore how this “thrill-seeking” behavior works, what drives it, and how to balance excitement with safety.


What Is Adrenaline?

Adrenaline, also known as epinephrine, is a hormone released by the adrenal glands in response to stress, excitement, or danger. It triggers the body’s “fight-or-flight” response, preparing you to react quickly in intense situations.


When Adrenaline Kicks In, You Might Experience:

  • Increased heart rate and breathing
  • Heightened focus and alertness
  • Surge of energy and strength
  • Reduced pain sensitivity
  • A feeling of euphoria or invincibility


This reaction is useful in emergencies—but when people repeatedly seek out that rush, it can lead to adrenaline dependence or what some call an “adrenaline addiction.”


Can You Really Be Addicted to Adrenaline?

While adrenaline itself isn’t classified as an addictive substance like drugs or alcohol, people can become psychologically addicted to the sensations it produces.


Here’s How It Works:

  1. Dopamine Connection: When adrenaline spikes, it often triggers a release of dopamine—the brain’s “reward chemical.” This creates feelings of pleasure and satisfaction.
  2. Reinforcement Loop: The brain begins to associate risky or exciting activities with positive emotions.
  3. Tolerance Effect: Over time, thrill-seekers may need more intense experiences to feel the same level of excitement.


This pattern can drive people toward increasingly dangerous activities, such as extreme sports, street racing, or high-stakes gambling.


Signs You Might Be an “Adrenaline Junkie”

You might be drawn to adrenaline if you:

  • Feel restless or bored without excitement
  • Frequently seek out risky or high-intensity experiences
  • Enjoy activities that others find intimidating
  • Take unnecessary risks for the thrill
  • Feel euphoric during danger but crash emotionally afterward


While occasional excitement is healthy, consistently needing that rush can take a toll on your mental and physical health.


The Science of the Thrill-Seeker’s Brain

Research suggests that thrill-seekers may be wired differently. Studies show that individuals with lower natural levels of dopamine tend to seek more intense experiences to achieve satisfaction.


This doesn’t mean thrill-seeking is bad—it can foster resilience, confidence, and focus. However, unchecked risk-taking can lead to serious consequences like injury, burnout, or chronic stress.


In communities like Greenville, SC, where adventure sports and motorcycle culture are popular, understanding your limits is key to staying safe while enjoying life’s thrills.


Finding a Healthy Balance

If you love adventure, there’s no need to give it up—you just need to channel it responsibly.


Tips to Manage Your Adrenaline Cravings:

  • Pace your activities: Balance high-intensity experiences with calmer hobbies like yoga, hiking, or meditation.
  • Recognize your triggers: Be mindful of what situations or emotions drive you to seek a thrill.
  • Prioritize safety: Always use proper gear and follow safety guidelines.
  • Talk it out: If adrenaline-seeking affects your work or relationships, consider speaking with a mental health professional.
  • Find new challenges: Try creative outlets like music, art, or fitness training that stimulate the brain without physical danger.


Why It’s Important to Have Motorcycle Insurance

For many thrill-seekers, motorcycling is the ultimate adrenaline experience—freedom, speed, and focus all rolled into one. But with that freedom comes responsibility, and that’s where motorcycle insurance plays a vital role.


Key Benefits of Motorcycle Insurance:

  • Financial Protection: Covers repair or replacement costs after accidents or theft.
  • Liability Coverage: Pays for injuries or property damage you cause to others.
  • Medical Coverage: Helps pay for medical expenses if you’re injured in a crash.
  • Uninsured/Underinsured Motorist Coverage: Protects you if another driver doesn’t have adequate insurance.
  • Comprehensive Coverage: Safeguards against non-collision events like vandalism, fire, or weather damage.


Who It Best Serves:

  • Daily riders and commuters
  • Weekend riders and motorcycle enthusiasts
  • High-performance or sport bike owners
  • Adventure riders who travel across states


In Greenville, SC, where scenic mountain roads and warm weather attract motorcyclists year-round, having the right insurance ensures you can enjoy the thrill—without the financial risk.


Final Thoughts

Being drawn to excitement is part of human nature, but when the chase for adrenaline becomes constant, it can edge into risky territory. Understanding what fuels your thrill-seeking tendencies helps you make smarter, safer choices—so you can embrace adventure without sacrificing well-being.


And if motorcycling or extreme sports are your outlet, don’t forget to protect yourself. The right motorcycle insurance provides peace of mind, letting you enjoy the ride knowing you’re covered—whether you’re cruising through the scenic roads of Greenville, SC, or chasing your next big adventure.


At Priority Insurance LLC, we put our clients first by offering them policies that they can afford. Having insurance is a necessity nowadays, and we're here to help you out. Learn more about our products and services by calling our agency at 
(864) 297-9744. You can also request a quote by CLICKING HERE.

Disclaimer: The information presented in this blog is intended for informational purposes only and should not be considered as professional advice. It is crucial to consult with a qualified insurance agent or professional for personalized advice tailored to your specific circumstances. They can provide expert guidance and help you make informed decisions regarding your insurance needs.​


By Mark Turley • November 17, 2026
A business owner who needs to get workers’ compensation insurance for the first time is likely to have lots of questions. This is a large area of insurance that has the potential to make the difference between a company surviving or failing in the event of a work-related accident. SC generally requires this coverage for a company with four or more employees, and employers with an annual payroll of less than $3,000 are exempt regardless of employee count. Part-time workers count toward the threshold, and so do corporate officers who haven’t rejected coverage. This often catches small corporations off guard! Here are three answers to some of the common questions that come up related to workers’ compensation insurance in Greenville, SC. If any of these topics prompt more questions in your mind about your current insurance coverage, or if you aren’t sure whether workers’ compensation is required by law for your business, schedule a consultation with one of our South Carolina insurance experts here at Priority Insurance.
Woman behind a café counter with glass pastry display and coffee equipment
October 13, 2026
Buy-sell agreements, key person insurance, and executive bonus plans for Upstate SC business owners. Protect your family, partners, and key people.
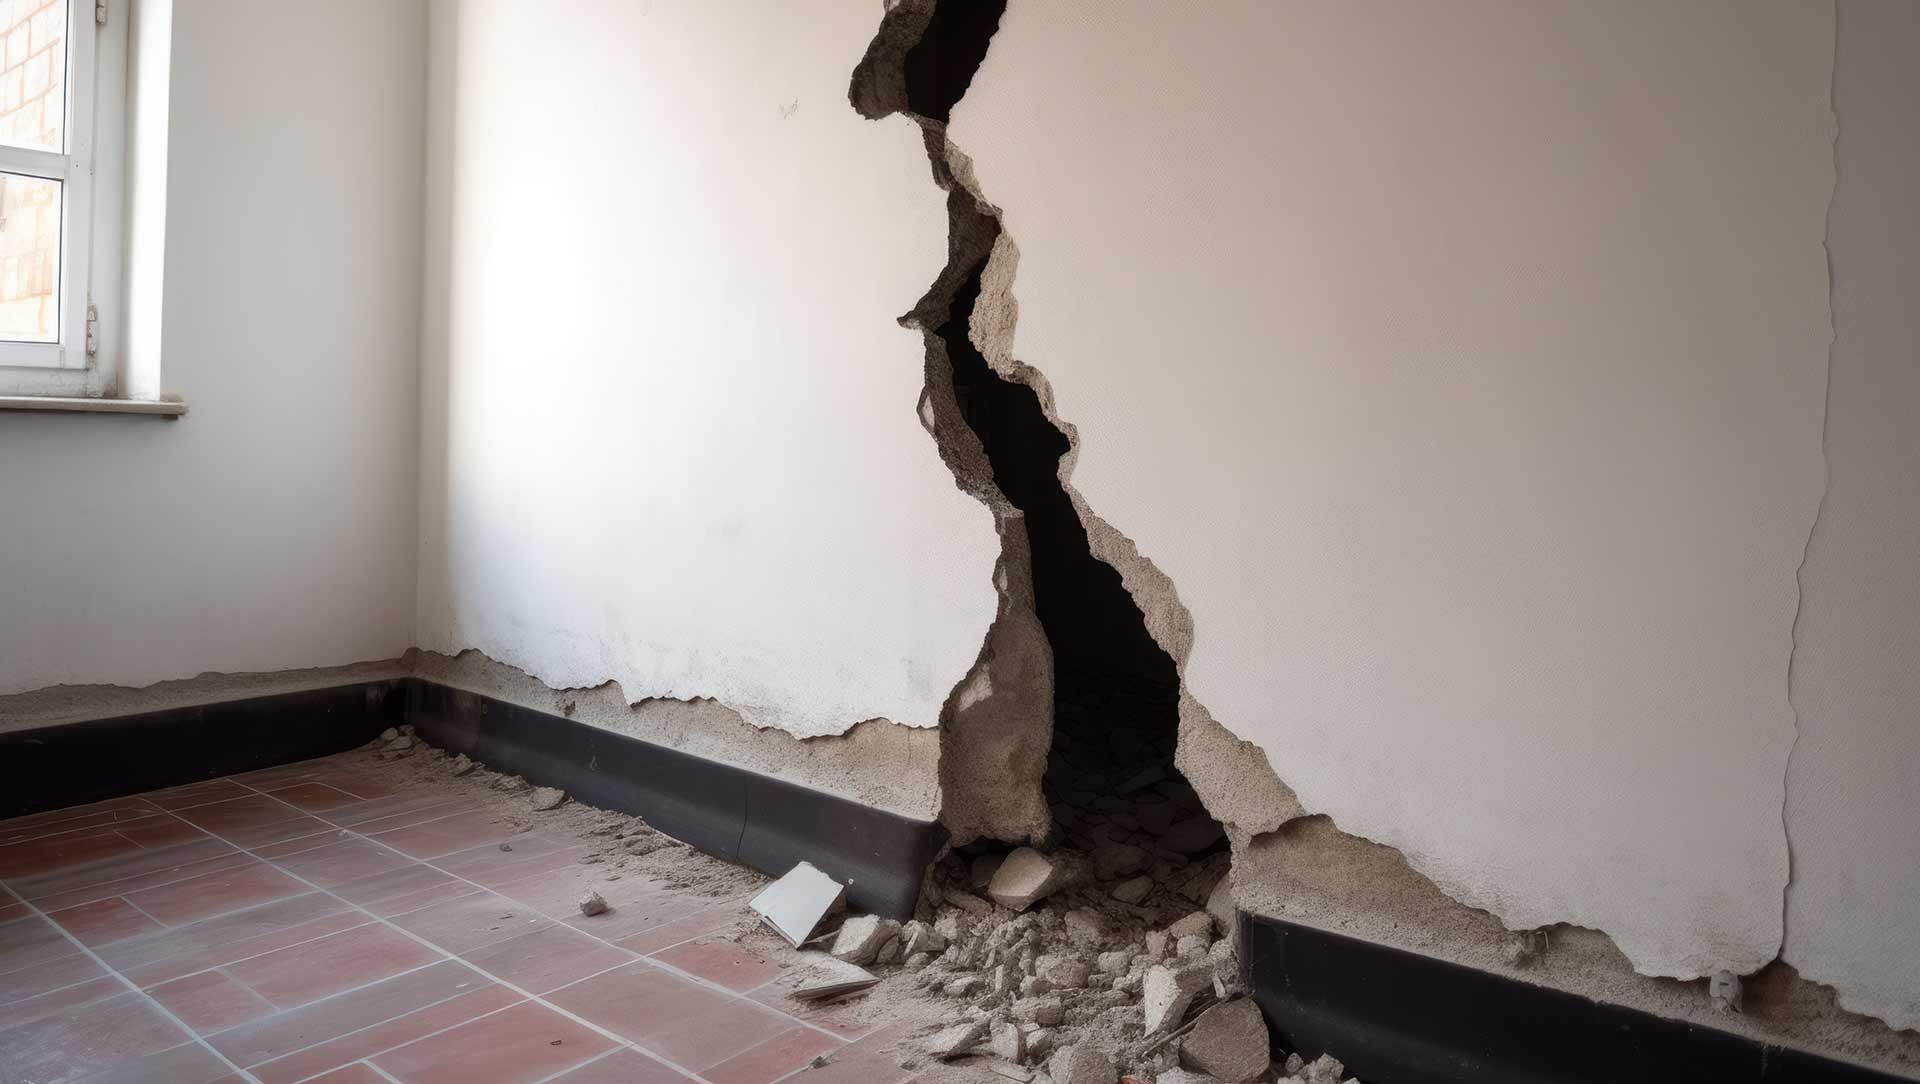
Interior wall with a large vertical crack and crumbled plaster exposing damage near the floor.
October 8, 2026
Most homeowners I sit down with in Greenville can tell me their deductible and roughly what their house is insured for. Very few can tell me whether they're covered if the ground shakes, or if the sewer line backs up into the house. That's not a knock on anybody — these are two coverages almost nobody thinks about until the day they need them. And on that day, a lot of people find out the answer is no.  Both earthquake damage and sewer or water backup are excluded on a standard homeowners policy. Both can usually be added back, often for a modest cost. Here's what I want every homeowner in the Upstate to understand about each one.
By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Night-lit two-story brick house with a balcony and warm exterior lights at night
September 17, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
Show More