Why You Should Consider Adding Roadside Assistance To Your Auto Insurance Policy
February 12, 2026
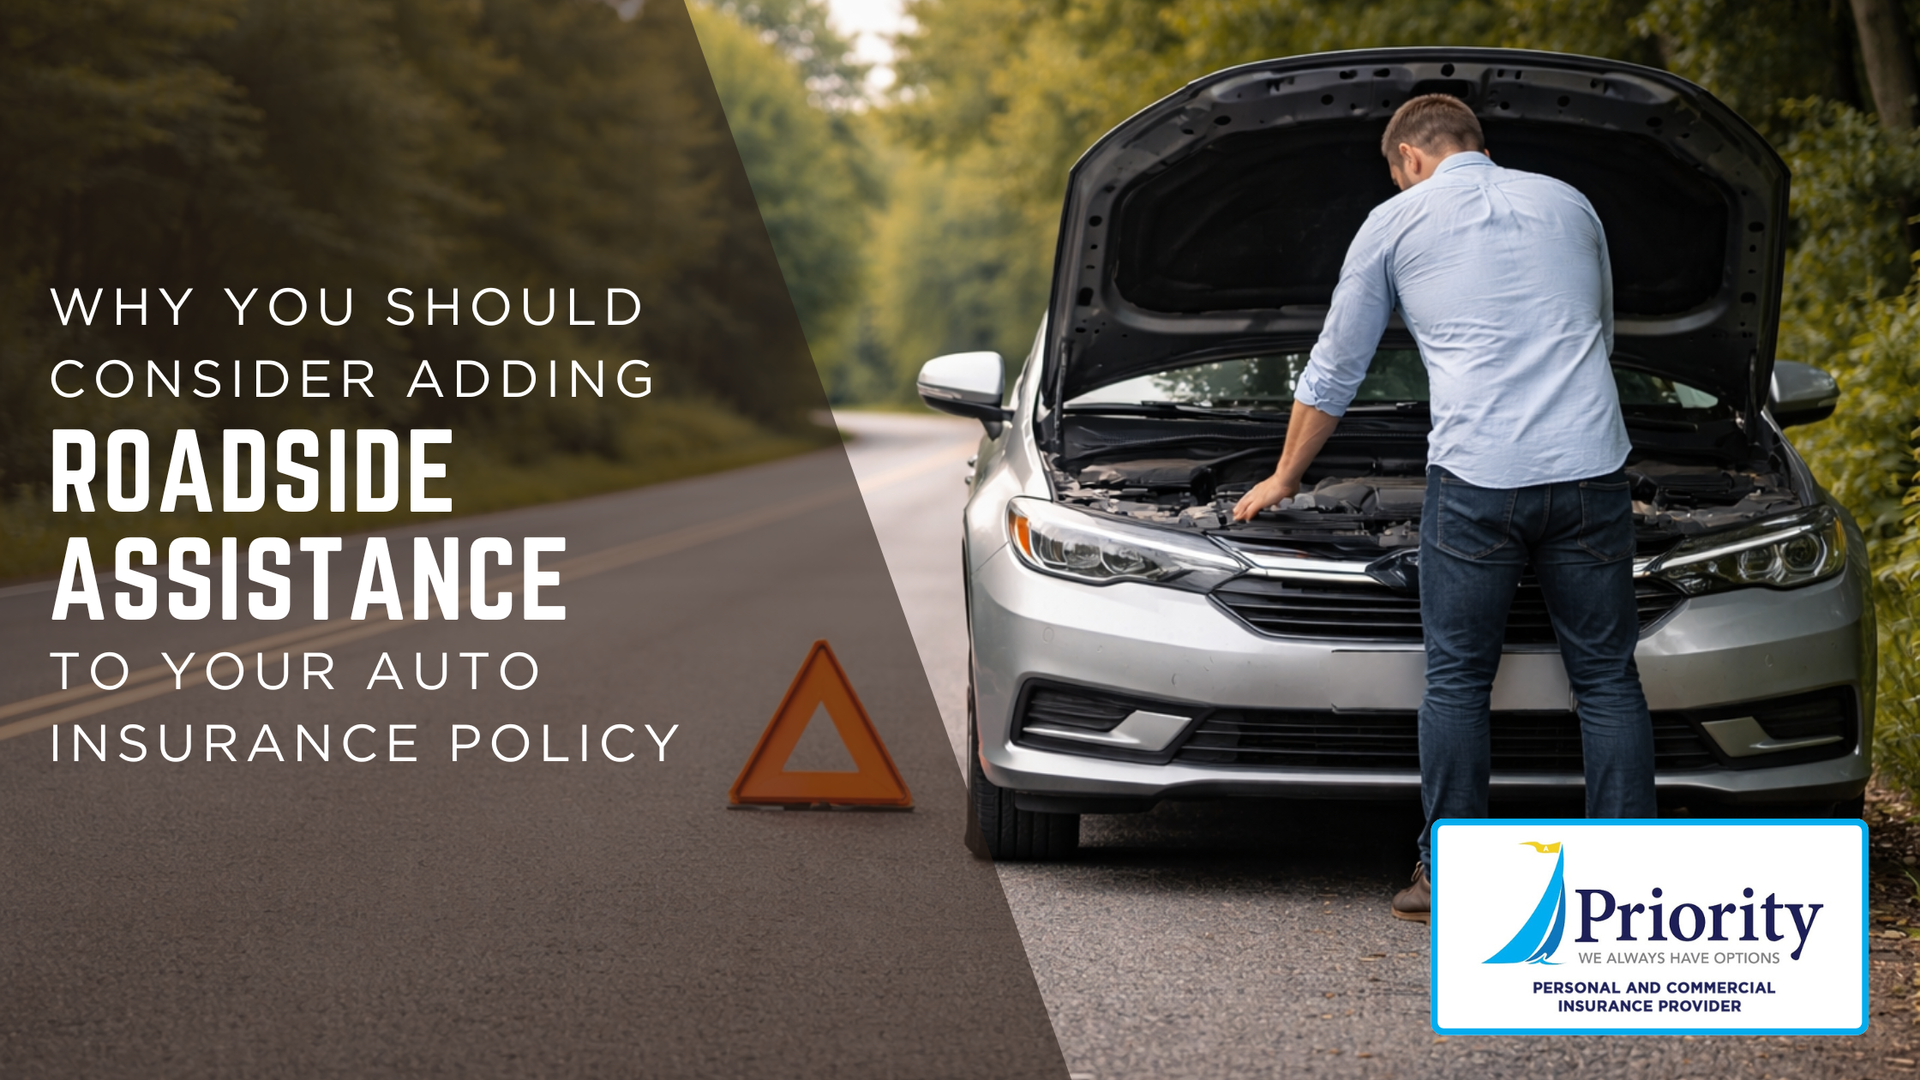
Roadside assistance ad with man inspecting a broken-down silver car on a roadside

Adding roadside assistance to your auto insurance policy can be a low-cost way to get help for common breakdowns like dead batteries, flat tires, lockouts, and towing—often with one phone call and no need to shop for a service provider. It’s especially useful if you drive frequently, commute in heavy traffic, or want predictable help when something goes wrong in Greenville, SC.


Why You Should Consider Adding Roadside Assistance To Your Auto Insurance Policy

What Roadside Assistance Actually Is (And What It Isn’t)

 Roadside assistance is a service benefit that helps when your vehicle becomes disabled and you need help to get moving again or get towed to a repair facility. It’s not the same as collision or comprehensive coverage, and it’s not meant to pay for major repairs. Instead, it covers the “urgent basics” that keep a minor incident from turning into a long, expensive day.


Most roadside assistance programs are designed to handle routine, high-frequency problems such as:

  • Towing after a breakdown
  • Battery jump-start
  • Flat tire change (with a spare)
  • Lockout service
  • Fuel delivery (usually you pay for the fuel, service may be covered)
  • Winching or extraction in limited scenarios (varies by plan)


In our work with clients, a common issue we see is people assuming roadside assistance covers the cost of a new battery, tire, or repair. Typically, it covers the service call and labor for simple roadside tasks, not the parts.


Why Adding It To Your Auto Policy Can Be Convenient

You can get roadside assistance from several sources: auto clubs, vehicle manufacturers, credit cards, or insurance companies. Adding it to your auto insurance policy can be appealing because it consolidates your coverage and makes access simple.


Practical advantages often include:

  • One number to call, especially if you already have a claims or service app
  • Straightforward eligibility because it’s tied to a covered vehicle
  • Less need to compare multiple third-party plans
  • Often a modest premium add-on compared to standalone memberships


If you’re trying to reduce “subscription overload,” bundling roadside assistance with your auto policy can simplify your setup.


The Real-World Situations Where It Pays Off Quickly

Roadside assistance is most valuable in predictable, common scenarios—especially when you’re stuck and can’t safely solve the issue yourself.


Dead Battery Or No-Start

Battery failures are common, and they often happen at the worst time: early morning, after work, or during bad weather. Jump-start service gets you moving quickly, and if the battery is truly failing, it at least gets you to a shop without needing to coordinate a tow separately.


Flat Tire On The Road

If you have a spare and the tire can be changed safely, roadside assistance can handle the swap. If you don’t have a spare (which is increasingly common) or your tire is damaged beyond a quick fix, towing can be the difference between a manageable inconvenience and a long, stressful delay.


Lockout

Lockouts happen to careful people, too—especially with key fobs, trunk lockouts, or distracted moments when juggling groceries or work equipment. Roadside assistance can prevent you from paying high out-of-pocket locksmith rates.


Out Of Fuel Or Charging Issues

Fuel delivery can help if you misjudge distance or run into unexpected traffic. For EVs, roadside services vary, but many programs can still provide towing to the nearest charging location if you’re stranded.


Breakdown And Towing

This is the biggest value driver. A tow arranged in the moment—especially after hours—can be expensive and hard to coordinate. Having towing included or discounted can reduce cost uncertainty.


Along busy stretches near Haywood Mall, it’s not unusual for a minor mechanical problem to become a bigger safety concern simply because traffic makes it hard to wait or troubleshoot. Getting help quickly matters.


What Roadside Assistance Typically Covers And Common Limits

Roadside assistance is not unlimited. Most plans include limits that you should know before you rely on it.


Common limitations include:

  • Towing distance limit (for example, a set number of miles per event)
  • Number of service calls allowed per year
  • Coverage restrictions for certain vehicles (heavy-duty trucks, specialty vehicles)
  • Winching/extraction limits (distance off-road, severity of situation)
  • Service availability based on provider networks and location


Practical tip: ask what towing distance is included and whether you can choose the destination or if it must be the nearest qualified repair facility.


Roadside Assistance Vs Towing And Labor Coverage: Are They The Same?

Depending on the carrier, “roadside assistance,” “towing and labor,” and similar names can mean slightly different things. Some emphasize towing after disablement, while others emphasize small roadside services.


When reviewing options, confirm:

  • Does it include towing and roadside labor, or towing only?
  • What counts as a covered disablement?
  • Are lockouts included?
  • Is tire service included if there’s no spare?
  • Is there a per-incident dollar cap?


These details can change the value more than the premium difference.


Will Using Roadside Assistance Affect My Premium?

This is one of the most common questions. Roadside assistance is typically treated differently than at-fault accidents, but every insurer handles service usage and claims history differently. The key is to view it as a convenience feature and use it appropriately.


Practical approach:

  • Use it for true roadside needs (tow, lockout, no-start, flat)
  • Keep records of repeated issues (multiple battery calls often signal a replacement is needed)
  • If you’re concerned about how service calls are recorded, ask how roadside events are categorized under your specific policy


In many cases, the bigger risk is not “rate impact” but repeatedly relying on roadside service instead of fixing the underlying maintenance issue.


Who Benefits Most From Adding Roadside Assistance?

Roadside assistance is often a good fit if:

  • You commute regularly or drive daily for work
  • You have an older vehicle or higher mileage car
  • You drive at night, travel with family, or prefer safer, faster assistance
  • You don’t want to coordinate towing/locksmith services on your own
  • You want predictable help without carrying a separate membership


We also see it help newer drivers and families with teen drivers, where the peace-of-mind benefit is often just as important as the cost benefit.


How To Decide If It’s Worth It For You

Instead of guessing, look at your driving reality and the alternatives you already have.


Ask yourself:

  • Do I already have roadside help through a manufacturer warranty, credit card, or membership?
  • If my car broke down today, would I know who to call and what it would cost?
  • Is my vehicle equipped with a spare tire and tools, or would I need a tow for a flat?
  • Do I drive in areas where being stuck would be a safety concern?


If you already have reliable roadside coverage elsewhere, adding it may be redundant. If you don’t, the value often comes from the first or second time you need help.


A practical comparison method: price out a single tow in your area, then compare it to the annual cost of adding roadside assistance. For many drivers, one tow can exceed a full year (or more) of the add-on premium.


Common Pitfalls To Avoid

To get full value from roadside assistance, avoid these common problems:

  • Assuming it covers repairs or parts (it usually doesn’t)
  • Not knowing towing distance limits until you need a long tow
  • Forgetting to update the covered vehicle list after buying/selling cars
  • Relying on roadside assistance repeatedly instead of fixing maintenance issues
  • Assuming every vehicle you own automatically has the benefit (it’s usually tied to specific listed vehicles)


If you live or travel around areas like Five Forks, it’s also smart to confirm service availability and whether coverage applies seamlessly across county lines and longer trips.


Conclusion

Roadside assistance can be a practical, low-stress add-on that turns common breakdown problems into manageable inconveniences—especially when towing, lockouts, and jump-starts happen at inconvenient times. The best way to decide is to compare the modest add-on cost to the real cost and hassle of arranging emergency help on your own, and to confirm the limits that matter most (towing distance and number of calls). If you want help reviewing whether roadside assistance makes sense on your policy in Greenville, SC, we can walk through your options and match the coverage to how you actually drive.


At Priority Insurance LLC, we put our clients first by offering them policies that they can afford. Having insurance is a necessity nowadays, and we're here to help you out. Learn more about our products and services by calling our agency at (864) 297-9744. You can also request a quote by CLICKING HERE.

Disclaimer: The information presented in this blog is intended for informational purposes only and should not be considered as professional advice. It is crucial to consult with a qualified insurance agent or professional for personalized advice tailored to your specific circumstances. They can provide expert guidance and help you make informed decisions regarding your insurance needs.​


 Priority Insurance LLC

 Greenville, SC

 (864) 297-9744

 https://www.priorityi.com/


Woman behind a café counter with glass pastry display and coffee equipment
October 13, 2026
Buy-sell agreements, key person insurance, and executive bonus plans for Upstate SC business owners. Protect your family, partners, and key people.
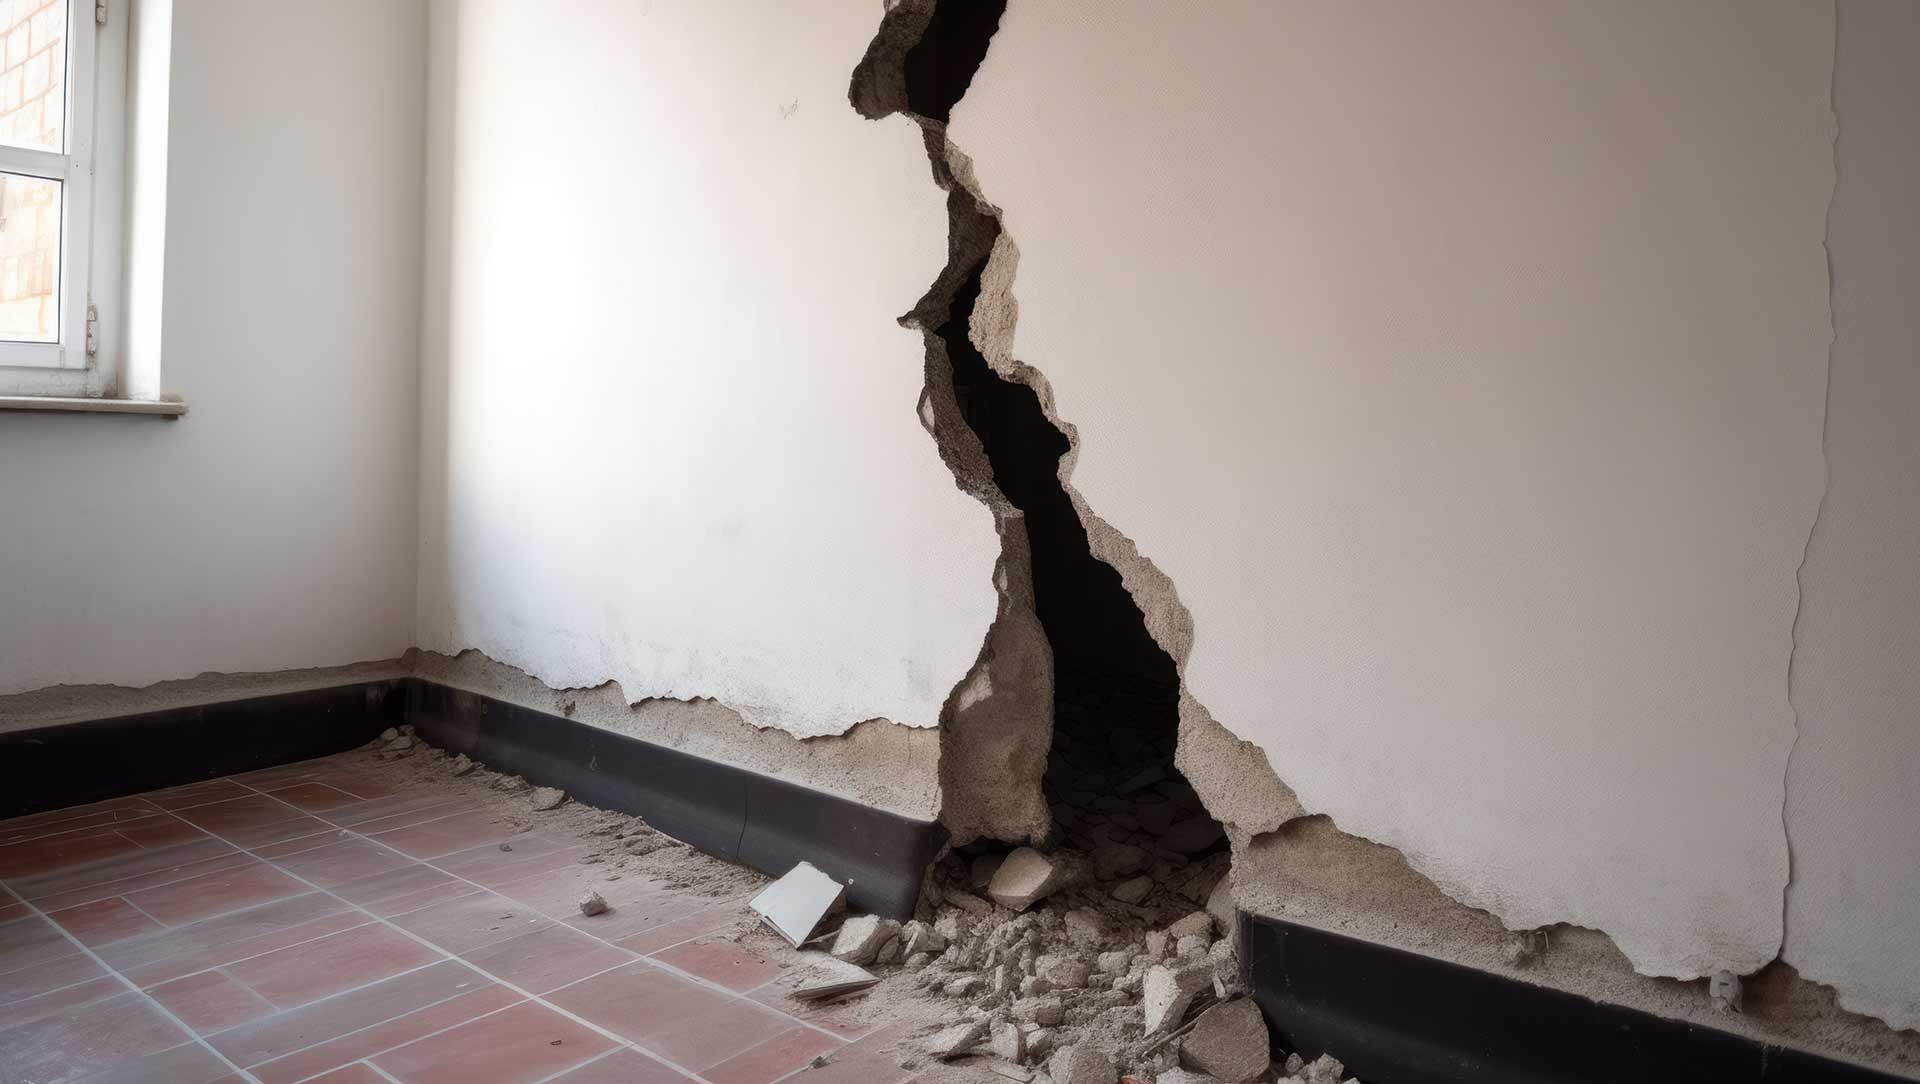
Interior wall with a large vertical crack and crumbled plaster exposing damage near the floor.
October 8, 2026
Most homeowners I sit down with in Greenville can tell me their deductible and roughly what their house is insured for. Very few can tell me whether they're covered if the ground shakes, or if the sewer line backs up into the house. That's not a knock on anybody — these are two coverages almost nobody thinks about until the day they need them. And on that day, a lot of people find out the answer is no.  Both earthquake damage and sewer or water backup are excluded on a standard homeowners policy. Both can usually be added back, often for a modest cost. Here's what I want every homeowner in the Upstate to understand about each one.
By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Night-lit two-story brick house with a balcony and warm exterior lights at night
September 17, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
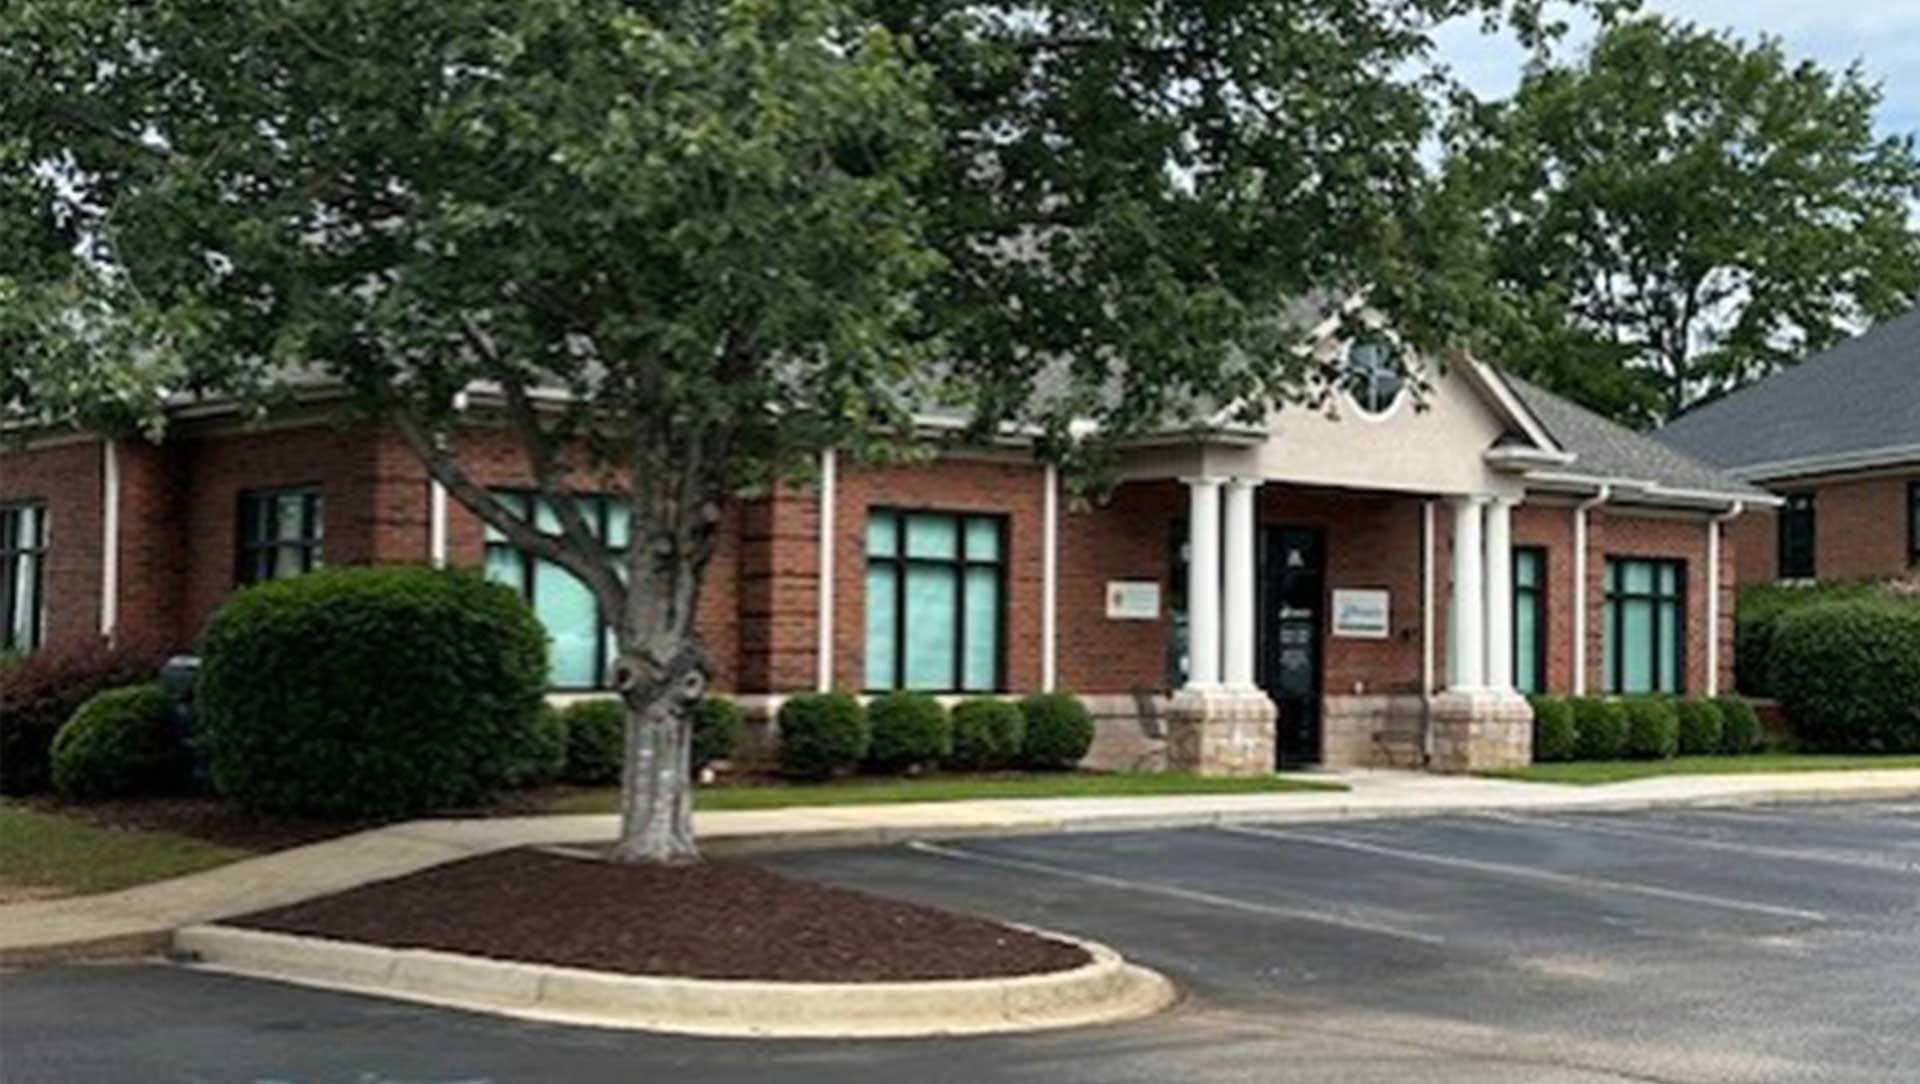
Brick office building with white columns, green awnings, and a tree-lined parking lot
By By Mark Turley, Owner — Priority Insurance LLC • August 11, 2026
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Show More