Collector Cars & Insurance: Everything You Need to Know to Protect Your Investment
December 16, 2025
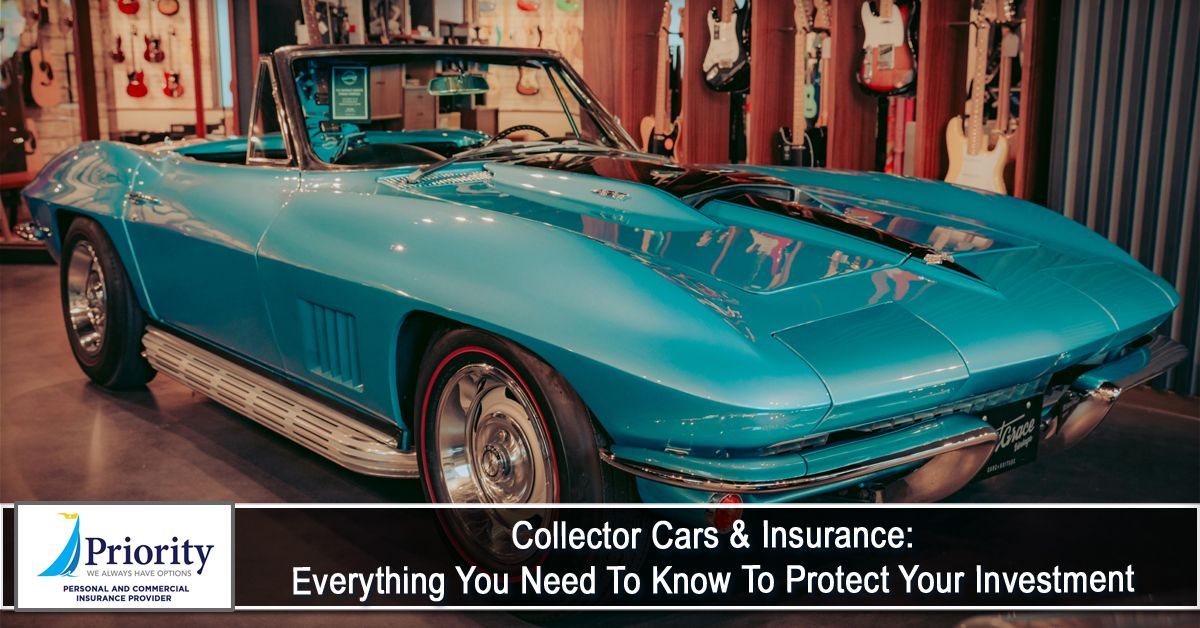
A blue vintage Corvette convertible.

Owning a collector car is more than a hobby—it’s a passion, an investment, and often a treasured piece of automotive history. Whether you’ve restored a classic muscle car, preserved a vintage European model, or acquired a limited-production modern collectible, protecting your investment is essential.

Collector cars require more than standard auto insurance. With unique value, usage patterns, and preservation needs, they demand specialized coverage that reflects their true worth. Understanding how collector car insurance works helps ensure your prized vehicle is properly protected now and for years to come.


What Makes Collector Car Insurance Different?

Collector car insurance is designed specifically for vehicles that are rare, limited-use, and often appreciating in value. Unlike a standard auto policy—which factors in daily driving, depreciation, and wear—collector car insurance considers the unique way enthusiasts store, maintain, and enjoy their vehicles.


Key differences include:

  • Agreed value vs. actual cash value
  • Restrictions on mileage
  • Proof of secure storage
  • Customized repair options
  • Coverage for restoration and spare parts


This specialized approach ensures your collectible is insured for what it’s truly worth—not just a depreciated market price.


What Qualifies as a Collector Car?

While criteria vary between insurers, a vehicle may be considered a collector car if it meets one or more of the following:

  • Classic or antique
    Typically 20–25+ years old.

  • Limited production or high-value
    Rare models or special editions.

  • Exotic performance vehicles
    Premium or supercars with lasting resale value.

  • Modern collectibles
    Newer models projected to appreciate over time.

  • Restored or preserved cars
    Vehicles maintained to original or enhanced condition.

General requirements often include:

  • Limited annual mileage
  • Secure, indoor storage
  • A clean driving record
  • The car not being used as a daily driver


Agreed Value vs. Actual Cash Value: The Most Important Distinction

One of the biggest advantages of collector car insurance is agreed value coverage.


Agreed Value Coverage

  • You and the insurer determine the car’s value upfront.
  • If the car is totaled, you receive the full agreed amount.
  • No depreciation is applied.


Actual Cash Value (Standard Auto Insurance)

  • Pays only what the car is worth at the time of loss.
  • Depreciation significantly reduces payout.
  • Often leaves collector car owners underinsured.


For collectible vehicles, agreed value is essential to protecting long-term investment.


What Collector Car Insurance Typically Covers

Collector car policies offer a wide range of protections tailored for enthusiast vehicles.


1. Comprehensive & Collision Coverage

Covers damage from:

  • Accidents
  • Weather events
  • Theft
  • Vandalism
  • Fire


2. Spare Parts Coverage

Many collectors keep parts that are difficult or expensive to find. Policies often provide coverage for spares stored at home or in a workshop.


3. Restoration Coverage

For cars currently being restored, this coverage protects:

  • Parts and materials
  • Tools
  • In-progress improvements


The value can be increased as restoration progresses.


4. Special Repair Options

Collector car owners typically want repairs done by specialty shops.


Policies may allow:

  • Choice of mechanic
  • OEM or original-spec parts
  • Restoration-quality repair standards


5. Limited-Use Protection

Since collector cars are often driven only to shows, parades, or weekend cruises, insurers consider the reduced risk and offer lower premiums.


Factors That Affect Collector Car Insurance Rates

Several elements impact the cost of coverage, including:

  • Vehicle age, rarity, and condition
  • Agreed value amount
  • Storage security
  • Mileage restrictions
  • Driver history
  • Modifications or customizations


Cars in excellent condition or stored in climate-controlled garages often receive better rates.


Car enthusiasts in Greenville, SC enjoy a thriving automotive culture with shows, weekend drives, and restoration communities. With changing weather, growing traffic, and increasing vehicle values in the Greenville area, having proper collector car insurance ensures your prized vehicle remains well protected—whether it’s stored, displayed, or driven on scenic Carolina roads.


Tips for Protecting Your Collector Car Investment

  • Store your car safely
    Preferably in a locked, indoor, temperature-controlled garage.

  • Keep detailed maintenance records
    Documentation increases vehicle value and supports claims.

  • Avoid daily driving
    Collector policies often require limited, hobby-only use.

  • Update your policy annually
    Values can change rapidly in the collector market.

  • Invest in security
    GPS trackers, alarms, and immobilizers deter theft.


Common Mistakes to Avoid

  • Relying on standard auto insurance
    It rarely reflects true vehicle value.

  • Underestimating restoration costs
    Inflation and rarity of parts can increase expenses significantly.

  • Not updating the agreed value
    Your car may appreciate over time.

  • Using the vehicle beyond policy limits
    Daily driving may void coverage.


Conclusion

Collector cars are more than vehicles—they’re investments, passion projects, and cherished pieces of history. Protecting them with the right insurance ensures you can continue enjoying your automotive treasure with confidence and peace of mind.

Whether you're restoring a classic, showcasing a vintage gem, or building a modern collection in Greenville, SC, specialized collector car insurance ensures your investment is safeguarded today and for the miles—or memories—to come.


At Priority Insurance LLC, we put our clients first by offering them policies that they can afford. Having insurance is a necessity nowadays, and we're here to help you out. Learn more about our products and services by calling our agency at 
(864) 297-9744. You can also request a quote by CLICKING HERE.


Disclaimer: The information presented in this blog is intended for informational purposes only and should not be considered as professional advice. It is crucial to consult with a qualified insurance agent or professional for personalized advice tailored to your specific circumstances. They can provide expert guidance and help you make informed decisions regarding your insurance needs.​

Woman behind a café counter with glass pastry display and coffee equipment
October 13, 2026
Buy-sell agreements, key person insurance, and executive bonus plans for Upstate SC business owners. Protect your family, partners, and key people.
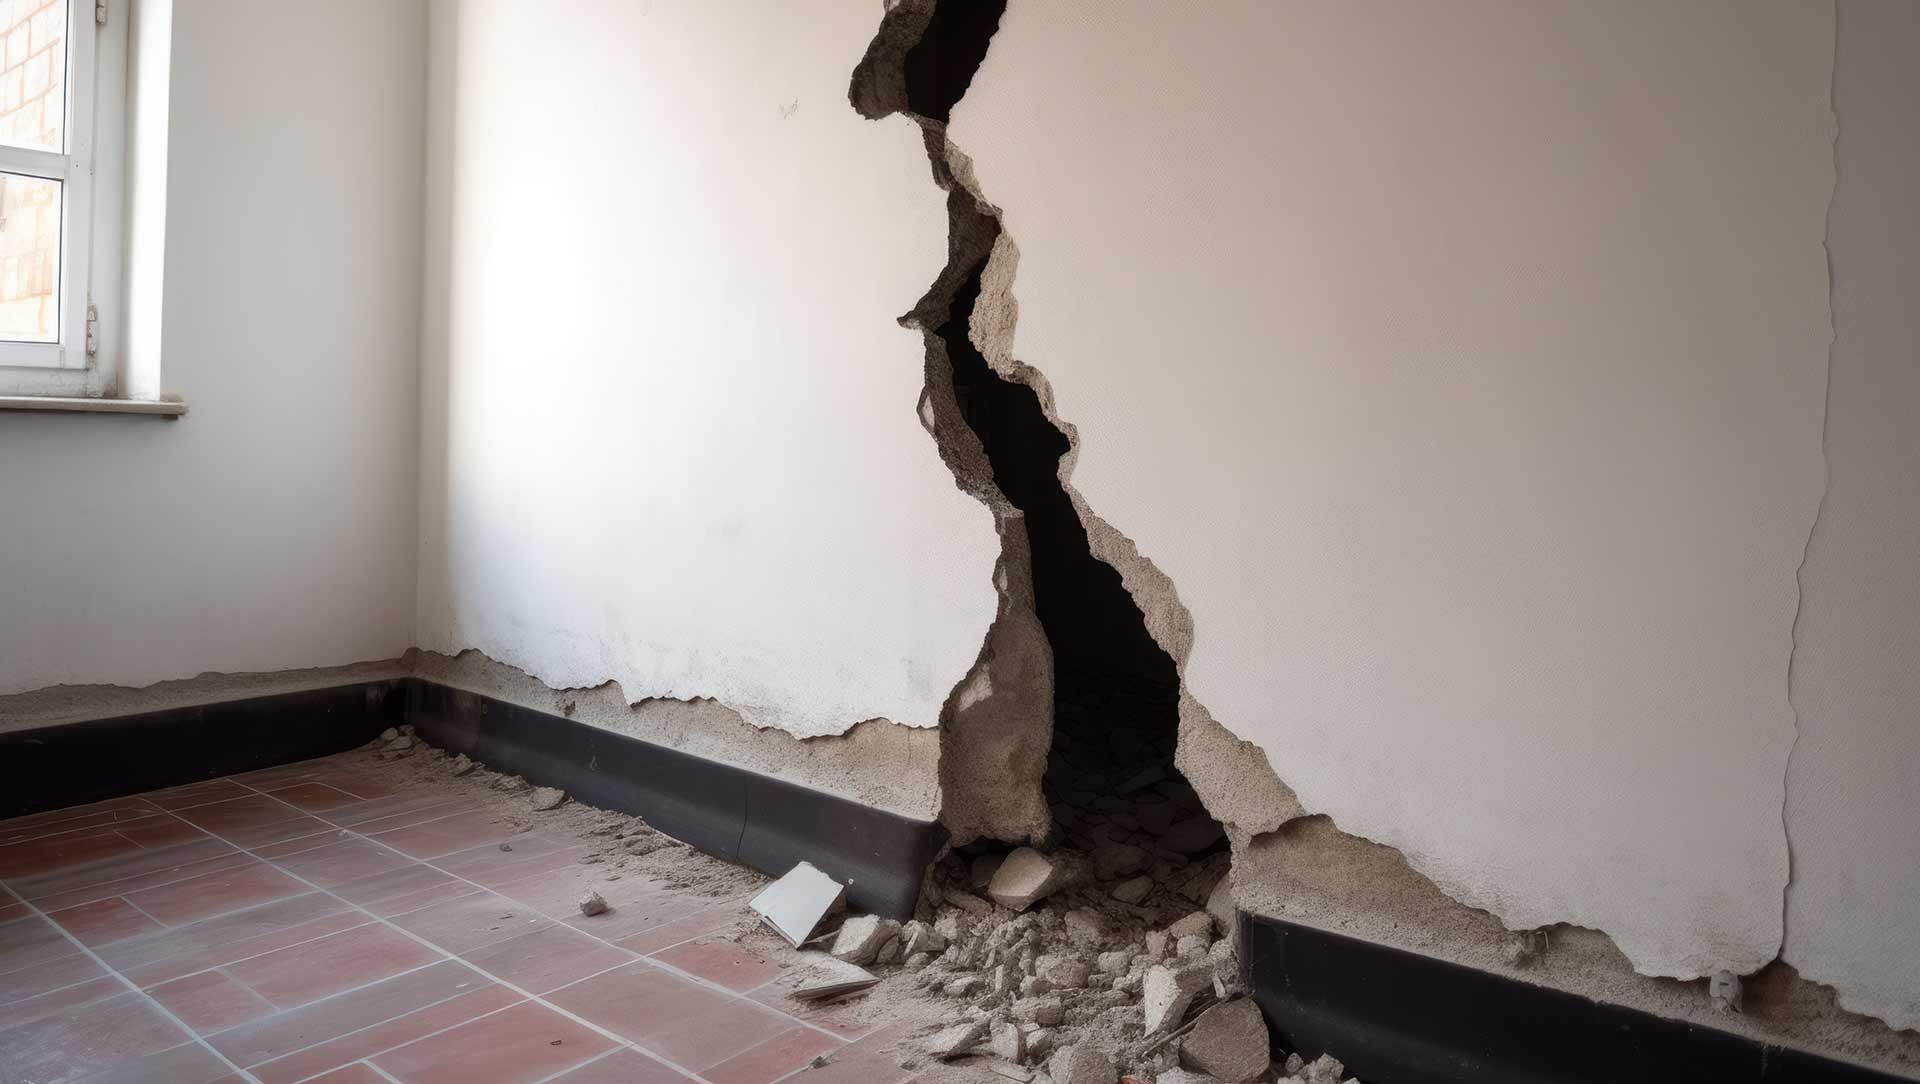
Interior wall with a large vertical crack and crumbled plaster exposing damage near the floor.
October 8, 2026
Most homeowners I sit down with in Greenville can tell me their deductible and roughly what their house is insured for. Very few can tell me whether they're covered if the ground shakes, or if the sewer line backs up into the house. That's not a knock on anybody — these are two coverages almost nobody thinks about until the day they need them. And on that day, a lot of people find out the answer is no.  Both earthquake damage and sewer or water backup are excluded on a standard homeowners policy. Both can usually be added back, often for a modest cost. Here's what I want every homeowner in the Upstate to understand about each one.
By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Night-lit two-story brick house with a balcony and warm exterior lights at night
September 17, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
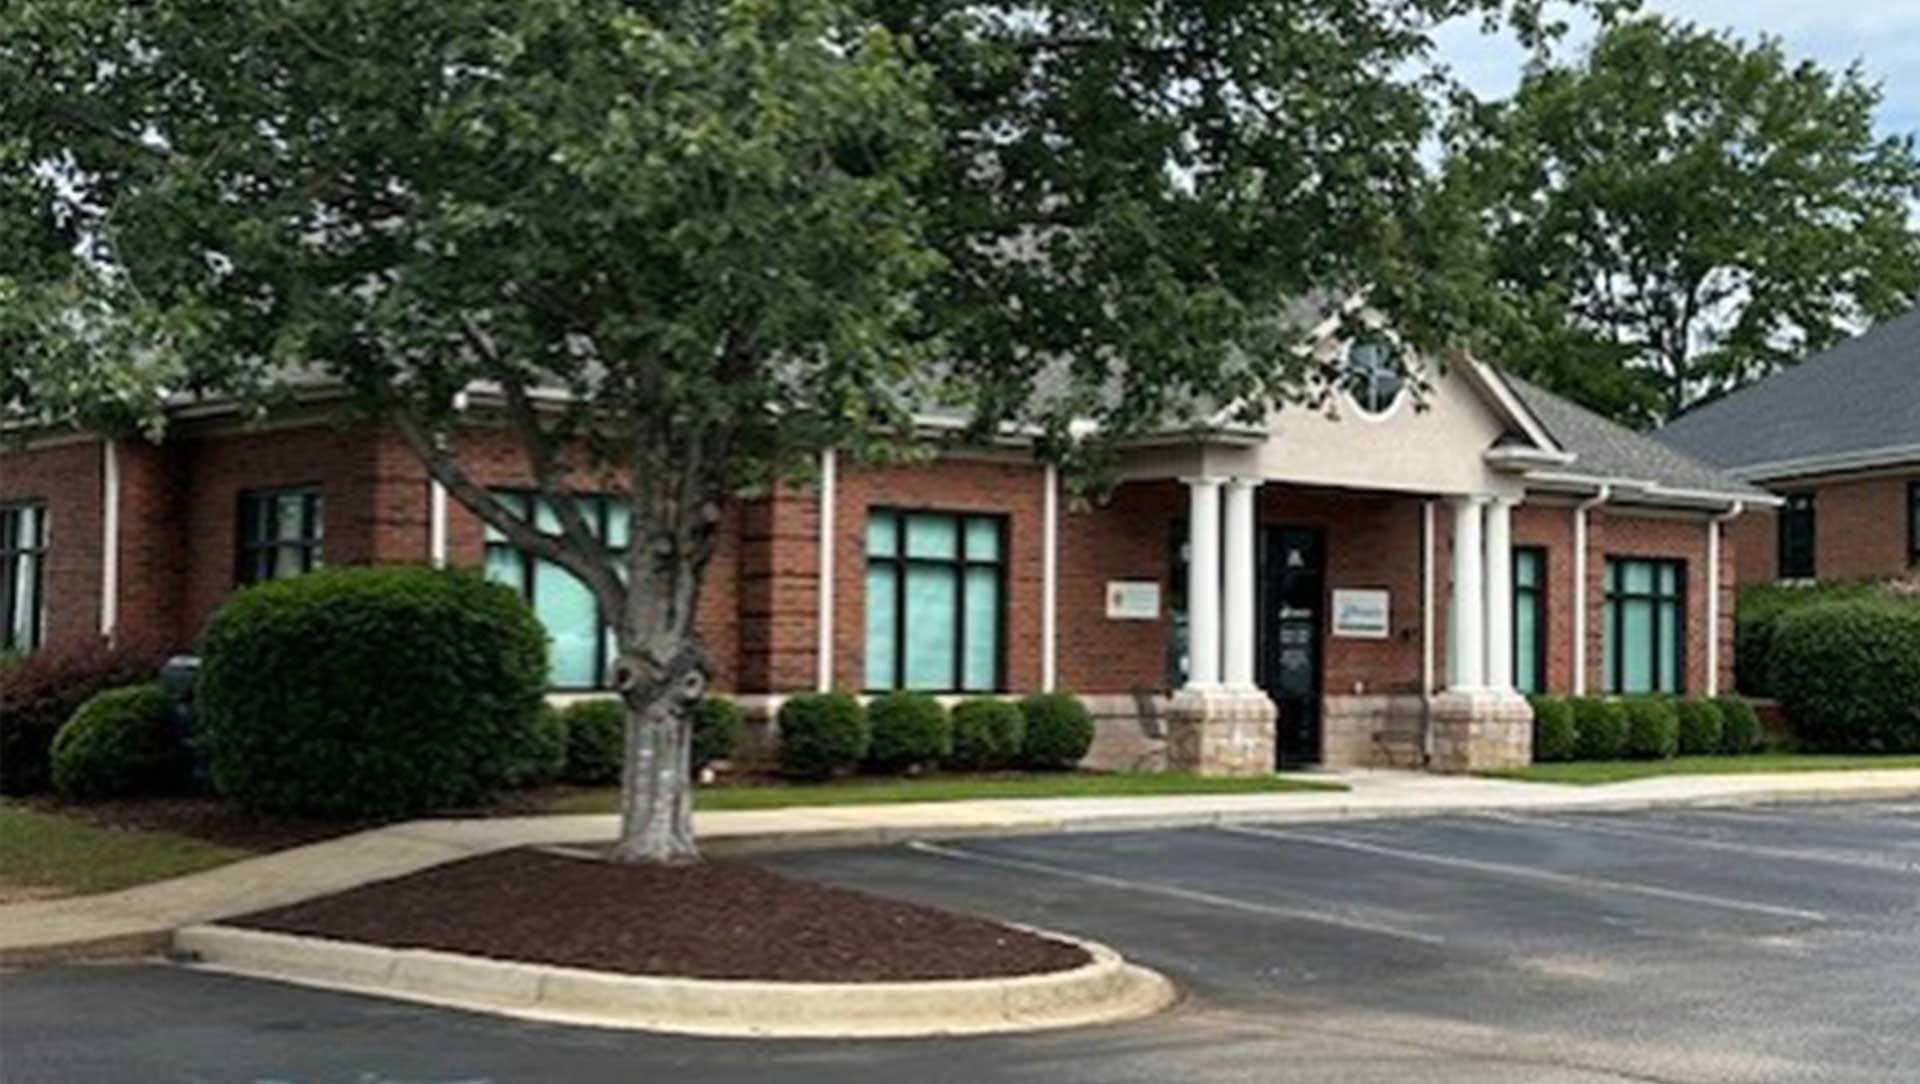
Brick office building with white columns, green awnings, and a tree-lined parking lot
By By Mark Turley, Owner — Priority Insurance LLC • August 11, 2026
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Show More