Essential Business Insurance Coverages Every Company Should Have
January 22, 2026
Business meeting in an office with “Essential Business Insurance Coverages” text and Priority Insurance logo.

Every business faces risks that can lead to lawsuits, property damage, income loss, or operational shutdowns—and the right insurance coverages are designed to absorb those shocks. Essential business insurance creates a safety net that protects cash flow, reputation, and long-term viability. In our years of professional service advising business owners in Greenville, SC, we’ve seen how properly structured coverage turns unexpected setbacks into manageable events.


Why Business Insurance Is a Necessity, Not a Luxury

No matter the size or industry, every business operates with exposure. Accidents happen, property is damaged, and claims arise—often without warning. Business insurance exists to transfer those risks away from the company and onto an insurer, protecting owners from catastrophic financial loss.


Operating without adequate coverage can place personal assets, future revenue, and the business itself at risk.


General Liability Insurance: The Foundation of Protection

General liability insurance is the cornerstone of most business insurance programs.


What General Liability Typically Covers

This coverage may help protect against:

  • Third-party bodily injury claims
  • Property damage caused by business operations
  • Legal defense costs
  • Settlements or court judgments


Even simple incidents—like a customer slipping on a wet floor—can result in expensive claims without liability coverage in place.


Commercial Property Insurance: Protecting Physical Assets

Business property represents a significant investment that needs protection.


What Commercial Property Insurance Covers

This policy generally helps pay for damage to:

  • Buildings owned or leased
  • Equipment and machinery
  • Inventory and supplies
  • Furniture, fixtures, and signage


Covered losses often include fire, theft, vandalism, and certain weather events. Without this coverage, replacing damaged assets can severely disrupt operations.


Business Interruption Insurance: Income Protection During Downtime

Property damage often leads to temporary closures.


Why Business Interruption Coverage Is Critical

This coverage may help replace:

  • Lost income during shutdowns
  • Ongoing expenses like rent and payroll
  • Extra costs to resume operations faster


For businesses that rely on steady customer flow near areas like Falls Park on the Reedy or along Haywood Road, even short interruptions can have a major financial impact.


Workers’ Compensation Insurance: Protecting Employees and Employers

If your business has employees, workers’ compensation insurance is often required.


What Workers’ Compensation Typically Covers

This coverage generally provides:

  • Medical care for work-related injuries
  • Partial wage replacement during recovery
  • Rehabilitation service
  • Protection against most employee injury lawsuits


Beyond compliance, workers’ compensation supports employee trust and workplace stability.


Commercial Auto Insurance: Managing Driving Risks

Any business that uses vehicles faces added exposure.


Why Commercial Auto Coverage Is Essential

Commercial auto insurance may help cover:

  • Liability from accidents involving business vehicles
  • Damage to company-owned or leased vehicles
  • Medical expenses related to auto accidents


Personal auto policies often exclude business use, leaving dangerous gaps if the wrong coverage is in place.


Professional Liability Insurance: Errors and Omissions Coverage

Some risks aren’t physical—they’re professional.


When Professional Liability Applies

Also known as errors and omissions insurance, this coverage may help if a client alleges:

  • Negligence
  • Mistakes in professional services
  • Failure to meet contractual obligations


Even unfounded claims can be expensive to defend without proper coverage.


Cyber Liability Insurance: A Modern Essential

Digital exposure affects businesses of all sizes.


What Cyber Liability Insurance Can Address

Cyber coverage may help with:

  • Data breach response costs
  • Customer notification expenses
  • Legal claims related to compromised data
  • Business interruption from cyber incidents


In our professional experience, small businesses are often targeted because they’re less prepared.


Business Owner’s Policy (BOP): Bundled Protection

Many businesses benefit from bundling core coverages.


What a BOP Typically Includes

A Business Owner’s Policy often combines:

  • General liability insurance
  • Commercial property insurance
  • Optional business interruption coverage


Bundling can reduce costs and simplify insurance management while closing common coverage gaps.


Employment Practices Liability Insurance (EPLI)

Employee-related claims extend beyond injuries.


What EPLI Helps Protect Against

EPLI may help cover claims involving:

  • Wrongful termination
  • Discrimination or harassment
  • Retaliation allegations


As workforces grow, this coverage becomes increasingly relevant.


How Coverage Needs Vary by Business Type

No two businesses face identical risks.


Factors That Influence Coverage Needs

Insurance should reflect:

  • Industry and operations
  • Customer interaction level
  • Number of employees
  • Revenue size
  • Physical vs. service-based work


In Greenville, SC, businesses ranging from professional offices to contractors often require different coverage combinations to stay protected.


Common Coverage Gaps Business Owners Overlook

Many businesses are underinsured without realizing it.


Frequent Gaps We See

These often include:

  • Insufficient liability limits
  • Missing business interruption coverage
  • No cyber liability protection
  • Relying on personal auto insurance for work vehicles


Gaps usually surface only after a claim is denied or limited.


Contract and Client Requirements

Insurance is often required to do business.


Why Adequate Coverage Matters for Contracts

Clients, landlords, and lenders may require:

  • Proof of insurance
  • Specific coverage limits
  • Additional insured endorsements


Lacking required coverage can delay projects or disqualify businesses from opportunities.


Reviewing Coverage as Your Business Evolves

Business insurance should grow with your operations.


When to Reevaluate Your Coverage

Reviews are especially important when:

  • Hiring employees
  • Expanding services
  • Purchasing equipment
  • Moving locations


In Greenville, SC, growing businesses that review coverage annually are far less likely to face uninsured losses.


The Cost of Being Underinsured

Choosing minimal coverage to save money can backfire.


Long-Term Consequences of Inadequate Coverage

Underinsured businesses may face:

  • Out-of-pocket legal costs
  • Extended downtime
  • Loss of clients or contracts
  • Permanent financial damage


Premium savings rarely outweigh the cost of uncovered claims.


Business Insurance as a Strategic Asset

Insurance is more than compliance—it’s a strategic tool. Proper coverage supports resilience, credibility, and long-term planning, allowing owners to focus on growth instead of risk.


At Priority Insurance LLC, we put our clients first by offering them policies that they can afford. Having insurance is a necessity nowadays, and we're here to help you out. Learn more about our products and services by calling our agency at (864) 297-9744. You can also request a quote by CLICKING HERE.


Priority Insurance LLC

 Address: Greenville, SC

 Phone: (864) 297-9744

 Website: https://www.priorityi.com/


Woman behind a café counter with glass pastry display and coffee equipment
October 13, 2026
Buy-sell agreements, key person insurance, and executive bonus plans for Upstate SC business owners. Protect your family, partners, and key people.
Interior wall with a large vertical crack and crumbled plaster exposing damage near the floor.
October 8, 2026
Most homeowners I sit down with in Greenville can tell me their deductible and roughly what their house is insured for. Very few can tell me whether they're covered if the ground shakes, or if the sewer line backs up into the house. That's not a knock on anybody — these are two coverages almost nobody thinks about until the day they need them. And on that day, a lot of people find out the answer is no.  Both earthquake damage and sewer or water backup are excluded on a standard homeowners policy. Both can usually be added back, often for a modest cost. Here's what I want every homeowner in the Upstate to understand about each one.
By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Night-lit two-story brick house with a balcony and warm exterior lights at night
September 17, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
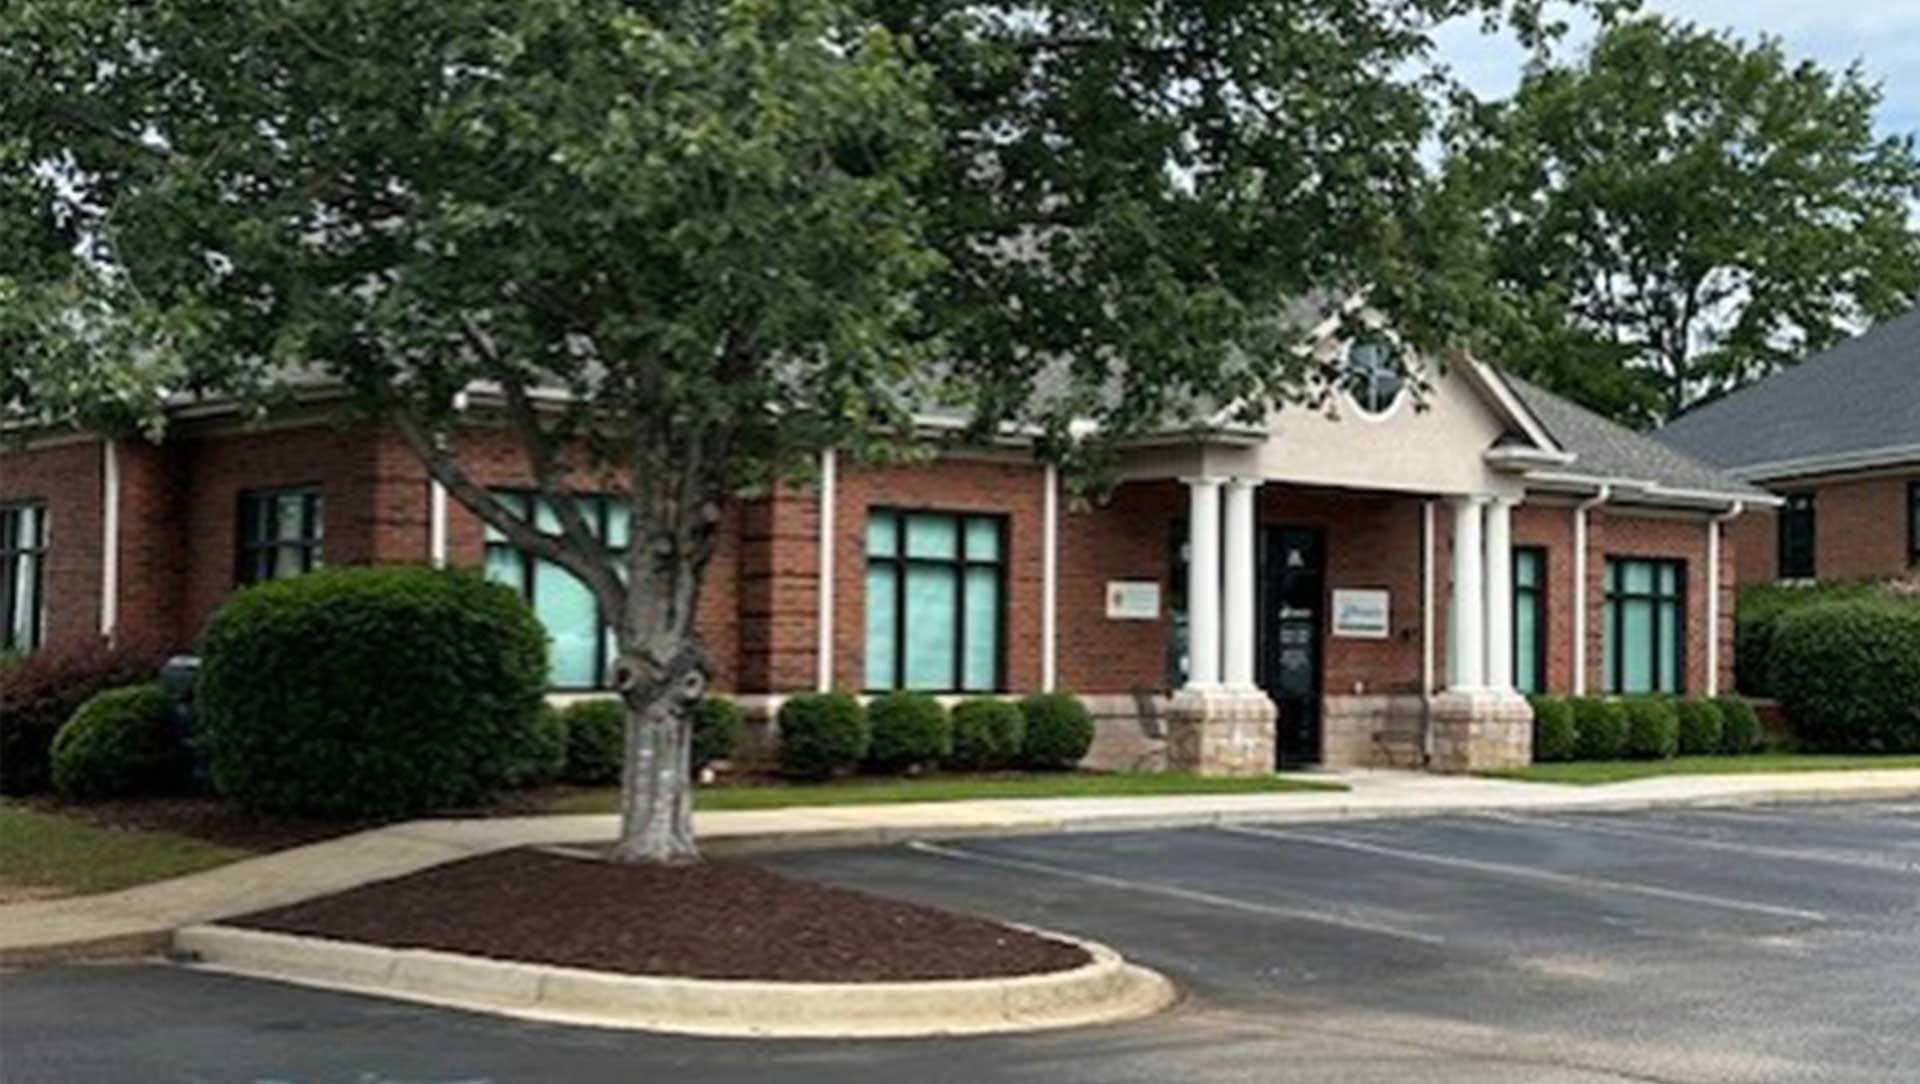
Brick office building with white columns, green awnings, and a tree-lined parking lot
By By Mark Turley, Owner — Priority Insurance LLC • August 11, 2026
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Show More