How To File An Auto Insurance Claim And What To Expect
January 14, 2026
Car interior with text “How to file an auto insurance claim” and a Priority Insurance logo

Filing an auto insurance claim involves promptly reporting the accident, documenting the damage, and working with an adjuster to resolve repairs or payments. Knowing what to expect at each step helps reduce stress and avoid delays. In our years of professional service assisting drivers in Greenville, SC, we’ve seen that informed policyholders experience smoother claims and better outcomes.


When You Should File an Auto Insurance Claim

Not every incident requires a claim, but certain situations almost always do. Understanding when to file helps protect your finances and your rights under the policy.

Situations That Typically Warrant a Claim

You should generally file a claim if:

  • There are injuries to you or others
  • Property damage is significant
  • Another party is involved and may file against you
  • Your vehicle is not drivable
  • Law enforcement is called to the scene


In our professional experience, delaying a necessary claim can complicate investigations and slow resolution.


Step One: Ensure Safety and Document the Scene

Your actions immediately after an accident matter.

What to Do at the Scene

After ensuring everyone is safe, you should:

  • Call emergency services if injuries are present
  • Move vehicles out of traffic if possible
  • Exchange information with other drivers
  • Take photos of vehicles, damage, and surroundings
  • Collect names and contact details of witnesses


Clear documentation strengthens your claim and reduces disputes later.


Step Two: Notify Your Insurance Company Promptly

Most policies require timely notice of accidents.

How to Report the Claim

Claims can usually be reported:

  • By phone
  • Through an insurer’s website
  • Via a mobile app


When reporting, be prepared to provide:

  • Policy information
  • Date, time, and location of the accident
  • Description of what happened
  • Information about other parties involved


In our years of professional service, prompt reporting often leads to faster inspections and repairs.


Step Three: Understanding the Claims Adjuster’s Role

Once a claim is opened, an adjuster is assigned.


What the Adjuster Does

The adjuster will:

  • Review accident details
  • Inspect vehicle damage
  • Determine fault if applicable
  • Evaluate repair or total loss value


The adjuster may contact you for additional information, so responsiveness is important.


Vehicle Inspection and Repair Estimates

After the initial review, the damage must be assessed.


How Damage Is Evaluated

Damage evaluation may involve:

  • Photos submitted electronically
  • In-person inspection
  • Estimates from approved repair shops


You may have the right to choose your repair shop, depending on state rules and policy terms.


Understanding Deductibles and Coverage

Before repairs begin, it’s important to understand how costs are shared.


What You’ll Likely Pay

  • Your deductible is usually paid out of pocket
  • The insurer pays remaining covered costs up to policy limits


Higher deductibles lower premiums but increase out-of-pocket expense during claims.


Rental Cars and Temporary Transportation

Many drivers worry about transportation during repairs.


When Rental Coverage Applies

Rental reimbursement may help cover:

  • A rental car while repairs are completed
  • Transportation after a total loss


Coverage limits and daily caps vary by policy, so reviewing this section in advance is helpful.


What Happens If Your Car Is Declared a Total Loss

Not all vehicles are repairable.


How Total Loss Decisions Are Made

A vehicle is typically declared a total loss when:

  • Repair costs exceed a percentage of vehicle value
  • Damage compromises safety


In these cases, insurers usually pay the actual cash value of the vehicle, minus your deductible.


Claims Involving Fault and Liability

Fault affects how claims are handled and which coverage applies.


If You Are At Fault

Your liability coverage may:

  • Pay for damage to others’ vehicles
  • Cover injuries to other parties
  • Provide legal defense if needed


If You Are Not At Fault

Your insurer may:

  • Pursue reimbursement from the at-fault party
  • Recover your deductible through subrogation


In Greenville, SC, fault determinations often rely on police reports, statements, and physical evidence.


Common Delays and How to Avoid Them

Some claims take longer than expected.


Factors That Can Slow Claims

Delays often occur due to:

  • Incomplete documentation
  • Difficulty contacting involved parties
  • Disputes over fault
  • Repair shop backlogs


Staying responsive and organized helps keep the process moving.


Communication During the Claims Process

Clear communication improves outcomes.


Best Practices for Policyholders

You should:

  • Respond promptly to adjuster requests
  • Keep records of all conversations
  • Ask questions if anything is unclear
  • Review settlement offers carefully


In our professional experience, proactive communication reduces misunderstandings and frustration.


Claims Impact on Future Premiums

Many drivers worry about rate increases.


What Typically Affects Premium Changes

Premiums may be influenced by:

  • Fault determination
  • Claim frequency
  • Severity of the loss


Not every claim results in a rate increase, especially if you are not at fault.


When to Seek Additional Guidance

Some claims are more complex.


Situations That May Require Extra Help

You may want professional guidance if:

  • Liability is disputed
  • Injuries are involved
  • The settlement seems insufficient


Drivers navigating busy areas near Falls Park on the Reedy or along Haywood Road often benefit from understanding coverage details before issues arise.


Preparing Before an Accident Happens

The best time to understand claims is before you need one.


Steps to Take Now

You should:

  • Review your coverage limits
  • Understand deductibles and exclusions
  • Keep insurer contact info accessible
  • Know your rental and roadside benefits


Preparation reduces stress when accidents occur.


Filing a Claim with Confidence

Filing an auto insurance claim doesn’t have to be overwhelming. When you know the steps, understand your coverage, and communicate clearly, the process becomes far more manageable.


At Priority Insurance LLC, we put our clients first by offering them policies that they can afford. Having insurance is a necessity nowadays, and we're here to help you out. Learn more about our products and services by calling our agency at (864) 297-9744. You can also request a quote by CLICKING HERE.


Priority Insurance LLC

 Address: Greenville, SC

 Phone: (864) 297-9744

 Website: https://www.priorityi.com/

Woman behind a café counter with glass pastry display and coffee equipment
October 13, 2026
Buy-sell agreements, key person insurance, and executive bonus plans for Upstate SC business owners. Protect your family, partners, and key people.
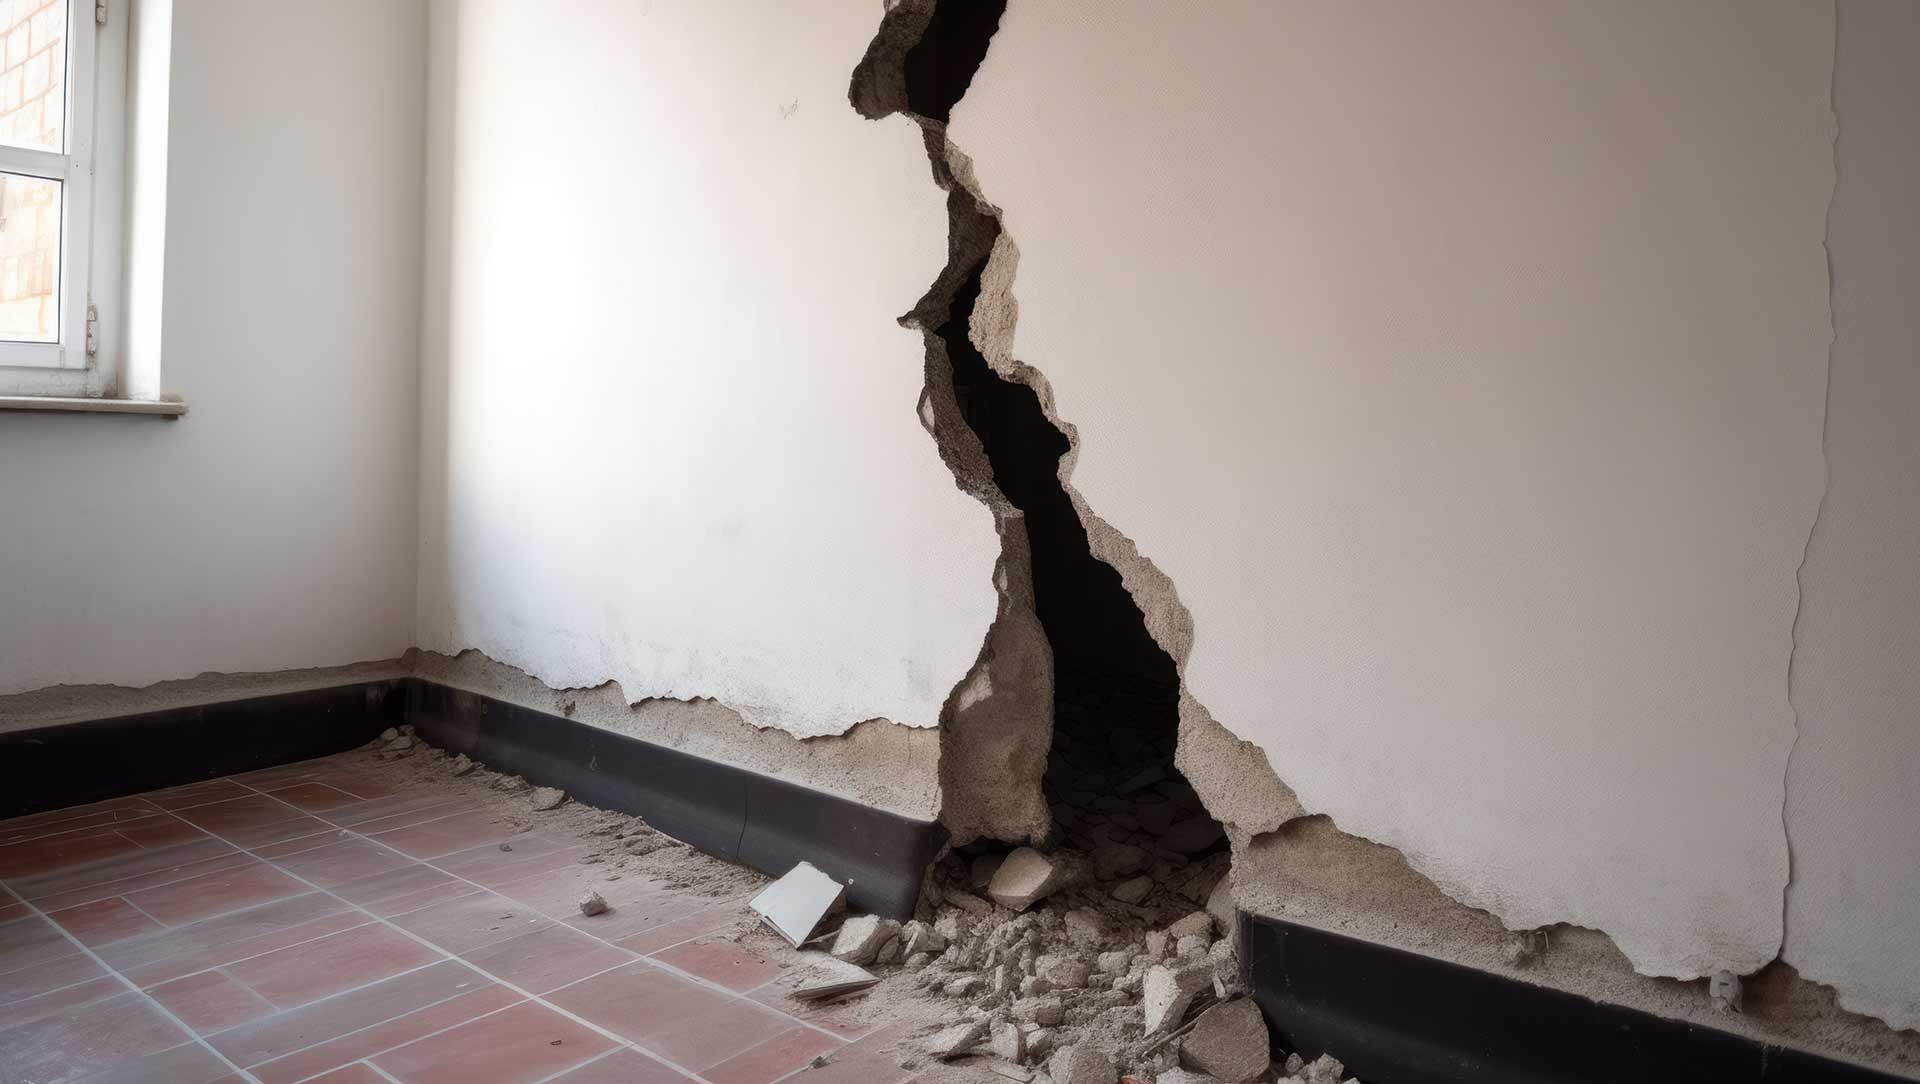
Interior wall with a large vertical crack and crumbled plaster exposing damage near the floor.
October 8, 2026
Most homeowners I sit down with in Greenville can tell me their deductible and roughly what their house is insured for. Very few can tell me whether they're covered if the ground shakes, or if the sewer line backs up into the house. That's not a knock on anybody — these are two coverages almost nobody thinks about until the day they need them. And on that day, a lot of people find out the answer is no.  Both earthquake damage and sewer or water backup are excluded on a standard homeowners policy. Both can usually be added back, often for a modest cost. Here's what I want every homeowner in the Upstate to understand about each one.
By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Night-lit two-story brick house with a balcony and warm exterior lights at night
September 17, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
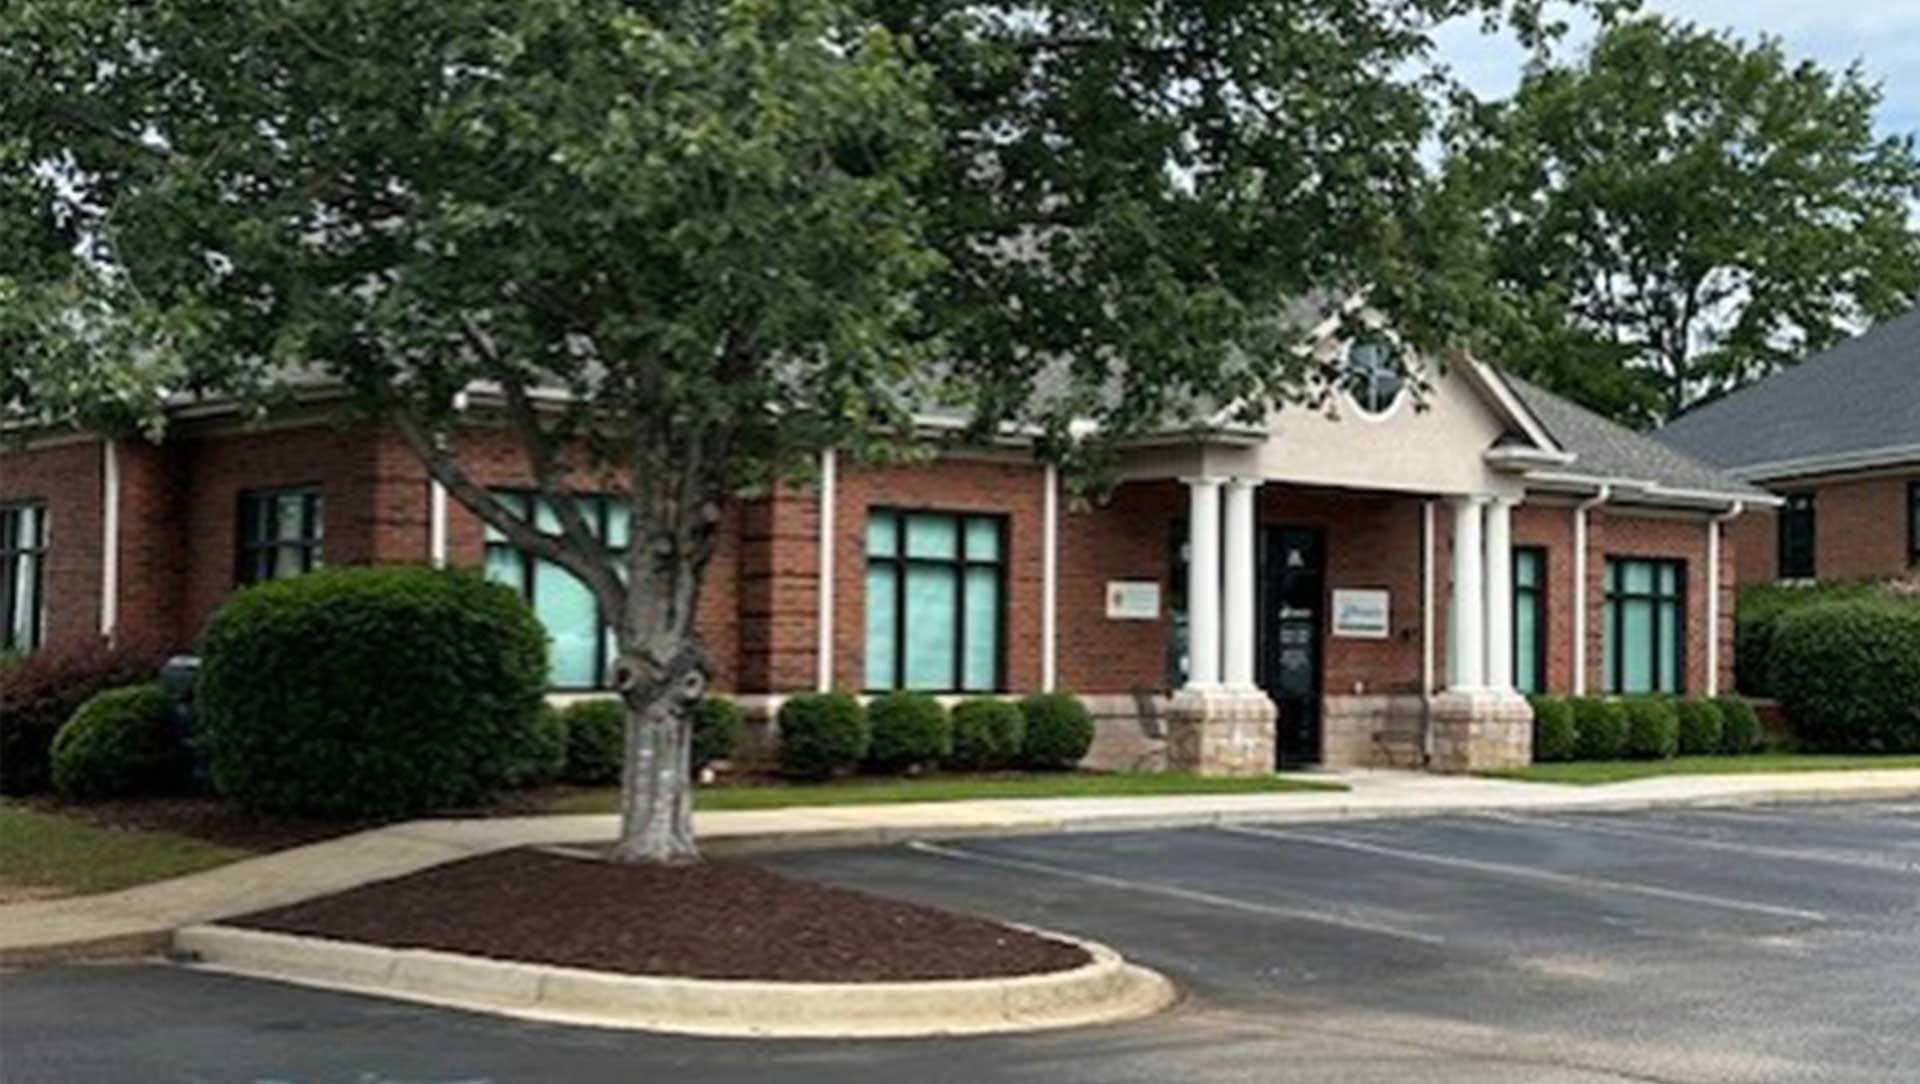
Brick office building with white columns, green awnings, and a tree-lined parking lot
By By Mark Turley, Owner — Priority Insurance LLC • August 11, 2026
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Show More