

Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into. So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
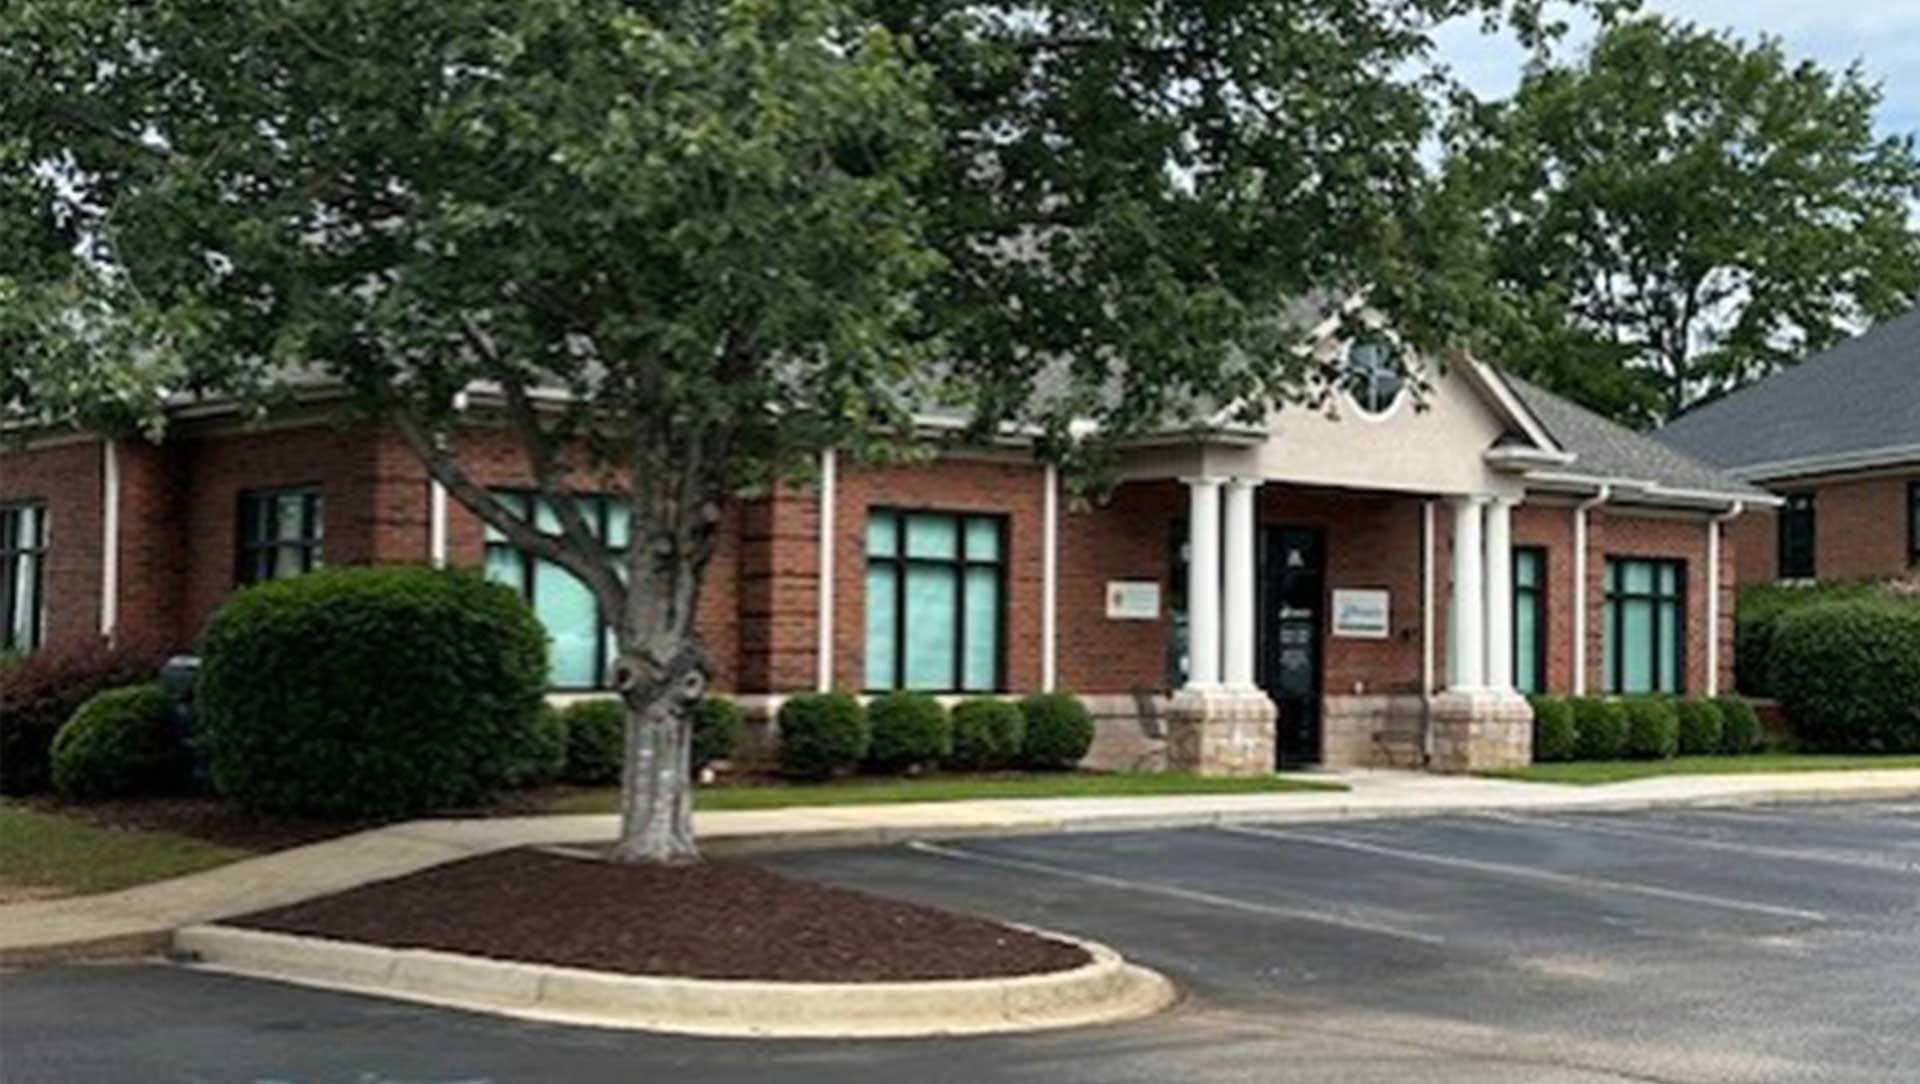
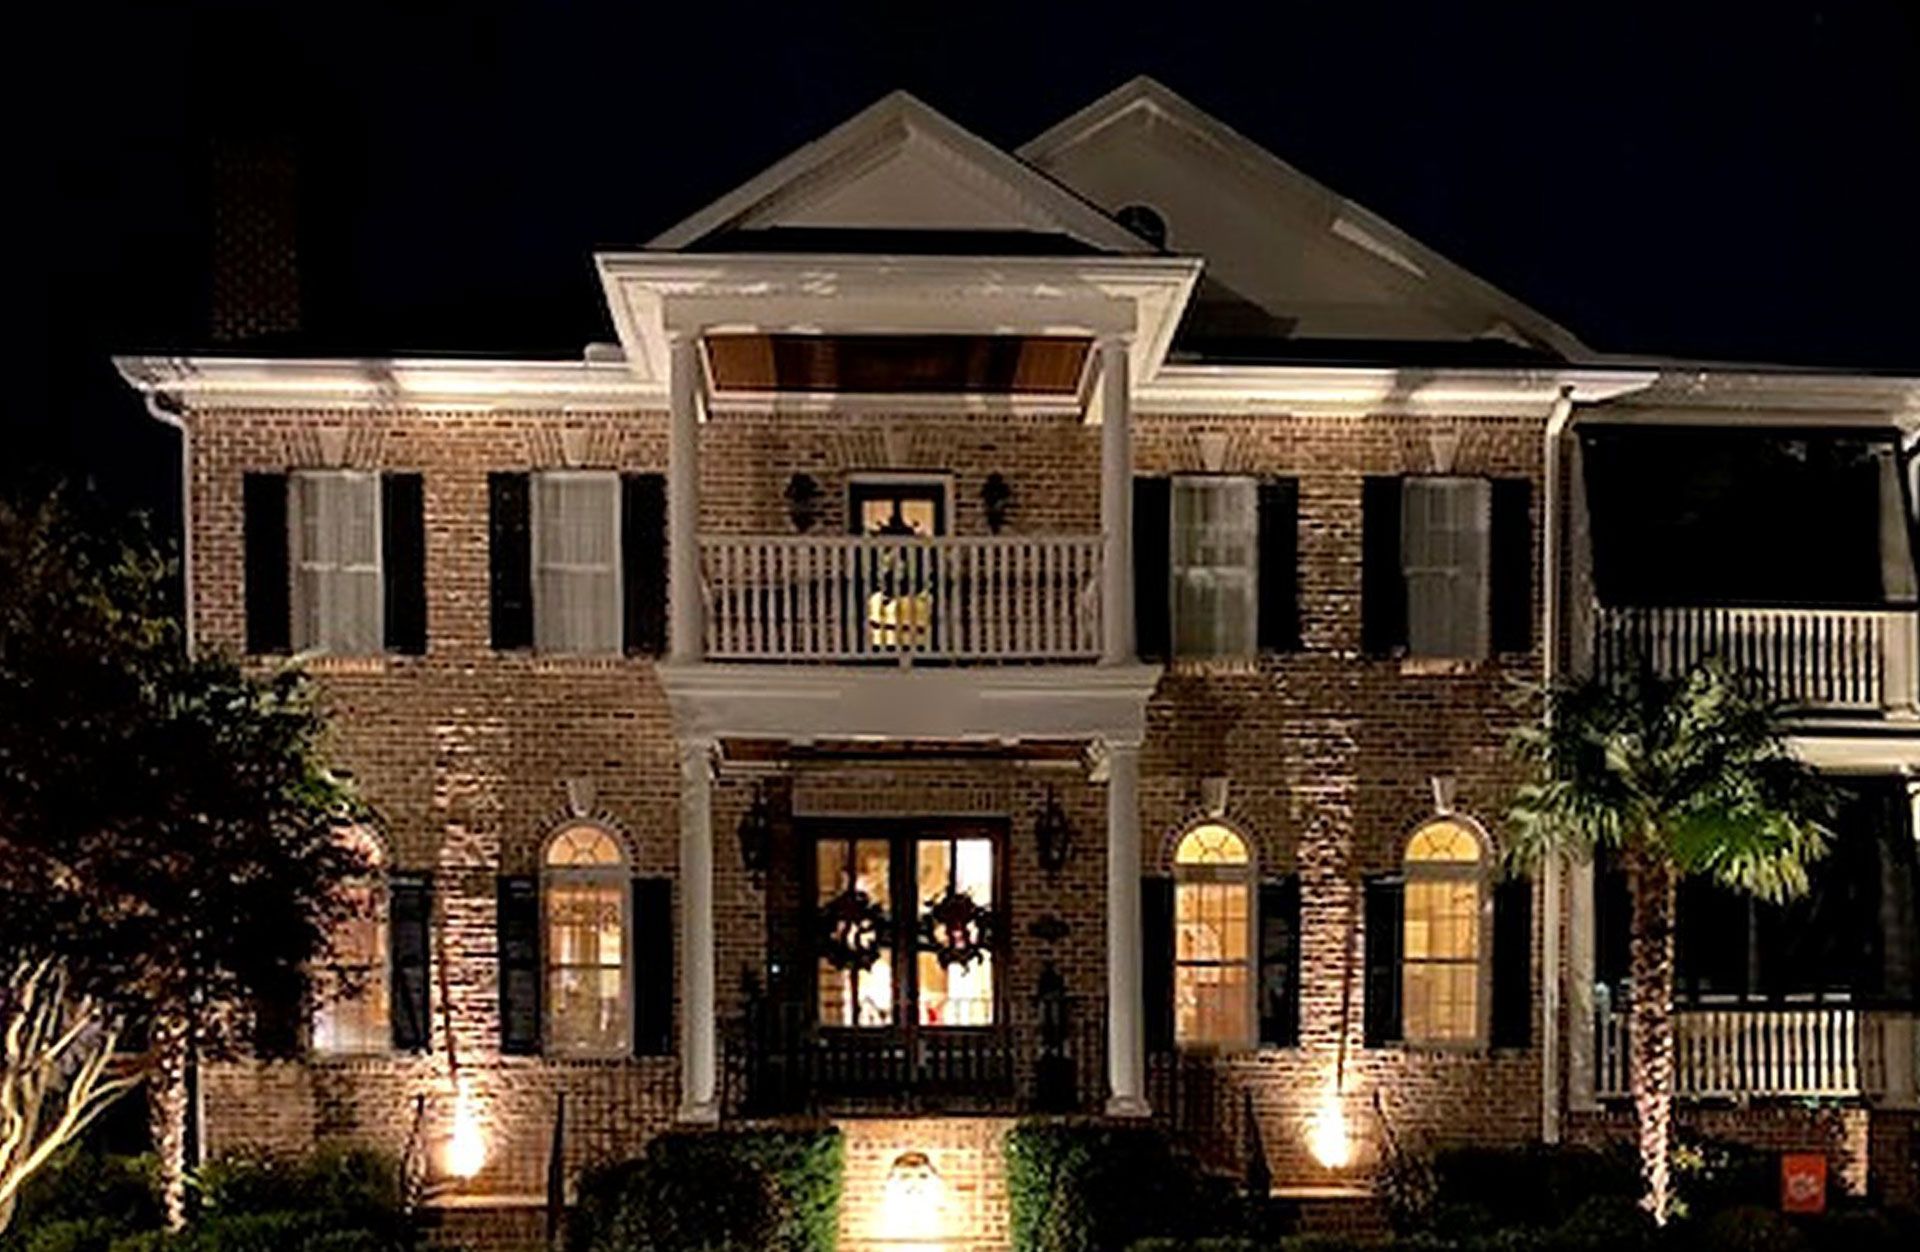
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Mark Turley, owner of Priority Insurance LLC, outside the agency's Greenville office.
As insurance agents, it’s our job at Priority Insurance to think about the worst case scenario. Most of the businesses that partner with us for their commercial insurance needs enjoy long stretches of “business as usual,” without much in the way of emergencies, injuries, or other events that would trigger an insurance claim. However, when that rare event does occur, the specific parameters of their business insurance could make the difference between recovering and going bankrupt. Umbrella liability insurance for business owners is a powerful product that provides peace of mind about those unexpected events. To let you know just how valuable this insurance is, here are a few examples of “worst case scenarios” that are more common than you might think. Each example is an event that would not be covered under more traditional types of commercial insurance, so a business owner without an umbrella insurance policy could end up facing thousands of dollars in costs out of pocket. Non-Employee Injury Most business owners are familiar with how workers compensation insurance works, and even with a small business employing only a few people, it’s likely to be in place to protect the owner if an employee is hurt while on the job. But what if someone who doesn’t work at your company is injured on the property? Even if your business is not a public-facing company like a grocery store or restaurant, you most likely have members of the public at your location occasionally. Service providers such as custodial and delivery workers are in and out on a regular basis, and the area outside your building comes into play as well. If one of these people happens to slip and fall while working in your building, or if a passerby is injured by a falling tree limb on your property, things can get complicated very quickly. Avoiding a prolonged legal proceeding is in the business owner’s best interest, and umbrella liability insurance for the business can ensure that the organization can continue to focus on growth, rather than getting sidetracked and having resources drained by a lawsuit. Intellectual Property Lawsuit Copyright infringement is most familiar to the public in the field of entertainment. Occasionally one pop music star will sue another for releasing a song that is suspiciously similar to one of their own. But this situation is not limited to the arts. Small businesses sometimes attract the attention of other organizations when they unwittingly publicize a new logo, slogan, or company name that closely resembles that of the larger company. In order to control their own reputation, these organizations will go after even small businesses to force them to change their intellectual property. In the worst case scenario, they may seek restitution for damages that they perceive. Even if the infringement was unintentional, unraveling the problem could cost a lot of money, which a larger organization may be able to spare but the small business cannot. This type of situation can be avoided with an umbrella liability insurance policy, and your agent at Priority Insurance can help you make sure you’re covered if an event like this ever comes up in connection with your business’s intellectual property. Unexpected Employee Actions Human beings are unpredictable, and that unpredictability can lead to any number of worst case scenarios for a small business. Even though you may have thoroughly vetted each employee on your company’s payroll, there’s no guarantee that those employees won’t someday do something that reflects back negatively on your organization. It could be something as simple as an innocent traffic accident while the employee is driving a company owned car. If another driver is injured in the accident, or if there is damage to a property where the employee is making a delivery, your company could be held liable for the expenses. Depending on the circumstances, the costs may or may not be covered by your company’s commercial auto policy. An umbrella liability insurance policy includes situations that are excluded by your auto policy to make sure that you don’t get stuck paying for damage out of pocket. Unfortunately, much larger issues can arise if an employee unexpectedly commits intentional damage while on your payroll. This is a true worst case scenario, and we all hope that the people we work with every day have one another’s best interests in mind. But it is not unheard of for an employee to suddenly act in a hostile, irrational manner and cause damage or injury to others. As catastrophic as the effects of such an action are to the people involved, they can also be catastrophic for the business that employs the individual. Although we hope none of our clients ever have to face this type of event, we help them make sure they are protected against it with umbrella liability insurance for business owners. Other Threats To a Business It would be impossible, of course, to list all the worst case scenarios that could crop up in the life of a business. That’s exactly why umbrella liability insurance was developed in the first place: to give business owners peace of mind as they begin investing in their organization. Without worrying about the possibility of a once-in-a-century weather event, an unpredictable action by someone, or an unintentional infringement on a powerful company’s intellectual property, a business owner is free to focus on advancing the company’s interests. How confident are you that your organization is ready to withstand whatever comes your way? You can increase that level of confidence by reviewing your business insurance policies with an expert at Priority Insurance. We’ll take a look at all aspects of your business and give you our best advice about what kind of insurance you should hold, what coverages you should have, and what you can do to avoid these and other worst case scenarios in the life of your business. In the Upstate region of South Carolina, contact Priority Insurance today to set up a consultation with a business insurance professional.