Comprehensive Coverage: Protecting Against Theft And Damage
November 20, 2025
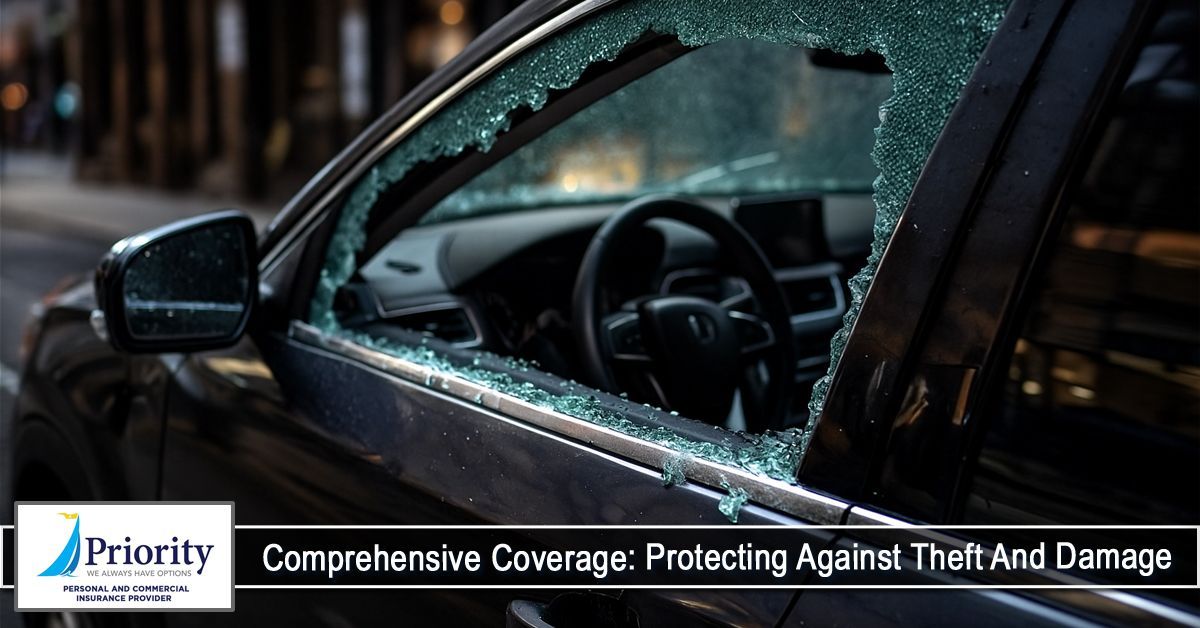
Car with shattered window.

Auto insurance is more than just a requirement—it’s a safeguard for your vehicle and financial peace of mind. But while many drivers understand liability coverage, fewer realize how important comprehensive coverage can be. This type of insurance protects your vehicle from losses not caused by a collision, making it an essential part of a strong auto policy.


From theft to weather damage, comprehensive coverage helps ensure you’re not left with major repair or replacement costs when unexpected events occur.


What Is Comprehensive Coverage?

Comprehensive coverage is an optional auto insurance protection that covers damage to your vehicle from events other than collisions. It focuses on losses that are usually sudden, accidental, and outside your control.

Comprehensive coverage generally includes protection from:

  • Theft
  • Vandalism
  • Fire damage
  • Falling objects (like tree limbs)
  • Natural disasters (hail, windstorms, flooding)
  • Animal-related collisions (e.g., hitting a deer)
  • Glass damage (windshield cracks, shattered windows)


This coverage helps repair or replace your vehicle up to its current market value, minus your chosen deductible.


Why Comprehensive Coverage Matters

Even the safest drivers can’t control everything on the road—or off it.

Without comprehensive coverage, you may be financially responsible for:

  • Replacing your vehicle if it’s stolen
  • Paying for body or paint damage caused by vandalism
  • Repairing flood, wind, or fire damage
  • Fixing a shattered windshield


Because these damages can be costly, comprehensive coverage offers financial protection and peace of mind.


When Is Comprehensive Coverage Especially Important?

Consider adding or maintaining comprehensive coverage if:

  • You park outside overnight
  • You live in an area prone to storms, flooding, or wildfires
  • Your neighborhood has a higher rate of vehicle theft or vandalism
  • You regularly drive in rural areas where animal collisions are more common
  • You lease or finance your vehicle (many lenders require it)


If your vehicle is newer or has a higher value, comprehensive coverage is often well worth the cost.

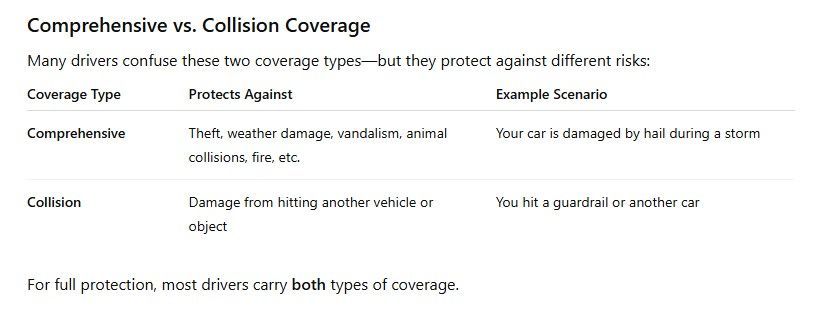
Comprehensive Collision Coverage

Local Insight for Greenville, SC Drivers

If you live in Greenville, SC, weather patterns can include heavy rain, hailstorms, and strong winds—conditions that can unexpectedly damage vehicles. Additionally, like any growing city, Greenville has areas where vehicle theft and vandalism are more common. Comprehensive coverage helps drivers in Greenville stay financially protected from these unpredictable events.


How to Choose the Right Deductible

Your deductible is the amount you pay out of pocket before insurance covers the rest.

Tips for selecting a deductible:

  • Higher deductible = lower monthly premium
  • Lower deductible = higher monthly premium
  • Choose an amount you can comfortably afford in an emergency


A common recommendation is $500–$1,000, depending on your budget and vehicle value.


Does Comprehensive Coverage Increase Your Rates?

Comprehensive coverage typically has a much smaller impact on rates compared to liability or collision coverage. The cost varies primarily based on:

  • Vehicle type and value
  • Location and weather risk
  • Claims history


For many drivers, the cost is modest compared to the potential out-of-pocket loss of an uncovered incident.


Conclusion

Comprehensive coverage is a smart and valuable addition to your auto insurance policy. It protects you from theft, weather damage, animal collisions, vandalism, and other unexpected events—things that even the safest driver can't prevent. By safeguarding your investment and reducing financial risk, comprehensive coverage ensures that you stay prepared for life’s unpredictability.


If you haven’t reviewed your auto policy recently, now is the perfect time to ensure you have the coverage you need—before a surprise event happens.


At Priority Insurance LLC, we put our clients first by offering them policies that they can afford. Having insurance is a necessity nowadays, and we're here to help you out. Learn more about our products and services by calling our agency at 
(864) 297-9744. You can also request a quote by CLICKING HERE.

Disclaimer: The information presented in this blog is intended for informational purposes only and should not be considered as professional advice. It is crucial to consult with a qualified insurance agent or professional for personalized advice tailored to your specific circumstances. They can provide expert guidance and help you make informed decisions regarding your insurance needs.​

Woman behind a café counter with glass pastry display and coffee equipment
October 13, 2026
Buy-sell agreements, key person insurance, and executive bonus plans for Upstate SC business owners. Protect your family, partners, and key people.
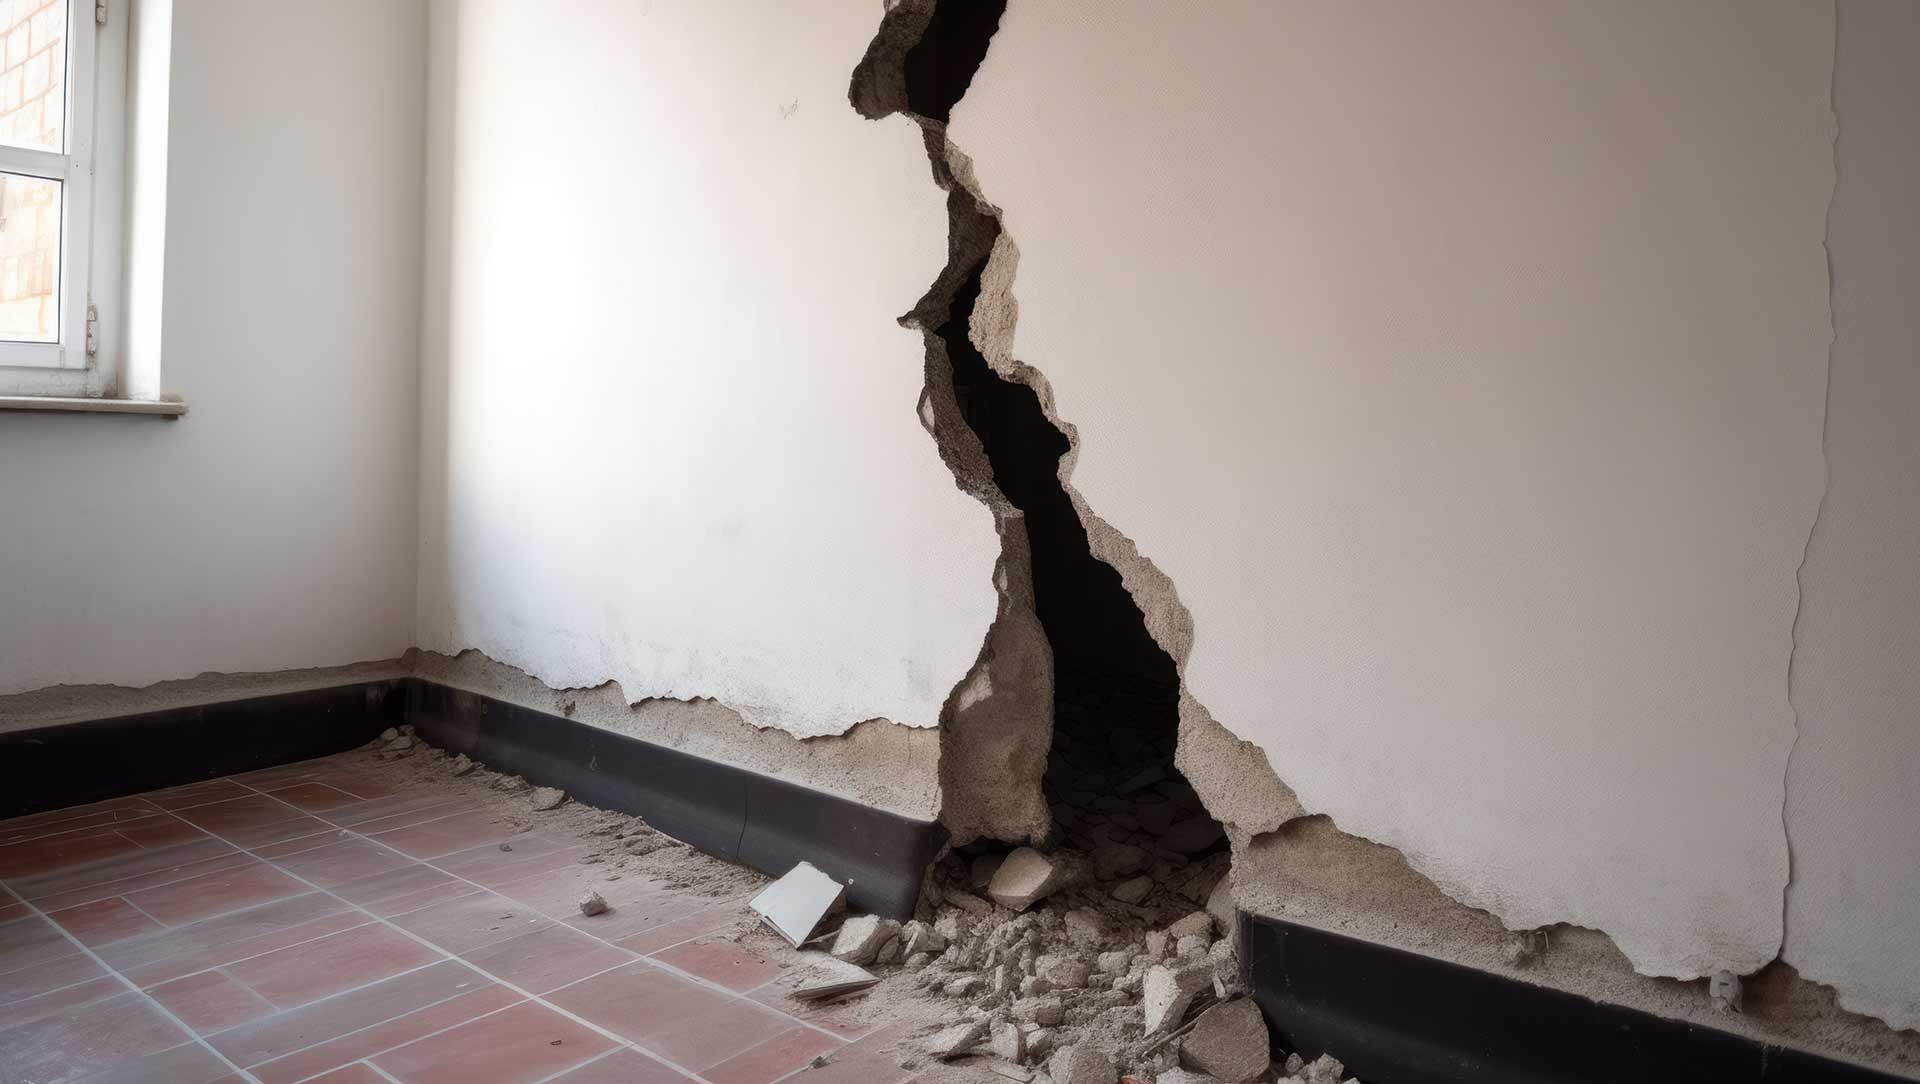
Interior wall with a large vertical crack and crumbled plaster exposing damage near the floor.
October 8, 2026
Most homeowners I sit down with in Greenville can tell me their deductible and roughly what their house is insured for. Very few can tell me whether they're covered if the ground shakes, or if the sewer line backs up into the house. That's not a knock on anybody — these are two coverages almost nobody thinks about until the day they need them. And on that day, a lot of people find out the answer is no.  Both earthquake damage and sewer or water backup are excluded on a standard homeowners policy. Both can usually be added back, often for a modest cost. Here's what I want every homeowner in the Upstate to understand about each one.
By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Night-lit two-story brick house with a balcony and warm exterior lights at night
September 17, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
Brick office building with white columns, green awnings, and a tree-lined parking lot
By By Mark Turley, Owner — Priority Insurance LLC • August 11, 2026
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Show More