The Business Owners Policy (BOP) in Greenville, South Carolina Protecting Both Sides of Your Business: Liability Lawsuits and the Building Itself
By Mark Turley, Owner — Priority Insurance LLC • August 11, 2026

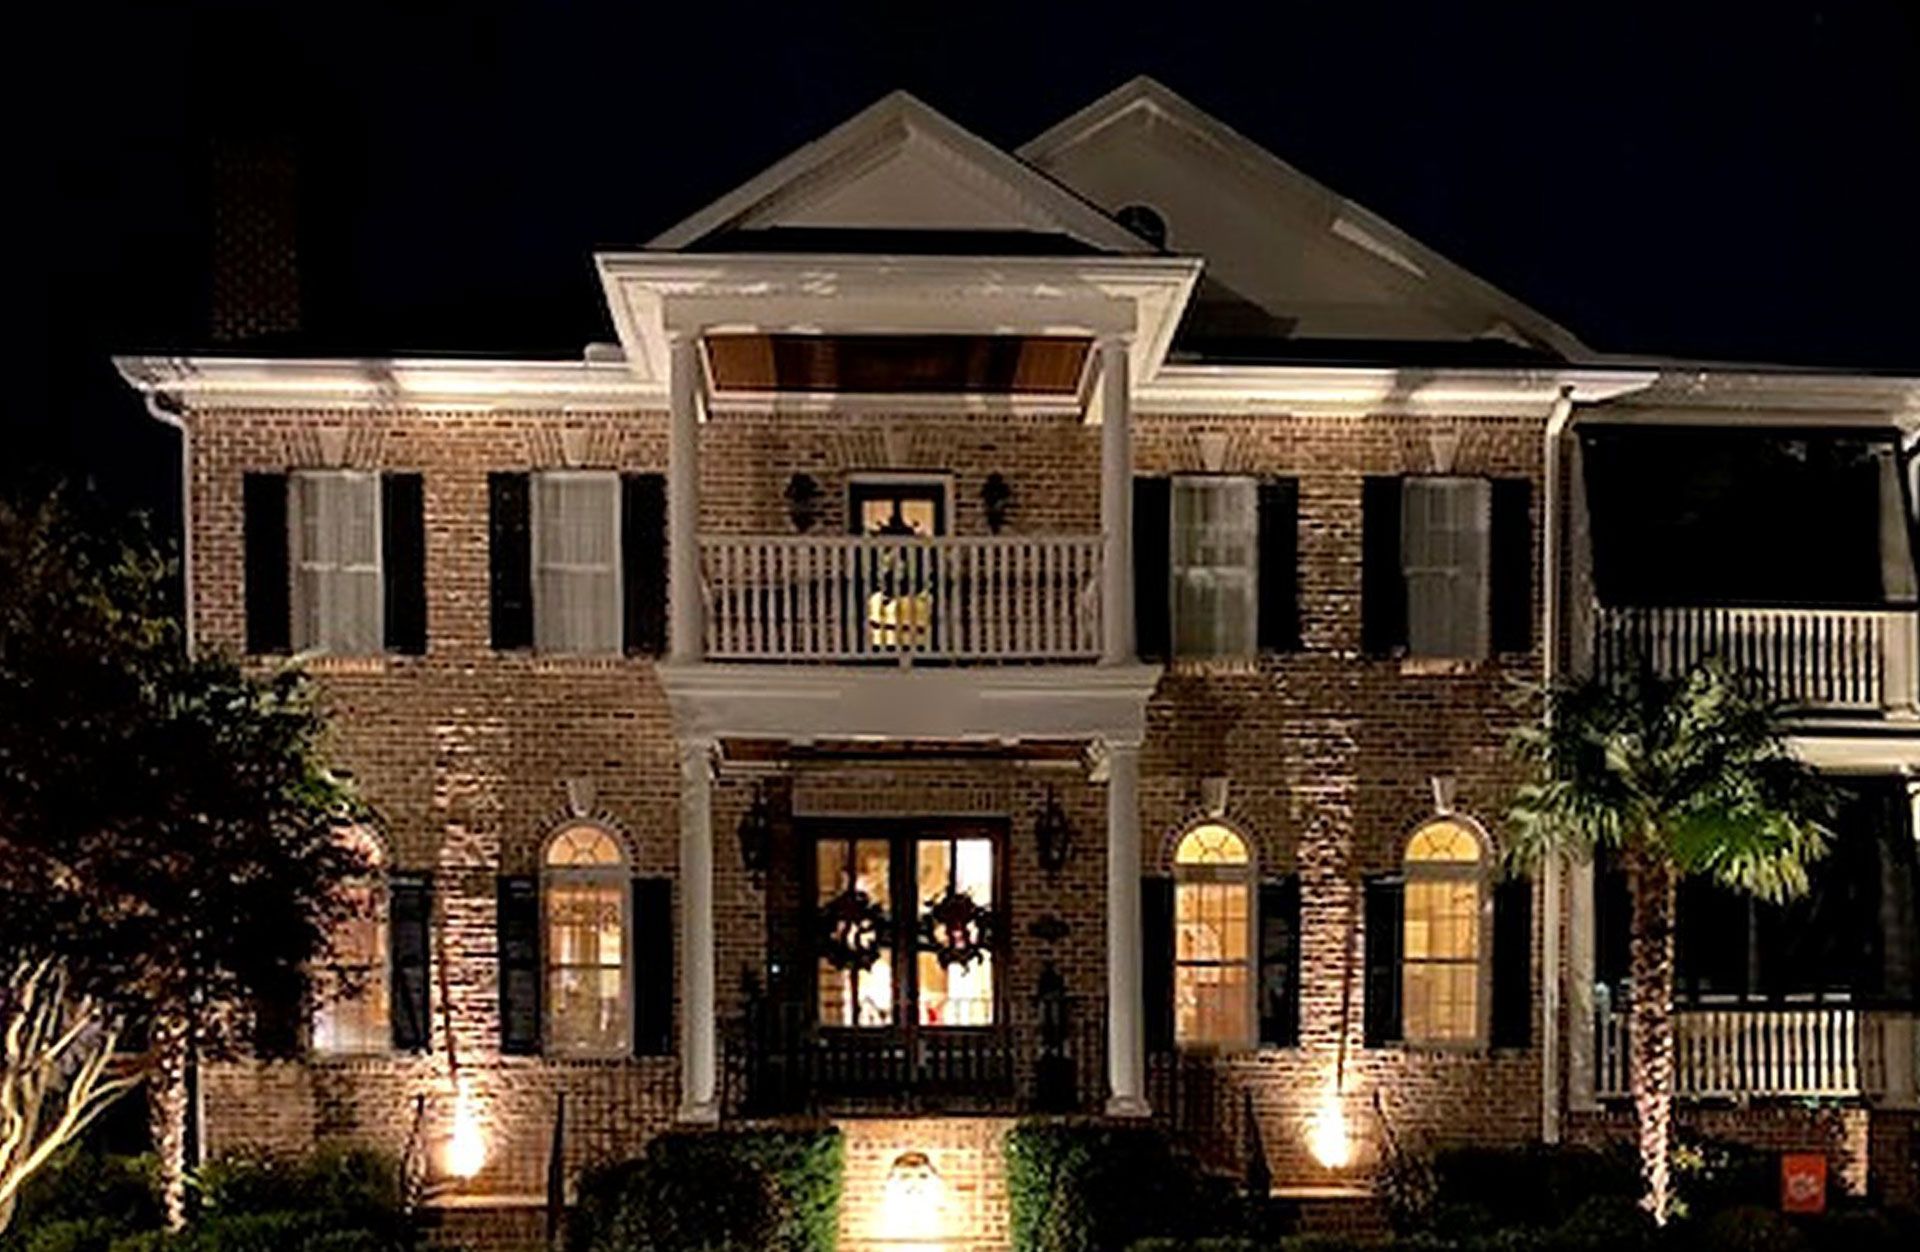
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.

2011

Serving the Upstate Since

Large

Carrier Partner Network

Local

Greenville-Based Agent

SC · NC · GA

Licensed In 3 States

The photo above is our office on Milestone Way in Greenville. I own that whole building, I stock it with equipment, I staff it, and every morning customers walk through the front door. If you own a business in the Upstate, you know exactly what that feels like — and you know that everything you have worked to build sits inside four walls that a single lawsuit, fire, or storm could threaten.


I'm Mark Turley, owner of Priority Insurance LLC. We have insured Greenville businesses since 2011, and the policy I want to walk you through today is the one most small and mid-sized businesses here should completely understand: the Business Owners Policy, or BOP. It bundles two very different kinds of protection — liability and property — into one policy, and in South Carolina's current climate, both halves matter more than they did a decade ago.

What a Business Owners Policy actually is

A BOP is a package built for eligible small-to-mid-sized businesses. Instead of buying your coverages piecemeal, it combines the essentials into one policy that is usually more affordable than the parts purchased separately. A BOP has three core pieces:


  • General liability — protects you when a third party (a customer, a vendor, a passerby) is injured or has their property damaged in connection with your business, and it pays your legal defense costs even when the claim is questionable.
  • Commercial property — covers your building and its contents: equipment, inventory, furniture, fixtures, and the improvements you have made to the space.
  • Business income — replaces lost income and covers ongoing bills if a covered event forces you to close temporarily.


A BOP does not include everything. Workers' compensation, commercial auto, and professional liability (errors & omissions) are separate policies. But for the core exposures most Greenville businesses face — getting sued and losing the building — the BOP is the foundation.

The liability half: why South Carolina's lawsuit climate should worry every business owner

Here in South Carolina, personal-injury advertising is relentless. Billboards along I-85 and I-385, radio spots, television commercials, sponsored search results — a large and aggressive plaintiff's bar is actively looking for people with claims against businesses. If a customer slips in your lobby, trips on a cracked sidewalk out front, or is hurt by something connected to your operation, there is a good chance a law firm will be interested.


South Carolina premises-liability law requires business owners to keep their property reasonably safe for the customers and visitors they invite in. The state uses a modified comparative-negligence rule and gives an injured person three years to file (S.C. Code § 15-3-530), and they can pursue economic damages, non-economic damages such as pain and suffering, and in some cases punitive damages. Here is the part business owners underestimate: even a claim you ultimately win costs you. Defending a premises case means attorneys, depositions, expert witnesses, and months of distraction — and the cost of defending personal-injury lawsuits has been climbing several percent a year.

You can do everything right and still get sued. General liability is what pays the lawyer to prove you did everything right.

And when a business does lose, the numbers have gotten frightening. Nationally, so-called “nuclear verdicts” — jury awards above $10 million — rose sharply in recent years, and the average large verdict now runs into the tens of millions. Plaintiff's attorneys use courtroom techniques like “anchoring” a jury to an enormous number, and a business with a building, equipment, and revenue looks like exactly the kind of defendant worth pursuing for every dollar above its policy limits.

The property half: the risk of losing the building

The other side of a BOP protects the physical business. Commercial property coverage pays to repair or rebuild your building and to replace the contents inside — the equipment, inventory, and fixtures that make the business run. In the Upstate, the everyday threats are fire, wind, hail, winter ice storms, vandalism, theft, and burst pipes.


What “all-risk” really means

People often ask me for “all perils” coverage. The accurate term is special form, sometimes called “all-risk” or “open perils.” It is the broadest property coverage available: instead of listing the specific events it covers, it covers all causes of loss except the ones it specifically excludes. That is a much stronger position than a “named perils” policy, which only pays if your loss matches one of the events on a list.


But “all-risk” does not mean everything. Two of the big exclusions are flood and earthquake, which require their own separate policies. Wear and tear, neglect, and a handful of other causes are excluded too. Part of my job is making sure you understand where the edges of your coverage are before a loss, not after.

Two settings that decide whether you actually recover: First, insure the building for replacement cost, not actual cash value, so depreciation is not subtracted from your check. Second, watch the coinsurance clause — if you insure the building for less than the required percentage of its value to save on premiums, the policy can penalize your claim payment. Getting these two right is the difference between rebuilding and being stuck.

The risk everyone forgets: losing the income, not just the building

If a fire closes your doors for four months, the building damage is only part of the loss. The rent or mortgage still comes due, payroll still matters, and the revenue simply stops. That is what business income coverage is for — it replaces the profit you would have earned and covers continuing expenses while you rebuild. For many owners, losing months of income is more devastating than the physical damage itself, and it is the coverage people most often discover they were short on.

How to structure a BOP that actually protects you

Here is the framework I use with business owners across the Upstate:

  • Match your liability limits to your exposure. A standard limit may be fine for a quiet office and dangerously low for a business with heavy foot traffic. The more customers through your door, the higher your limits should be.
  • Add a commercial umbrella. An umbrella stacks another layer of liability protection — often a million dollars or more — on top of your BOP for a modest cost. In a nuclear-verdict environment, this is basic protection, not a luxury.
  • Insure the building for what it would actually cost to rebuild. Under-insuring to shave the premium is the most expensive mistake a business owner can make — it can shrink the check you receive at claim time.
  • Don't skip business income. Make sure the coverage period is long enough to realistically rebuild and reopen.
  • Layer in what a BOP excludes. Flood, earthquake, workers' comp, commercial auto, and professional liability are separate — we make sure nothing important falls through the gap.

Serving businesses across Greenville and the Upstate

We write commercial coverage for businesses throughout the region: Greenville, Greer, Simpsonville, Mauldin, Taylors, Fountain Inn, Travelers Rest, Easley, Anderson, Spartanburg, and the surrounding communities. Because we are an independent agency, we are not tied to one company — we shop a large network of top-rated carrier partners to build the right BOP for your building, your operation, and your risk.

Why work with Priority Insurance

When you are protecting the business you have built, you should know exactly who is behind the advice. Priority Insurance has been an independent, locally owned agency in Greenville since 2011. We are licensed in South Carolina, North Carolina, and Georgia.


I run my business out of the same kind of building you do, in the same city, under the same South Carolina laws. I will sit down with you, look at your specific liability and property exposure, and tell you honestly whether your current policy is doing its job.

Is your business actually covered — liability and building?

Let's review your BOP and close the gaps before a claim or a storm finds them.


Mark Turley

Owner · Priority Insurance LLC

Mark Turley is the owner of Priority Insurance LLC, an independent insurance agency serving Greenville and the Upstate of South Carolina since 2011. Priority insures businesses and families across the region, is licensed in South Carolina, North Carolina, and Georgia, and shops a large network of top-rated carriers to match coverage to each client's real-world exposure. Reach the agency at 140 Milestone Way, Suite A, Greenville, SC 29615, or call (864) 297-9744.

Woman behind a café counter with glass pastry display and coffee equipment
October 13, 2026
Buy-sell agreements, key person insurance, and executive bonus plans for Upstate SC business owners. Protect your family, partners, and key people.
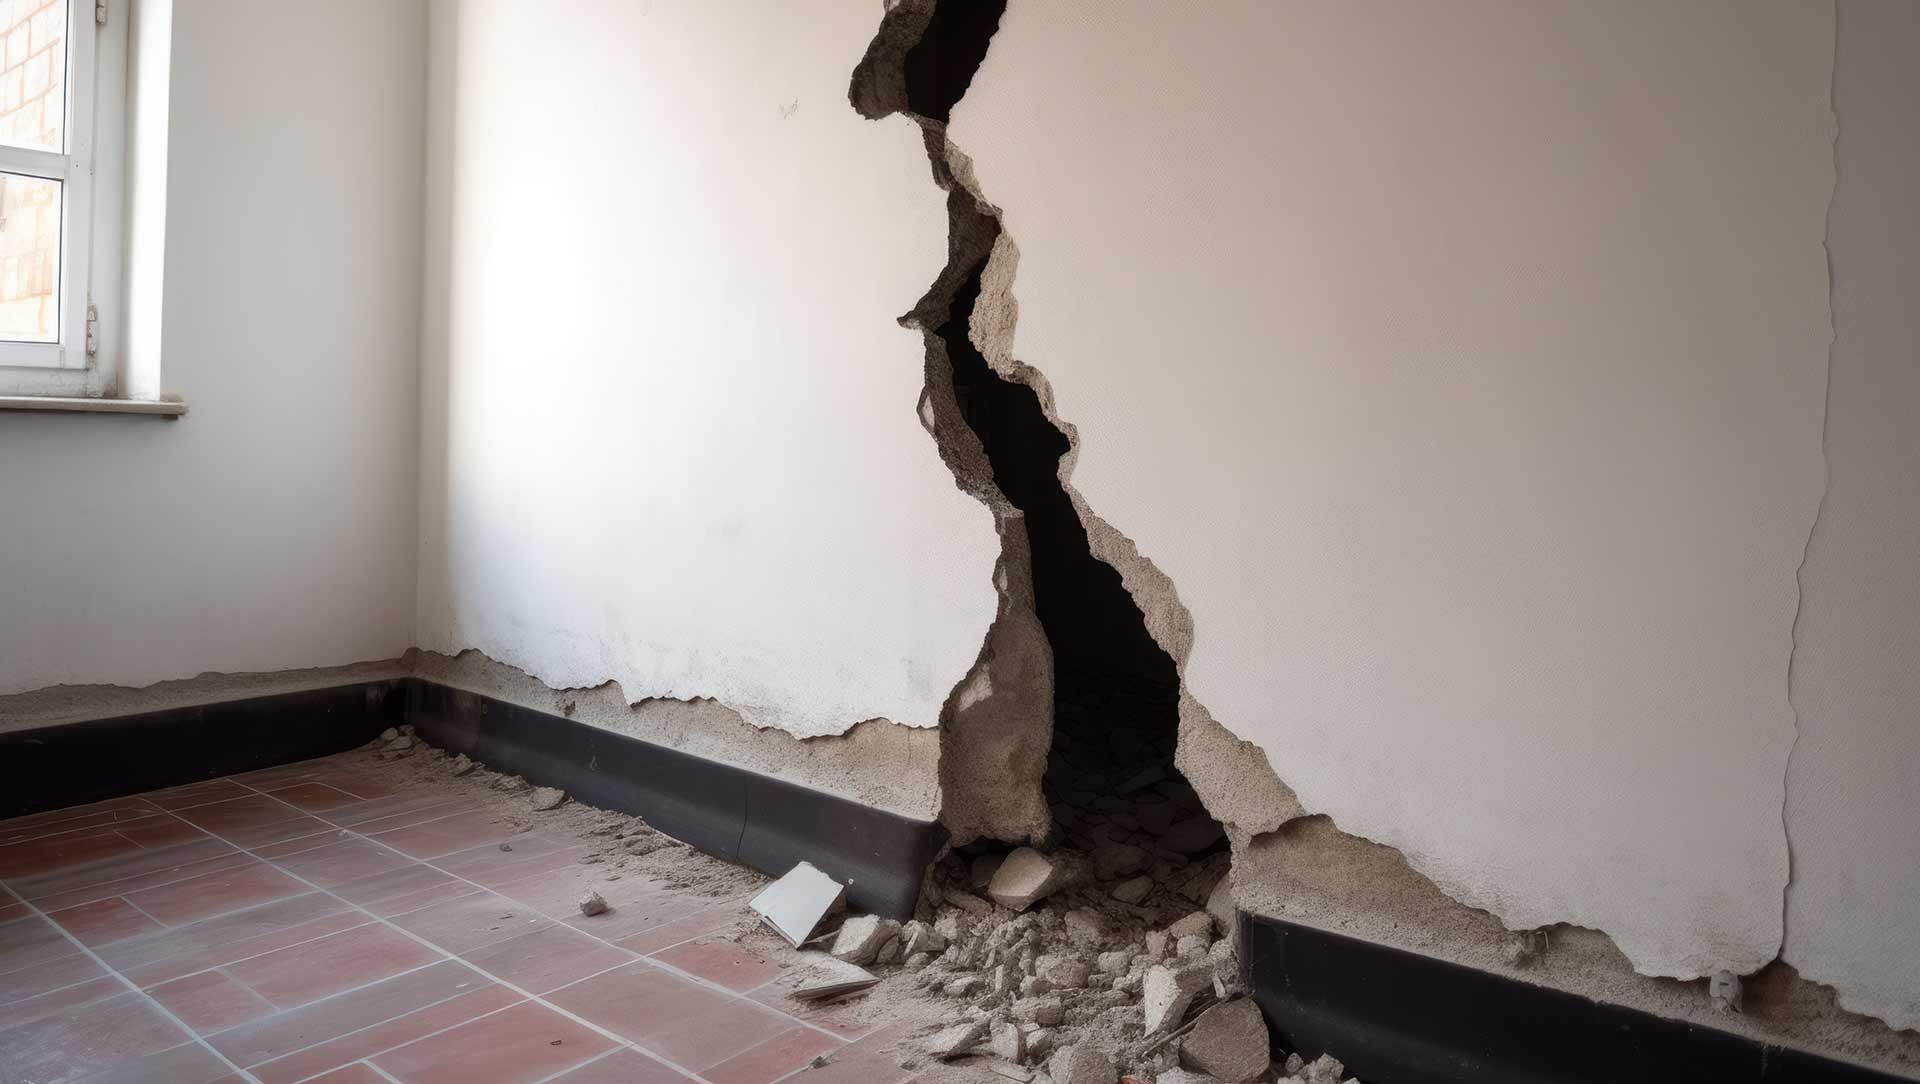
Interior wall with a large vertical crack and crumbled plaster exposing damage near the floor.
October 8, 2026
Most homeowners I sit down with in Greenville can tell me their deductible and roughly what their house is insured for. Very few can tell me whether they're covered if the ground shakes, or if the sewer line backs up into the house. That's not a knock on anybody — these are two coverages almost nobody thinks about until the day they need them. And on that day, a lot of people find out the answer is no.  Both earthquake damage and sewer or water backup are excluded on a standard homeowners policy. Both can usually be added back, often for a modest cost. Here's what I want every homeowner in the Upstate to understand about each one.
By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Night-lit two-story brick house with a balcony and warm exterior lights at night
September 17, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
Dark blue luxury SUV parked outside a building on a patterned driveway
By By Mark Turley, Owner — Priority Insurance LLC • August 4, 2026
Mark Turley, owner of Priority Insurance LLC, outside the agency's Greenville office.
Show More