A Quick Refresher On Auto Insurance Terms
PalmettoSoft • June 23, 2026
Tall palm tree silhouetted against a blue sky

For those of us who work in the insurance industry, terms like collision, deductibles, copay, liability, and comprehensive are very, very familiar. We use them multiple times every day in conversations with our clients, and they’ve become a common part of our vocabulary. We also understand, though, that the same cannot be said for our clients! It’s our goal to understand these insurance topics thoroughly so that our clients can focus on other things. 


However, you will feel more confident about your own homeowners and
auto insurance in Greenville, SC if you have a basic knowledge of what these terms mean and how they affect your insurance. Here’s a quick refresher about the most important car insurance terms.


1. Deductible


A car owner quickly realizes how important this term is when they become involved in an accident and their insurance has to pay a claim. Many people assume that if they have insurance, that means they will never have to pay anything out of pocket for an accident. Not necessarily! The deductible is the amount of money that the client has to pay personally before their auto insurance policy will pay the remaining amount. 


If you have a high deductible (meaning you must pay more money out of pocket before your insurance kicks in), your monthly premium is lower. On the other hand, if you want to have zero deductible in the event of a claim, you will pay more for your policy each month. Which is best for you? Your representative at Priority is the best advisor to talk you through the considerations and establish the best balance for your policy.


2. Liability


Specifically within the context of auto insurance in Greenville, SC, liability insurance refers to what your insurance company will pay to cover property damage or injury to others, if you are found to be at fault in an accident. If you are involved in an accident and the other driver is found to be at fault, your liability insurance would not come into play. 


When setting up your insurance policy, liability is usually divided between coverage for property damage and personal injury. You may want to set different parameters for these different categories, with the help of your insurance agent.


3. Collision


Many car owners misunderstand just what collision coverage refers to, and for good reason! It’s easy to get confused about what’s covered and not covered by this specific category. A short answer is that it covers damage to your vehicle when that damage is not covered by any other type of insurance coverage.


The most common application of collision coverage is when you are found at fault in an accident, and your vehicle suffers damage that needs to be repaired. The other driver’s insurance does not cover your damage since you were at fault, and your liability insurance only applies to the other driver’s vehicle and injuries. Therefore, your collision coverage determines how much your insurance company will pay for you to get your car repaired–or replaced, if it is a total loss.


Going without a collision component to your
auto insurance policy means that you assume the responsibility for all repairs to your own vehicle in the event of an accident caused by you. Many people take this risk simply because they want their monthly premiums to be manageable. However, an expert at Priority Insurance may be able to help you find a way to add this important coverage and still keep your payments low.


4. Comprehensive


In general terms, the word “comprehensive” means all-encompassing, or leaving nothing out. Does the same apply when we’re talking about auto insurance in Greenville, SC? Sort of, but only after all other types of applicable coverage have been ruled out.


If liability, either yours or another driver’s, and your collision coverage do not cover damage to your vehicle, the next step is to consider whether or not you have comprehensive coverage. Usually this point is reached when damage to your car was caused by an unavoidable or totally unexpected incident. 


Common examples include weather related damage, like a tree branch falling on your car, a violent hailstorm denting its roof, or even something rare like an earthquake. Comprehensive coverage is also used to cover damage caused by criminal activity, like vandalism. If a car thief steals your vehicle, your comprehensive coverage will also kick in to cover the loss.


It’s easy for a car owner to pass on comprehensive coverage because it feels like the potential incidents that would require it are very rare. However, those incidents also tend to be quite costly, so having no comprehensive coverage can cost the car owner a lot of money in the long run.


 This is sort of a “bonus term” in this list. That’s because it’s not a technical definition in the area of auto insurance, but clients tend to use it a lot. We find that when people talk about wanting full coverage, what they have in mind is having to pay very little or nothing out of pocket if they are involved in an accident. As you can see from the preceding definitions, this involves lots of different types of coverage, and you need to calibrate your coverage amounts in each of those areas to cover your potential costs if an accident occurs. 


It would be impossible to ensure that you would never have to pay out of pocket no matter what happens to your vehicle or someone else’s property. Your ideal insurance policy will always be a balance between your monthly premium and coverage levels. As always, an expert at Priority Insurance is the best person to consult to find out what levels are realistic for you, what your budget is for auto insurance, and how you can get the best deal for the coverage you need.


Are you spending too much for your auto insurance in Greenville, SC? Find out in a conversation with one of our experts. We look forward to giving you our assessment of your insurance and explaining any other terms that you have questions about.


Woman behind a café counter with glass pastry display and coffee equipment
October 13, 2026
Buy-sell agreements, key person insurance, and executive bonus plans for Upstate SC business owners. Protect your family, partners, and key people.
Interior wall with a large vertical crack and crumbled plaster exposing damage near the floor.
October 8, 2026
Most homeowners I sit down with in Greenville can tell me their deductible and roughly what their house is insured for. Very few can tell me whether they're covered if the ground shakes, or if the sewer line backs up into the house. That's not a knock on anybody — these are two coverages almost nobody thinks about until the day they need them. And on that day, a lot of people find out the answer is no.  Both earthquake damage and sewer or water backup are excluded on a standard homeowners policy. Both can usually be added back, often for a modest cost. Here's what I want every homeowner in the Upstate to understand about each one.
By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Night-lit two-story brick house with a balcony and warm exterior lights at night
September 17, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
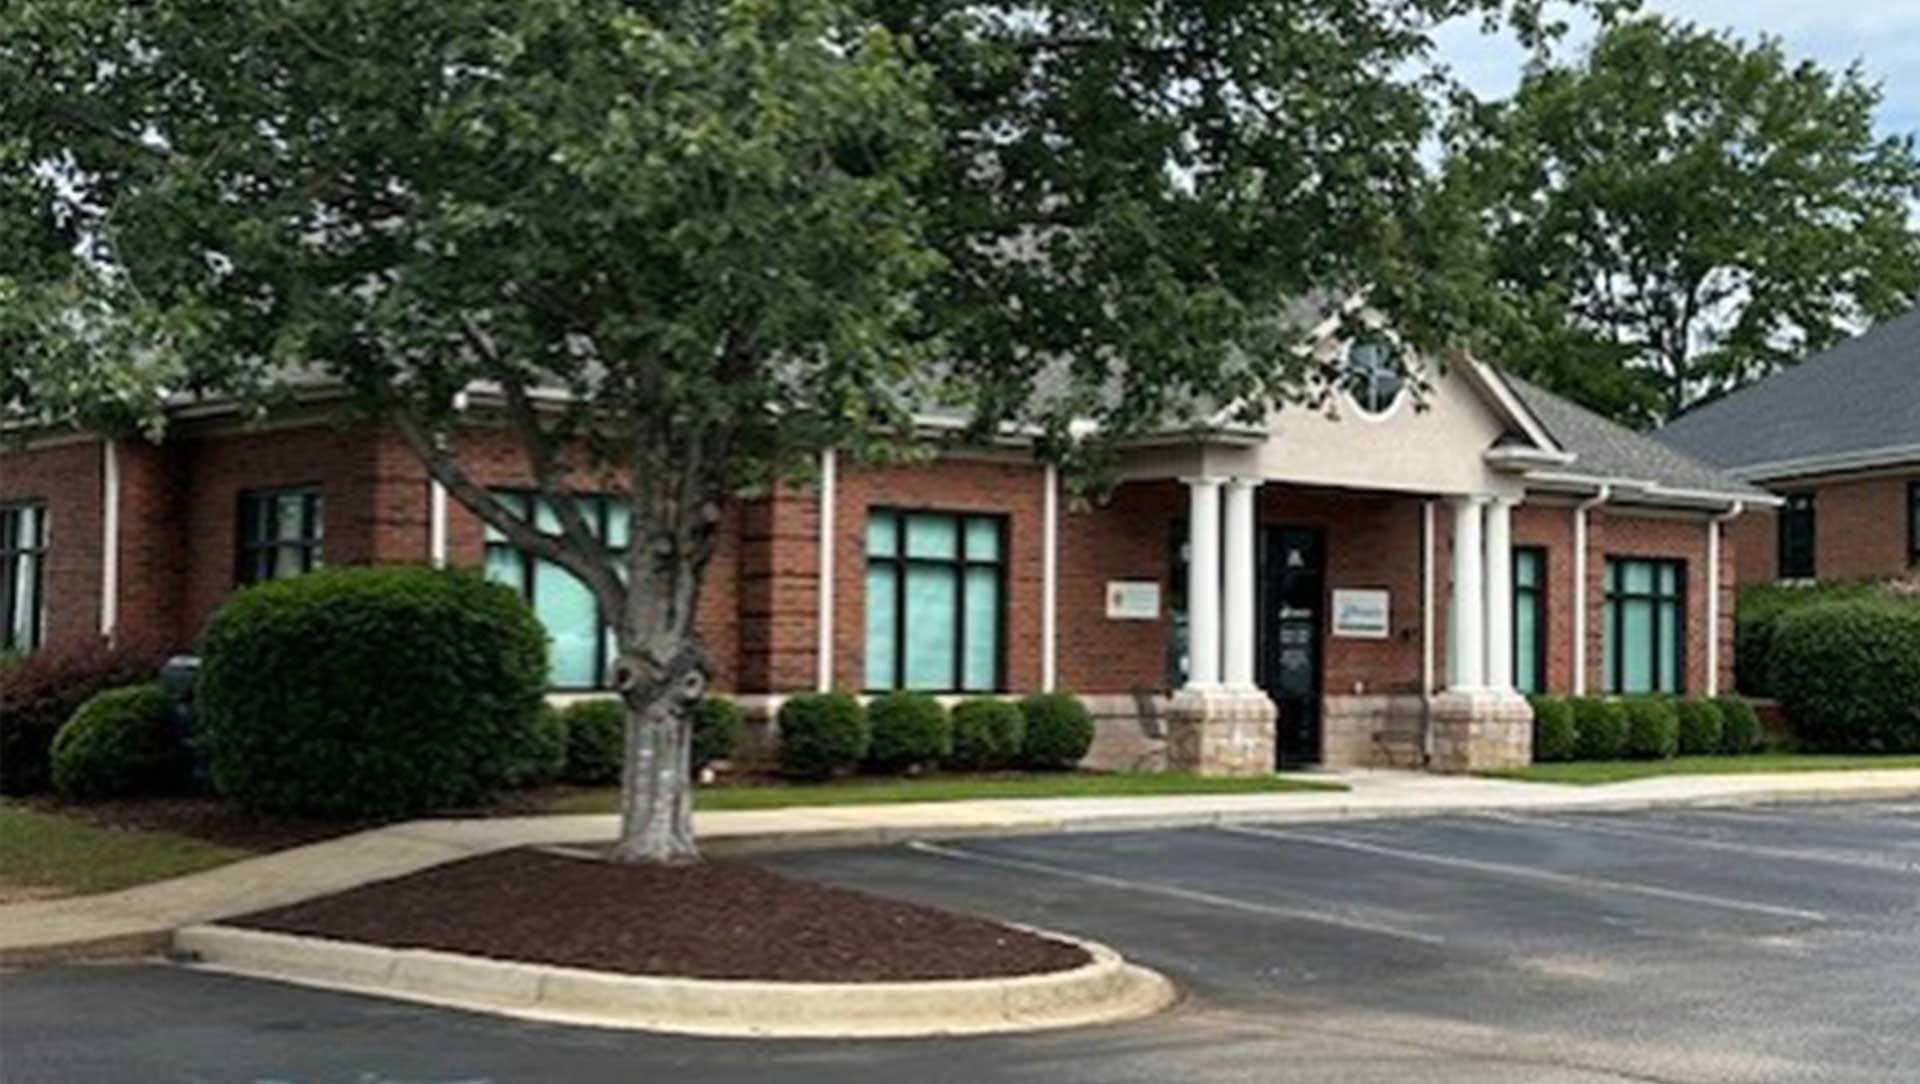
Brick office building with white columns, green awnings, and a tree-lined parking lot
By By Mark Turley, Owner — Priority Insurance LLC • August 11, 2026
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Show More