Auto Liability Insurance in Greenville, South Carolina: Protecting Yourself in Today's Injury-Lawsuit Climate
By Mark Turley, Owner — Priority Insurance LLC • August 4, 2026

Mark Turley, owner of Priority Insurance LLC, outside the agency's Greenville office.

2011

Serving the Upstate Since

Large

Carrier Partner Network

CLU · ChFC

Credentialed Advisor on Staff

SC · NC · GA

Licensed In 3 States

Every morning I pull out of the lot at our office on Milestone Way in Greenville, and I drive the same roads you do — 385, Woodruff Road, Wade Hampton, Pelham. I also drive a vehicle that turns a few heads. I mention that not to brag, but because it points straight at something I talk about with clients every single week: in South Carolina, the driver most exposed in a serious accident is often the one people assume is best protected.


My name is Mark Turley. I own Priority Insurance LLC, an independent agency that has served Greenville and the Upstate since 2011. I want to walk you through auto liability coverage — what it is, what South Carolina actually requires, why the state minimums can quietly leave you exposed, and why anyone with a nice car, a home, or a business needs to think harder about it than most people do.

Liability is the coverage that protects you, not your car

When people shop for auto insurance, they usually fixate on collision and comprehensive — the coverage that repairs their own vehicle. That matters. But it is not the coverage that can reach into your bank account, your home equity, and your future paychecks.


Liability coverage does. It has two parts:

  • Bodily injury liability pays for the medical bills, lost wages, and pain-and-suffering claims of people you injure in an at-fault accident — and it pays for the attorney your insurer hires to defend you.
  • Property damage liability pays for the other party's vehicle and any property you damage, from a fence to a storefront.


If a claim or a jury award climbs higher than your liability limits, the difference does not disappear. It becomes your personal responsibility. That is the whole ballgame, and it is where most drivers are dangerously thin.

What South Carolina actually requires (and why it isn't enough)

South Carolina law requires every driver to carry liability limits of 25/50/25 (S.C. Code § 38-77-140). In plain English, that means $25,000 in bodily injury coverage per person, $50,000 per accident, and $25,000 in property damage per accident. South Carolina also requires uninsured motorist (UM) coverage at those same limits — unlike most states, it is built into every policy and cannot be waived (S.C. Code § 38-77-150).


Those are legal minimums, not safe minimums. Consider how quickly they evaporate. One emergency-room visit, one surgery, one ambulance ride, and a few days of missed work can blow past $25,000 for a single injured person. A modern SUV or truck can cost well over $25,000 to replace, so the property-damage limit is easily exceeded in a multi-vehicle pileup. South Carolina is an at-fault, comparative-negligence state, which means the driver who causes the wreck is the one on the hook for the other side's damages.

The state minimum keeps you legal. It does not keep you protected. Those are two very different things.

This is why, as an agency, we do not treat 25/50/25 as a finish line. For most households, we recommend liability limits of at least 100/300/100 — $100,000 per person, $300,000 per accident, and $100,000 in property damage — and for many clients, a personal umbrella policy on top of that. The difference in premium is usually far smaller than people expect, and the difference in protection is enormous.

The Upstate's injury-lawsuit climate is real

If you have driven I-85 or turned on a television in Greenville lately, you already know this: personal-injury advertising in South Carolina is everywhere. Billboards, radio spots, late-night commercials, sponsored search results. There is nothing wrong with an accident victim hiring a lawyer — but the sheer volume of that advertising has changed the environment every driver operates in.


Nationally, so-called “nuclear verdicts” — jury awards above $10 million — rose sharply in recent years, and auto-accident cases make up roughly a quarter of them. South Carolina courts have handed down seven-figure car-accident verdicts in counties right around us. Attorneys use well-documented courtroom techniques, such as “anchoring” a jury to a very large number, and a broader trend insurers call “social inflation” has pushed the size of settlements and awards steadily upward.


None of that is meant to scare you. It is meant to be honest about the world we insure people in. When the potential cost of an at-fault accident is rising, the protection you carry against it should rise too.

Why a nicer car — or a home, or a business — can make you a target

Here is the part that hits close to home for me personally. When a claim is being evaluated, one of the quiet questions on the other side is always: is this defendant collectable? A driver in an older economy car with few assets is a very different target than a homeowner, a business owner, or someone driving a $70,000 vehicle.


If my wife or I were ever at fault in a serious accident, it is not hard to imagine an attorney looking at the car, the house, and the business and deciding it is worth pursuing every dollar above our policy limits. That is not paranoia — it is exactly how these cases are assessed. The people with the most to lose are frequently the people carrying the thinnest liability coverage relative to their exposure, because they bought a policy years ago and never revisited the limits.

The uncomfortable math: Say you carry the state minimum and cause an accident that results in a $250,000 judgment. Your policy pays its $25,000–$50,000 share. The remaining balance can be pursued against your savings, your home equity, and even your future wages. Adequate liability limits plus an umbrella policy are what stand between a bad day and a financial catastrophe.

How much liability coverage should you carry?

There is no single right answer, but here is the framework I use with clients:

  • Match your coverage to your assets. The more you own, the more a plaintiff's attorney has reason to pursue — and the higher your limits should be.
  • Start at 100/300/100 for most households. It is the practical floor for anyone with a home, savings, or steady income to protect.
  • Add a personal umbrella policy. An umbrella adds $1 million or more of liability protection above your auto and home policies, usually for a modest annual cost.
  • Do not shortchange UM/UIM. Roughly one in eight South Carolina drivers is uninsured, and many more carry only the bare minimum. Raising those limits protects your own family, too.

Serving Greenville and the towns around it

We write auto policies for drivers throughout the Upstate: Greenville, Greer, Simpsonville, Mauldin, Taylors, Fountain Inn, Travelers Rest, Easley, Anderson, Spartanburg, and the surrounding communities. Because we are an independent agency, we shop a large network of top-rated carrier partners to match the right coverage and price to your situation, and we build every auto policy with the UM/UIM protection South Carolina drivers need.

Why work with Priority Insurance

Trust is the whole reason I sat down to write this. Priority Insurance has been an independent, locally owned agency in Greenville since 2011. We are licensed in South Carolina, North Carolina, and Georgia, and our team includes an advisor who holds the CLU (Chartered Life Underwriter) and ChFC (Chartered Financial Consultant) designations from The American College of Financial Services.


We are not a call center in another state. We are your neighbors, and we will look at your specific exposure — your vehicles, your assets, and your risk — and tell you honestly whether your current coverage is doing its job.

Is your liability coverage actually protecting you?

Let's review your limits and close the gaps before you need them.


Mark Turley

Owner · Priority Insurance LLC

Mark Turley is the owner of Priority Insurance LLC, an independent insurance agency serving Greenville and the Upstate of South Carolina since 2011. Priority is licensed in South Carolina, North Carolina, and Georgia and shops a large network of top-rated carriers to match coverage to each client's real-world exposure. Reach the agency at 140 Milestone Way, Suite A, Greenville, SC 29615, or call (864) 297-9744.

Woman behind a café counter with glass pastry display and coffee equipment
October 13, 2026
Buy-sell agreements, key person insurance, and executive bonus plans for Upstate SC business owners. Protect your family, partners, and key people.
Interior wall with a large vertical crack and crumbled plaster exposing damage near the floor.
October 8, 2026
Most homeowners I sit down with in Greenville can tell me their deductible and roughly what their house is insured for. Very few can tell me whether they're covered if the ground shakes, or if the sewer line backs up into the house. That's not a knock on anybody — these are two coverages almost nobody thinks about until the day they need them. And on that day, a lot of people find out the answer is no.  Both earthquake damage and sewer or water backup are excluded on a standard homeowners policy. Both can usually be added back, often for a modest cost. Here's what I want every homeowner in the Upstate to understand about each one.
By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Night-lit two-story brick house with a balcony and warm exterior lights at night
September 17, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
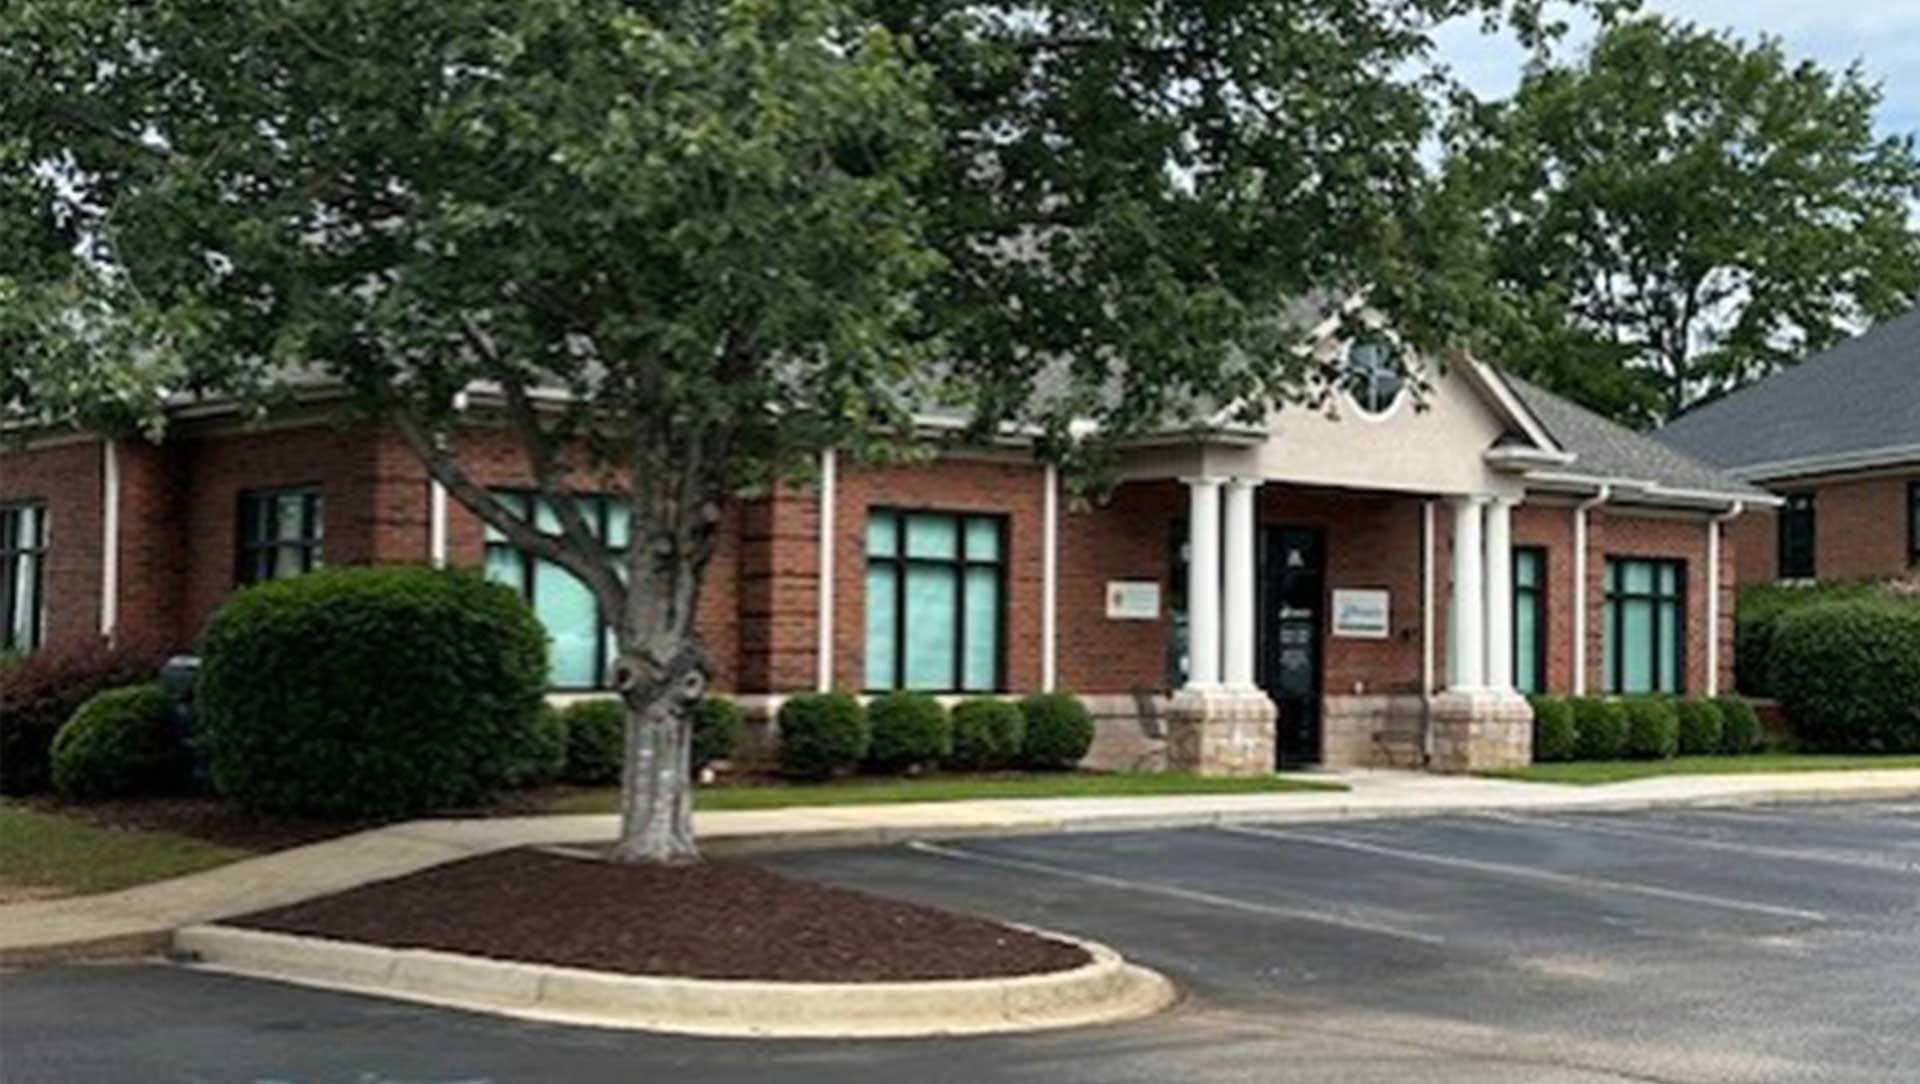
Brick office building with white columns, green awnings, and a tree-lined parking lot
By By Mark Turley, Owner — Priority Insurance LLC • August 11, 2026
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Show More