How Homeowners Insurance in the Upstate Has Changed Greenville, SC & the Upstate
September 17, 2026

Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA

Licensed in South Carolina · North Carolina · Georgia

By Mark Turley, Owner — Priority Insurance LLC

Independent agent serving the Upstate since 2011 · Published September 16, 2026


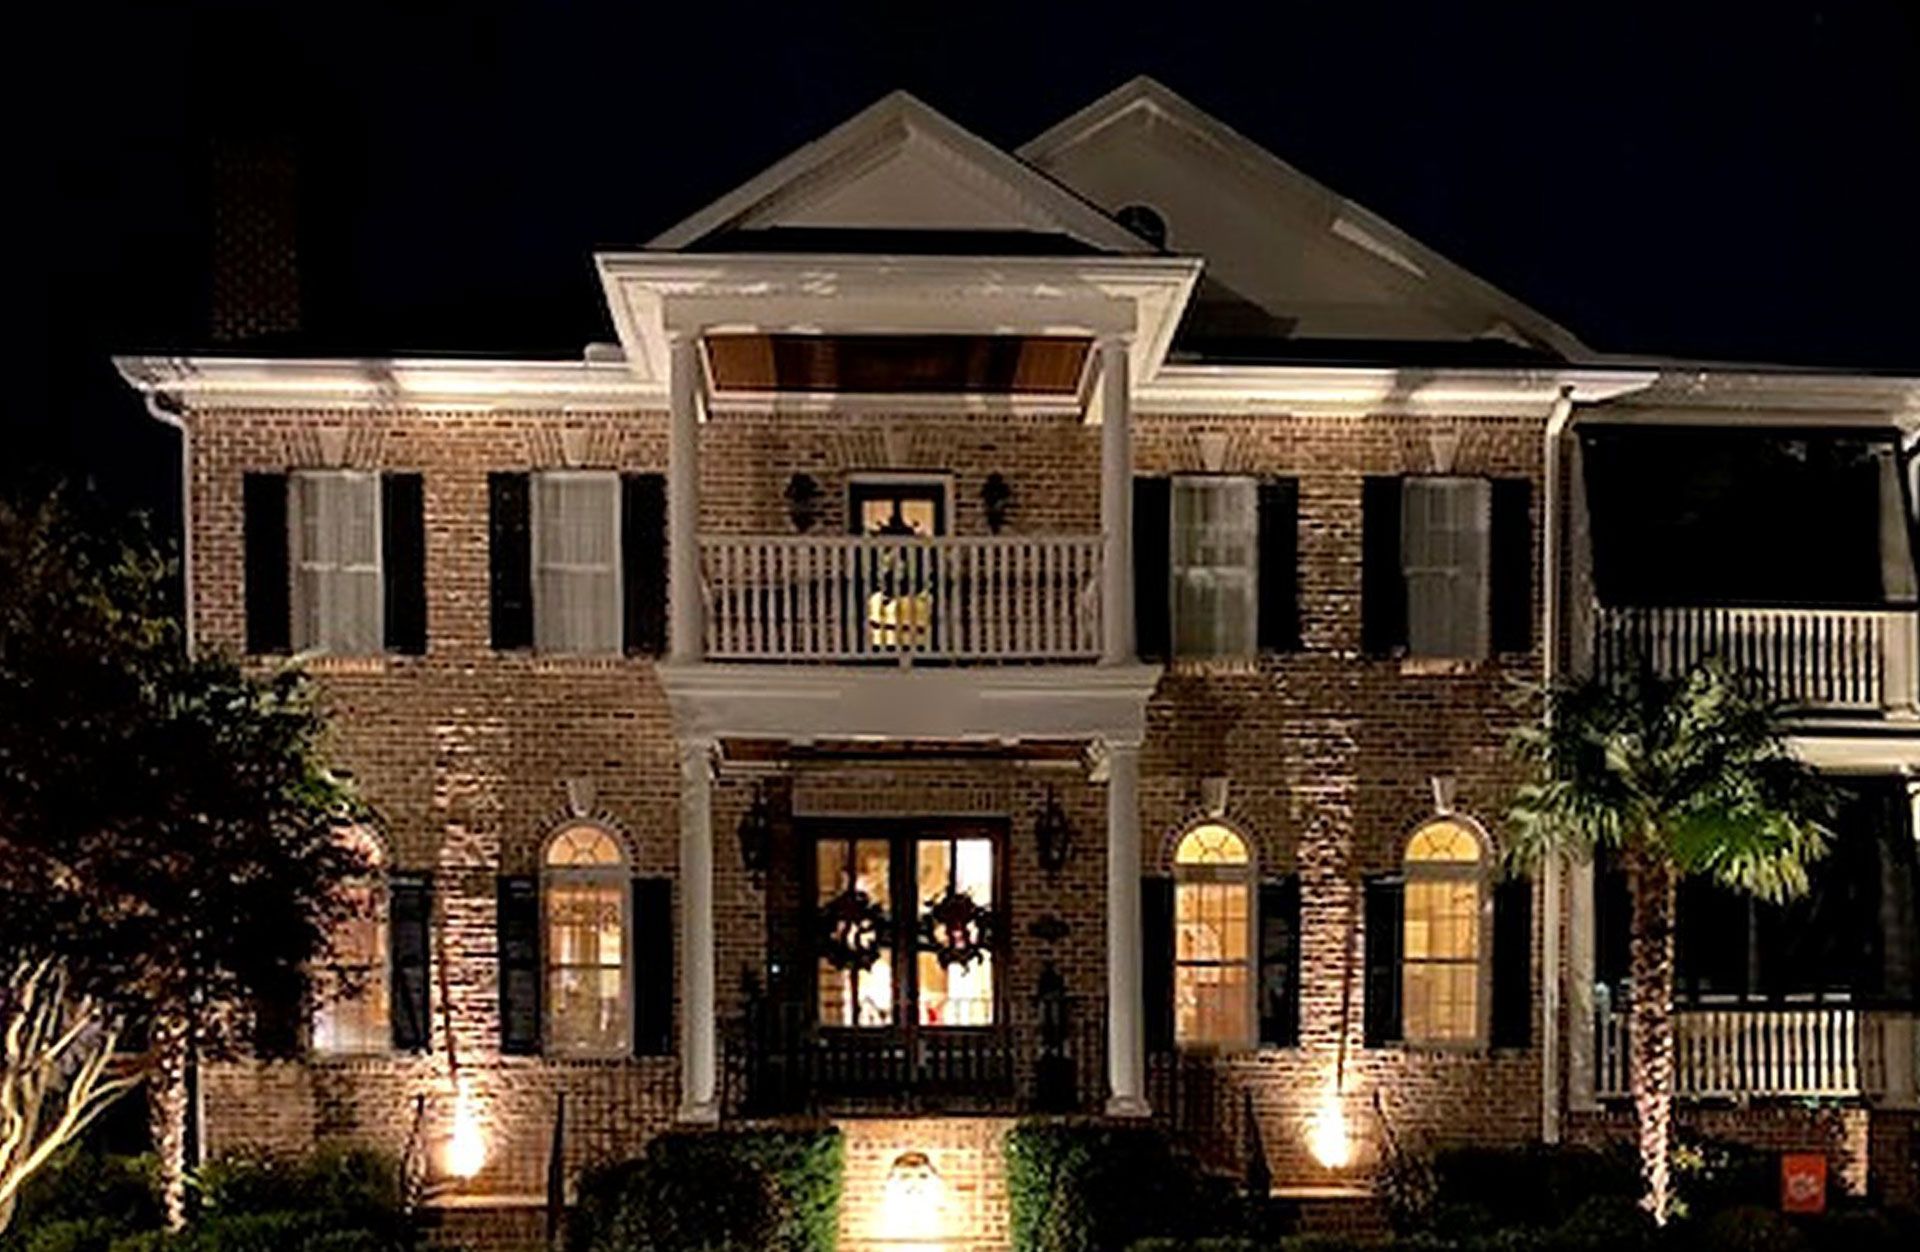
Lit brick two-story house at night, warmly lit with lights on the porch and windows.

A well-kept Upstate home. Today, a home's roof, systems, and upkeep are central to whether — and at what price — it can be insured.

Every week lately, a version of the same conversation happens in my office here in Greenville. A homeowner opens a renewal letter, sees a number that's hundreds of dollars higher than last year, and calls to ask what on earth happened. Or someone buying a home in Greer or Simpsonville gets a surprise: before the carrier will even quote the house, it wants to know the age of the roof, what kind of electrical panel is in the garage, and whether the plumbing has ever been updated. If you own a home in the Upstate, the property insurance world you're dealing with in 2026 is not the one you dealt with five years ago. Let me walk you through what actually changed, why it changed, and what it means for your wallet — in plain English, the way I'd explain it across my desk.

First, a quick translation: "property" and "hazard" insurance

If your mortgage company sends a letter about "hazard insurance," or your closing paperwork lists "property insurance," those are just other names for the coverage on the physical structure of your home — the dwelling portion of a standard homeowners policy. Same thing most folks mean when they say "homeowners." I'll use those terms interchangeably here, because the changes I'm describing hit all of it.

The days of easy homeowners coverage are over

Here's the heart of it. For years, carriers wrote the vast majority of homes off the address and a handful of basic questions. Square footage, year built, a credit-based score, maybe a prior-claims check, and you were bound. Those days are gone. Carriers now underwrite the home itself — the condition of the roof, the age of the systems, and how well the place has been maintained. It isn't that they got picky for no reason. It's that they lost an enormous amount of money, and they've changed the rules to stop the bleeding.

Why it changed: the losses were massive

Three things stacked up at once.


Helene proved "inland and safe" is a myth. On September 27, 2024, Hurricane Helene came up through Georgia and drove tropical-storm and hurricane-force winds deep into the Upstate. This wasn't a coastal event. FEMA opened individual disaster assistance for Greenville, Spartanburg, Anderson, Pickens, Oconee, and Cherokee counties, among others. Helene was tied to roughly 50 deaths in South Carolina — more than Hurricane Hugo — and public damage and response costs in the Upstate alone topped $370 million, before you even count insured or private losses. Regionally it became one of the costliest insured disasters in U.S. history. For an industry that had long treated the Upstate as low-risk interior, that was a wake-up call.


Hail and spring storms grind away every year. Even in a calm hurricane year, the Upstate gets pounded by severe thunderstorms and hail every spring. Those "severe convective storms" are a national problem — insured losses ran roughly $60 billion in 2023 and tens of billions again in 2024 — and hail is brutal on aging shingle roofs, which brings me to the roof section below.


Reinsurance got expensive. Insurance companies buy insurance on themselves, called reinsurance, so one bad storm doesn't sink them. The cost of that reinsurance climbed sharply over the past few years, and Carolina carriers — who juggle both coastal hurricane risk and Upstate hail — pay more for it. That cost flows straight into your premium.


What does that add up to? At the end of 2024, the homeowners combined ratio in South Carolina ran near 144% — meaning for every $1 of premium collected, carriers paid out about $1.44. Average annual premiums in the state reached roughly $2,700, well above the national average, and jumped about 20% from 2024 to 2025. Several national carriers paused or reduced new-business writing in parts of the state, which means less competition and more upward pressure on price for everyone. None of that is about you as an individual homeowner — it shows up on nearly every renewal in the Upstate.

Insurers now inspect the home, not just the address

The most visible change is the return of the 4-point inspection. It's a limited look at the four systems most likely to cause a costly claim: roof, electrical, plumbing, and HVAC. It used to be mostly a Florida thing. Now it's common across the Carolinas, typically on homes around 20 to 30 years old, and carriers ask for it at new business, when you switch companies, and sometimes at renewal. If you're buying an older home in Taylors or Easley, expect one. The inspection isn't pass/fail exactly — it's a disclosure document — but the findings decide whether a carrier will write the house, at what price, and with what conditions attached.

The roof is the single biggest change

If there's one thing driving both price and eligibility, it's the roof.

  • Age thresholds. A growing number of carriers won't write a shingle roof much past 20 years, and some have tightened that to 15. A roof with only a few years of useful life left often has to be replaced before a policy will bind.
  • The shift from Replacement Cost to Actual Cash Value. This one costs people real money and most never see it coming. Traditionally, a covered roof claim paid replacement cost (RCV) — the full cost to put on a new roof, minus your deductible. Increasingly, older roofs are settled at actual cash value (ACV) or on a "roof payment schedule," where the payout is reduced for the roof's age and depreciation. A common industry pattern: roughly full replacement cost for roofs 0–10 years old, a prorated amount from about 10–15 years, and ACV once a roof is around 15–16 years or older. On a hail-damaged 18-year-old roof, that difference can be many thousands of dollars out of your pocket.
  • Separate wind/hail deductibles. Many policies now carry a separate, higher deductible that applies only to wind or hail damage — sometimes a flat $2,500 to $5,000, sometimes a percentage of your dwelling limit. A 1% wind/hail deductible on a $300,000 home is $3,000 before the carrier pays a dime.


Here's the honest tradeoff: ACV roof settlements and higher wind/hail deductibles lower your premium, but they shift risk back onto you when a claim hits. Neither is automatically good or bad — you just need to know which one is on your policy so a storm isn't the moment you find out.

Older homes: the red flags carriers look for

A lot of the Upstate's charm is in its older homes, but a few things inside them are now underwriting red flags. If your home has any of these, expect questions, a surcharge, an exclusion, a repair requirement — or in some cases a decline:

  • Electrical panels: Federal Pacific (Stab-Lok), Zinsco, and Challenger panels are widely flagged as fire hazards. So is aluminum branch wiring and old knob-and-tube. Replacing an outdated panel typically runs $1,500–$3,000 and is often the single best move to make an older home insurable.
  • Plumbing: polybutylene and galvanized supply pipes are red flags, and the age of your water heater matters — a burst supply line or failed water heater is one of the most common non-weather claims there is.
  • Roof and HVAC age, as covered above, round out the four points.

Maintenance is now underwriting

This is the shift I most want Upstate homeowners to hear: deferred maintenance is what gets homes declined and non-renewed today. Missing or curling shingles, moss and organic growth on the roof, worn flashing, a rusting water heater, an obsolete panel — these used to be "get to it eventually" items. Now they're the exact things an inspection photo captures and an underwriter acts on. Keeping your home up is no longer just good homeownership; it's part of keeping it insurable at a reasonable price.

What South Carolina law does — and doesn't — let insurers do

With all that tightening, it's fair to ask: can a carrier just drop me whenever it wants? No — and this is where state law matters.


Under S.C. Code § 38-75-730, an insurer generally may not cancel your policy in the middle of its term. It can only cancel before the term ends for specific reasons: nonpayment of premium, material misrepresentation on your application, a substantial change in the risk, or a substantial breach of your contractual duties. Even then, it must give you at least 30 days' written notice (10 days for nonpayment), and the notice has to state the precise reason.


Renewal is where the guidelines really bite. A carrier can decline to renew a policy at its expiration — but under S.C. Code § 38-75-1160, it must send written notice with a specific reason, generally at least 60 days ahead for a non-renewal effective between November 1 and May 31, and at least 90 days ahead for one effective between June 1 and October 31. That notice must also tell you about your right to ask the South Carolina Department of Insurance to review the decision, in writing, within 30 days.


The honest bottom line: the law protects you from arbitrary mid-term drops and from surprise non-renewals with no warning — but it does not require a carrier to keep insuring a home that no longer meets its guidelines. That's precisely why getting ahead of these issues, rather than waiting for a renewal letter, is worth your time.

What this means for you as an Upstate homeowner

You don't need to panic — you need to get in front of it. A few practical steps:

  • Know your roof's age and condition. If it's approaching 15–20 years, start planning and budgeting now, before a carrier forces the timeline.
  • Know your panel and wiring. If you've got a Federal Pacific or Zinsco panel, replacing it is usually money well spent — for safety and for insurability.
  • Know your plumbing and water-heater age. Polybutylene or galvanized supply lines and an aging water heater are worth addressing on your schedule, not an underwriter's.
  • Document your upkeep. Keep photos and receipts for a new roof, panel, water heater, or repipe. That paper trail helps at quoting time and again if you ever file a claim.
  • Work with an independent agent who shops a large network. When one carrier tightens up or steps back from the Upstate, another may still be a strong fit for your home. Matching your specific house to the right carrier is the whole point of being independent — and it's what my office does every day for families in Greenville, Greer, Simpsonville, Mauldin, Taylors, Easley, Anderson, and Spartanburg.


The market has changed, and it isn't changing back. But a well-kept home, priced with the right carrier, is still very much insurable — and that's a conversation I'm glad to have with you before your renewal has it for you.

Mark Turley is the owner of Priority Insurance LLC, an independent insurance agency in Greenville, SC serving the Upstate since 2011. Priority shops a large network of top-rated carriers across South Carolina, North Carolina, and Georgia, and has a CLU · ChFC–credentialed advisor on staff for life and financial planning. Office: 140 Milestone Way, Suite A, Greenville, SC 29615. Phone: (864) 297-9744.

This article is general educational information for South Carolina homeowners and is not personalized insurance, legal, financial, or tax advice. It is not a statement of any specific carrier's underwriting rules and not a promise or offer of coverage. Underwriting guidelines, roof settlement terms, deductibles, and policy language vary by carrier and by policy; statutory references are current as of publication and may change. Review your own policy and speak with a licensed agent about your specific home.

Let's look at your home before your renewal does

A few minutes now can save you a surprise at renewal. We'll shop your home across our carrier network and match it to the right fit.


Related coverage from Priority Insurance


Home Insurance | Flood Insurance | Auto Insurance | Personal Umbrella Insurance

Woman behind a café counter with glass pastry display and coffee equipment
October 13, 2026
Buy-sell agreements, key person insurance, and executive bonus plans for Upstate SC business owners. Protect your family, partners, and key people.
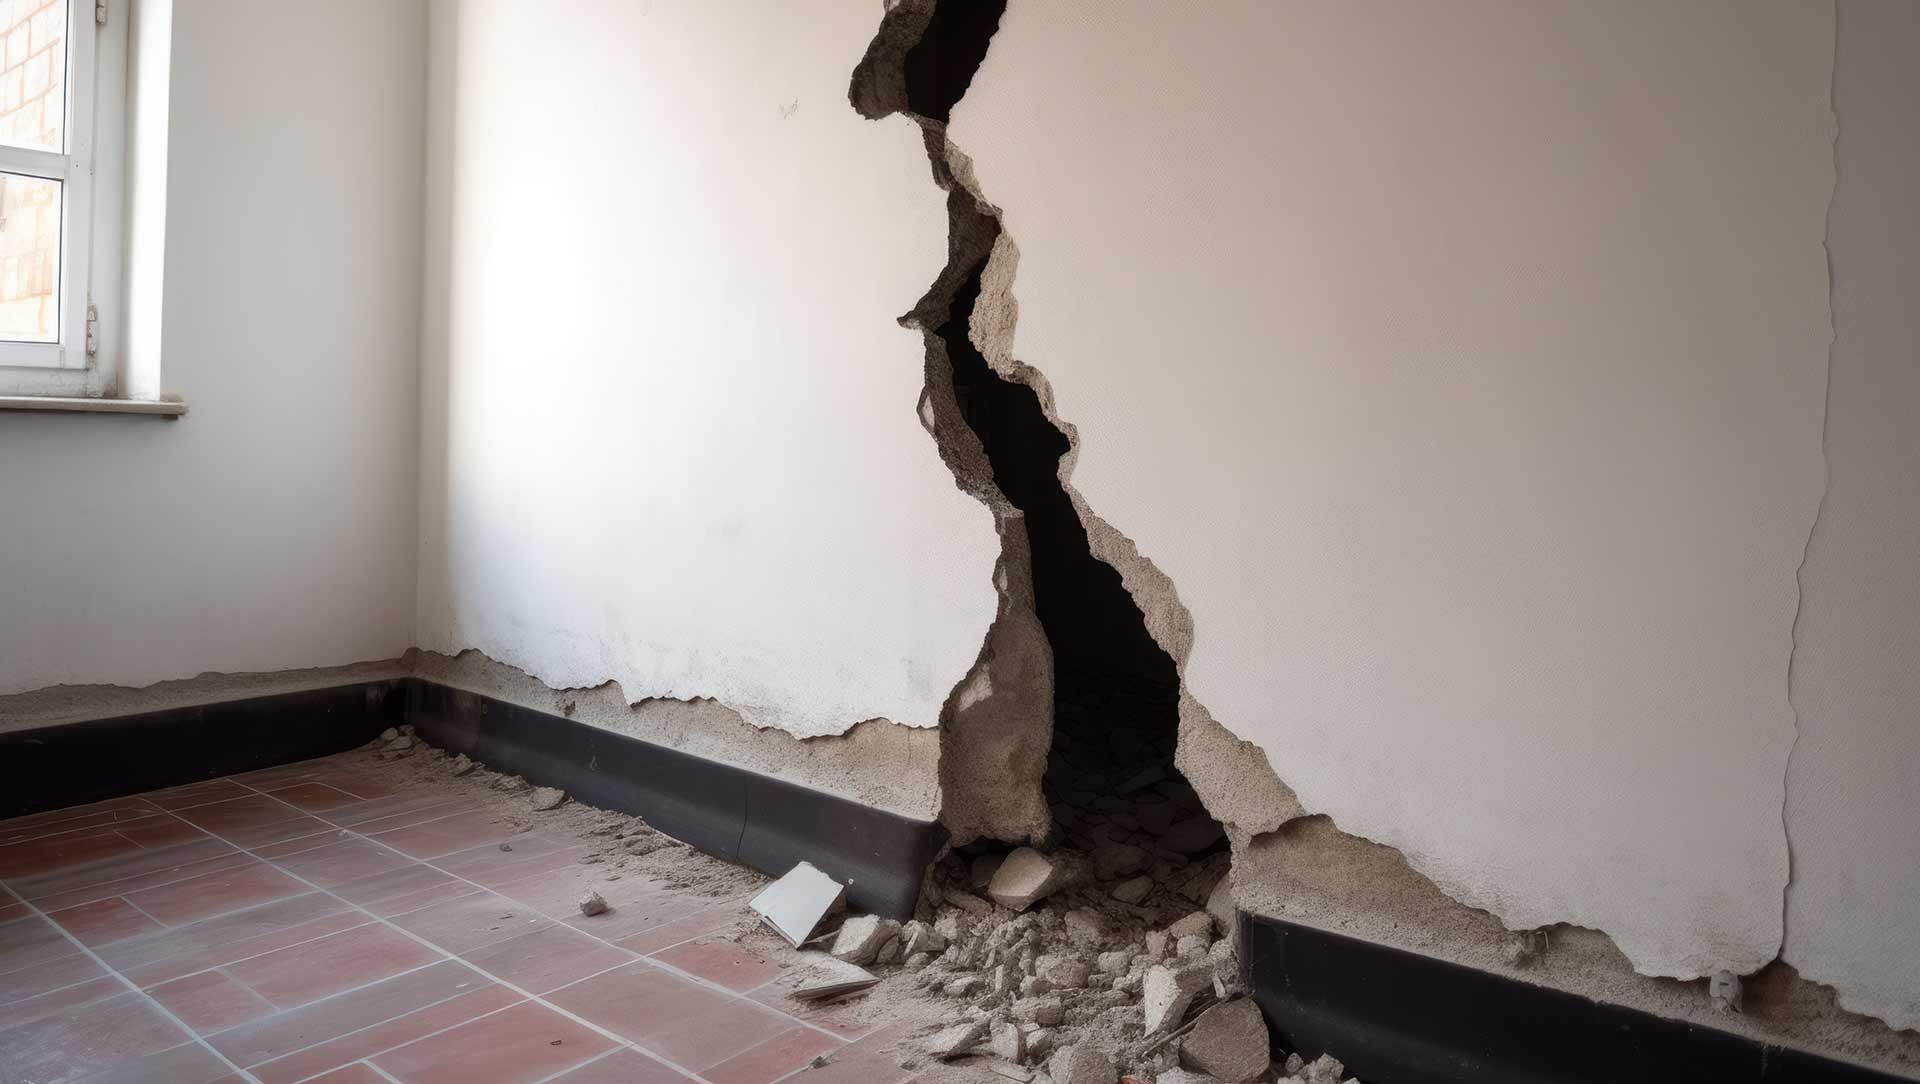
Interior wall with a large vertical crack and crumbled plaster exposing damage near the floor.
October 8, 2026
Most homeowners I sit down with in Greenville can tell me their deductible and roughly what their house is insured for. Very few can tell me whether they're covered if the ground shakes, or if the sewer line backs up into the house. That's not a knock on anybody — these are two coverages almost nobody thinks about until the day they need them. And on that day, a lot of people find out the answer is no.  Both earthquake damage and sewer or water backup are excluded on a standard homeowners policy. Both can usually be added back, often for a modest cost. Here's what I want every homeowner in the Upstate to understand about each one.
By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
Brick office building with white columns, green awnings, and a tree-lined parking lot
By By Mark Turley, Owner — Priority Insurance LLC • August 11, 2026
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Dark blue luxury SUV parked outside a building on a patterned driveway
By By Mark Turley, Owner — Priority Insurance LLC • August 4, 2026
Mark Turley, owner of Priority Insurance LLC, outside the agency's Greenville office.
Show More