
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into. So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
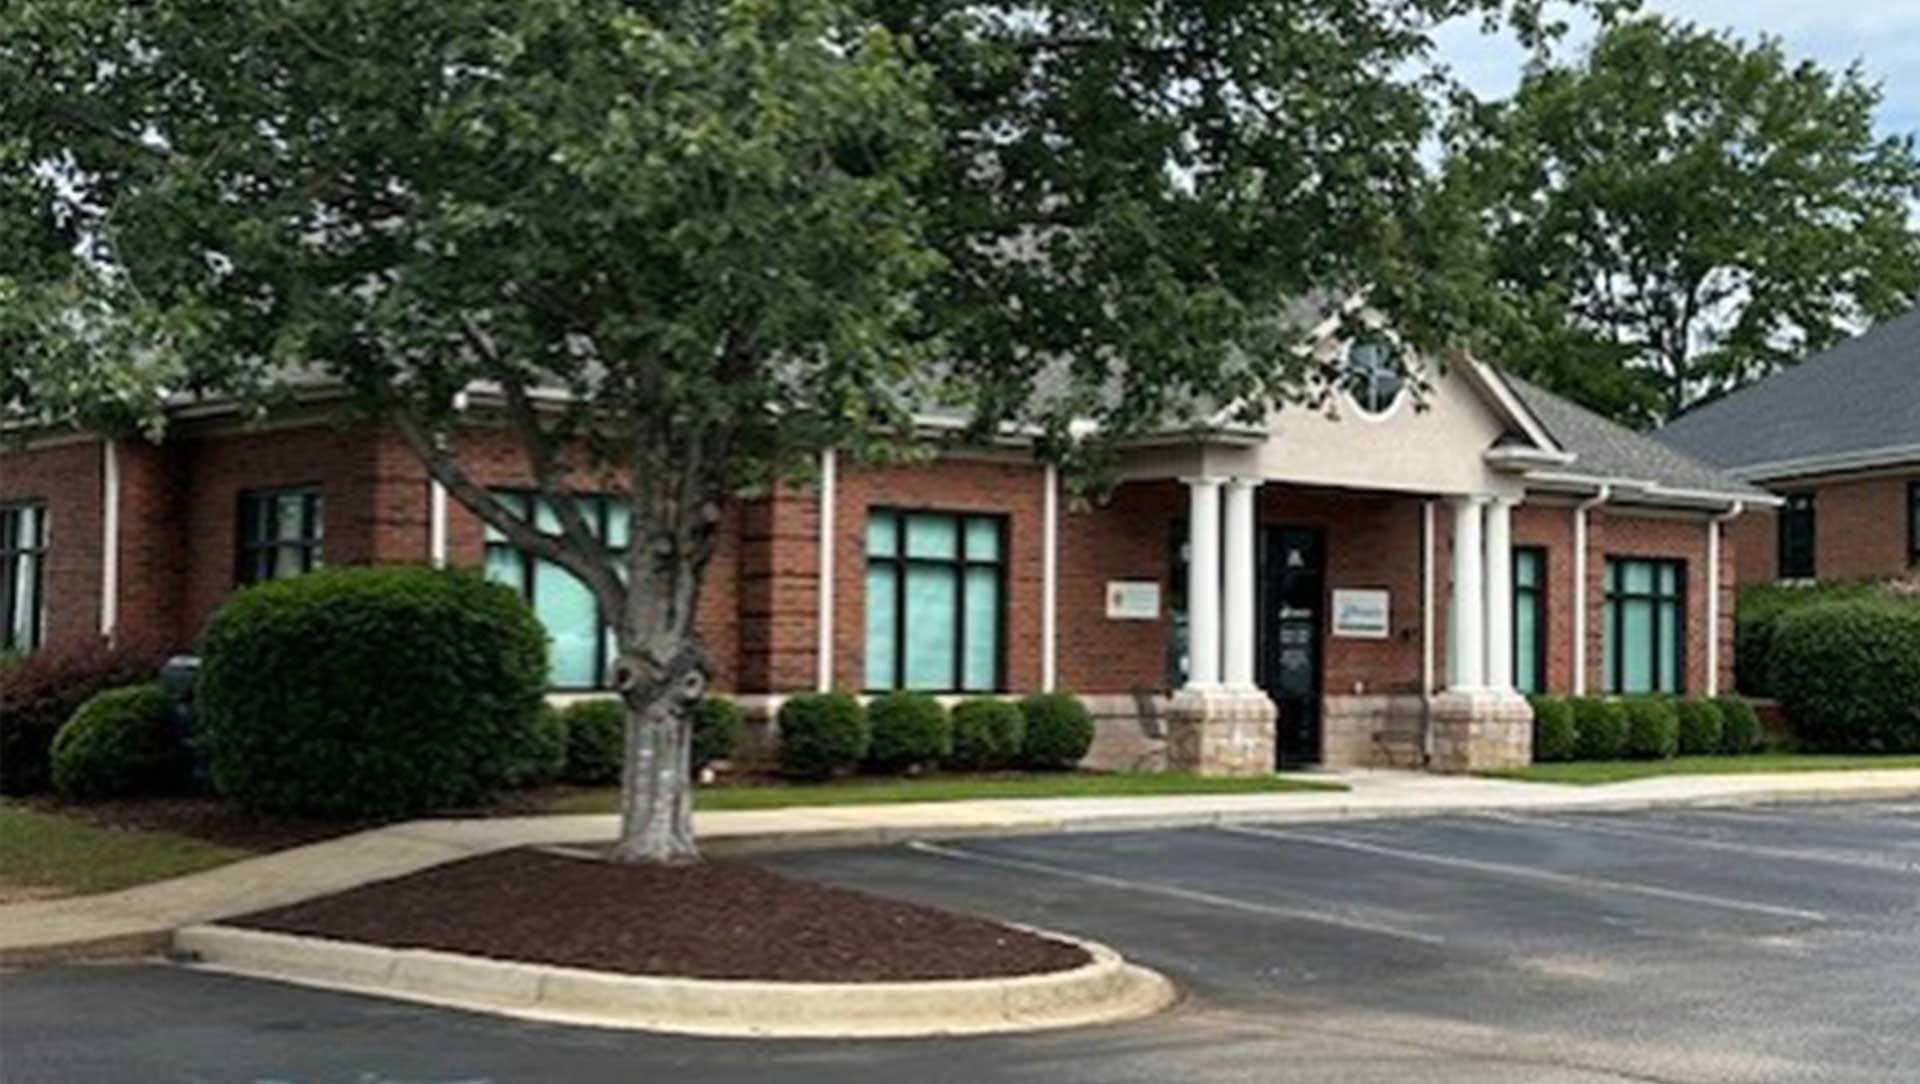
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Mark Turley, owner of Priority Insurance LLC, outside the agency's Greenville office.
As insurance agents, it’s our job at Priority Insurance to think about the worst case scenario. Most of the businesses that partner with us for their commercial insurance needs enjoy long stretches of “business as usual,” without much in the way of emergencies, injuries, or other events that would trigger an insurance claim. However, when that rare event does occur, the specific parameters of their business insurance could make the difference between recovering and going bankrupt. Umbrella liability insurance for business owners is a powerful product that provides peace of mind about those unexpected events. To let you know just how valuable this insurance is, here are a few examples of “worst case scenarios” that are more common than you might think. Each example is an event that would not be covered under more traditional types of commercial insurance, so a business owner without an umbrella insurance policy could end up facing thousands of dollars in costs out of pocket. Non-Employee Injury Most business owners are familiar with how workers compensation insurance works, and even with a small business employing only a few people, it’s likely to be in place to protect the owner if an employee is hurt while on the job. But what if someone who doesn’t work at your company is injured on the property? Even if your business is not a public-facing company like a grocery store or restaurant, you most likely have members of the public at your location occasionally. Service providers such as custodial and delivery workers are in and out on a regular basis, and the area outside your building comes into play as well. If one of these people happens to slip and fall while working in your building, or if a passerby is injured by a falling tree limb on your property, things can get complicated very quickly. Avoiding a prolonged legal proceeding is in the business owner’s best interest, and umbrella liability insurance for the business can ensure that the organization can continue to focus on growth, rather than getting sidetracked and having resources drained by a lawsuit. Intellectual Property Lawsuit Copyright infringement is most familiar to the public in the field of entertainment. Occasionally one pop music star will sue another for releasing a song that is suspiciously similar to one of their own. But this situation is not limited to the arts. Small businesses sometimes attract the attention of other organizations when they unwittingly publicize a new logo, slogan, or company name that closely resembles that of the larger company. In order to control their own reputation, these organizations will go after even small businesses to force them to change their intellectual property. In the worst case scenario, they may seek restitution for damages that they perceive. Even if the infringement was unintentional, unraveling the problem could cost a lot of money, which a larger organization may be able to spare but the small business cannot. This type of situation can be avoided with an umbrella liability insurance policy, and your agent at Priority Insurance can help you make sure you’re covered if an event like this ever comes up in connection with your business’s intellectual property. Unexpected Employee Actions Human beings are unpredictable, and that unpredictability can lead to any number of worst case scenarios for a small business. Even though you may have thoroughly vetted each employee on your company’s payroll, there’s no guarantee that those employees won’t someday do something that reflects back negatively on your organization. It could be something as simple as an innocent traffic accident while the employee is driving a company owned car. If another driver is injured in the accident, or if there is damage to a property where the employee is making a delivery, your company could be held liable for the expenses. Depending on the circumstances, the costs may or may not be covered by your company’s commercial auto policy. An umbrella liability insurance policy includes situations that are excluded by your auto policy to make sure that you don’t get stuck paying for damage out of pocket. Unfortunately, much larger issues can arise if an employee unexpectedly commits intentional damage while on your payroll. This is a true worst case scenario, and we all hope that the people we work with every day have one another’s best interests in mind. But it is not unheard of for an employee to suddenly act in a hostile, irrational manner and cause damage or injury to others. As catastrophic as the effects of such an action are to the people involved, they can also be catastrophic for the business that employs the individual. Although we hope none of our clients ever have to face this type of event, we help them make sure they are protected against it with umbrella liability insurance for business owners. Other Threats To a Business It would be impossible, of course, to list all the worst case scenarios that could crop up in the life of a business. That’s exactly why umbrella liability insurance was developed in the first place: to give business owners peace of mind as they begin investing in their organization. Without worrying about the possibility of a once-in-a-century weather event, an unpredictable action by someone, or an unintentional infringement on a powerful company’s intellectual property, a business owner is free to focus on advancing the company’s interests. How confident are you that your organization is ready to withstand whatever comes your way? You can increase that level of confidence by reviewing your business insurance policies with an expert at Priority Insurance. We’ll take a look at all aspects of your business and give you our best advice about what kind of insurance you should hold, what coverages you should have, and what you can do to avoid these and other worst case scenarios in the life of your business. In the Upstate region of South Carolina, contact Priority Insurance today to set up a consultation with a business insurance professional.
For those of us who work in the insurance industry, terms like collision, deductibles, copay, liability, and comprehensive are very, very familiar. We use them multiple times every day in conversations with our clients, and they’ve become a common part of our vocabulary. We also understand, though, that the same cannot be said for our clients! It’s our goal to understand these insurance topics thoroughly so that our clients can focus on other things. However, you will feel more confident about your own homeowners and auto insurance in Greenville, SC if you have a basic knowledge of what these terms mean and how they affect your insurance. Here’s a quick refresher about the most important car insurance terms. 1. Deductible A car owner quickly realizes how important this term is when they become involved in an accident and their insurance has to pay a claim. Many people assume that if they have insurance, that means they will never have to pay anything out of pocket for an accident. Not necessarily! The deductible is the amount of money that the client has to pay personally before their auto insurance policy will pay the remaining amount. If you have a high deductible (meaning you must pay more money out of pocket before your insurance kicks in), your monthly premium is lower. On the other hand, if you want to have zero deductible in the event of a claim, you will pay more for your policy each month. Which is best for you? Your representative at Priority is the best advisor to talk you through the considerations and establish the best balance for your policy. 2. Liability Specifically within the context of auto insurance in Greenville, SC, liability insurance refers to what your insurance company will pay to cover property damage or injury to others, if you are found to be at fault in an accident. If you are involved in an accident and the other driver is found to be at fault, your liability insurance would not come into play. When setting up your insurance policy, liability is usually divided between coverage for property damage and personal injury. You may want to set different parameters for these different categories, with the help of your insurance agent. 3. Collision Many car owners misunderstand just what collision coverage refers to, and for good reason! It’s easy to get confused about what’s covered and not covered by this specific category. A short answer is that it covers damage to your vehicle when that damage is not covered by any other type of insurance coverage. The most common application of collision coverage is when you are found at fault in an accident, and your vehicle suffers damage that needs to be repaired. The other driver’s insurance does not cover your damage since you were at fault, and your liability insurance only applies to the other driver’s vehicle and injuries. Therefore, your collision coverage determines how much your insurance company will pay for you to get your car repaired–or replaced, if it is a total loss. Going without a collision component to your auto insurance policy means that you assume the responsibility for all repairs to your own vehicle in the event of an accident caused by you. Many people take this risk simply because they want their monthly premiums to be manageable. However, an expert at Priority Insurance may be able to help you find a way to add this important coverage and still keep your payments low. 4. Comprehensive In general terms, the word “comprehensive” means all-encompassing, or leaving nothing out. Does the same apply when we’re talking about auto insurance in Greenville, SC? Sort of, but only after all other types of applicable coverage have been ruled out. If liability, either yours or another driver’s, and your collision coverage do not cover damage to your vehicle, the next step is to consider whether or not you have comprehensive coverage. Usually this point is reached when damage to your car was caused by an unavoidable or totally unexpected incident. Common examples include weather related damage, like a tree branch falling on your car, a violent hailstorm denting its roof, or even something rare like an earthquake. Comprehensive coverage is also used to cover damage caused by criminal activity, like vandalism. If a car thief steals your vehicle, your comprehensive coverage will also kick in to cover the loss. It’s easy for a car owner to pass on comprehensive coverage because it feels like the potential incidents that would require it are very rare. However, those incidents also tend to be quite costly, so having no comprehensive coverage can cost the car owner a lot of money in the long run. This is sort of a “bonus term” in this list. That’s because it’s not a technical definition in the area of auto insurance, but clients tend to use it a lot. We find that when people talk about wanting full coverage, what they have in mind is having to pay very little or nothing out of pocket if they are involved in an accident. As you can see from the preceding definitions, this involves lots of different types of coverage, and you need to calibrate your coverage amounts in each of those areas to cover your potential costs if an accident occurs. It would be impossible to ensure that you would never have to pay out of pocket no matter what happens to your vehicle or someone else’s property. Your ideal insurance policy will always be a balance between your monthly premium and coverage levels. As always, an expert at Priority Insurance is the best person to consult to find out what levels are realistic for you, what your budget is for auto insurance, and how you can get the best deal for the coverage you need. Are you spending too much for your auto insurance in Greenville, SC? Find out in a conversation with one of our experts. We look forward to giving you our assessment of your insurance and explaining any other terms that you have questions about.
Buying your first house is an incredibly exciting step. Finalizing the paperwork, changing your address, and finally taking possession of the keys to your new place make you feel like you’ve crossed a huge threshold from renter to homeowner. Homeowners insurance is one of the topics related to your purchase, however, that’s not quite as exciting to consider. For most buyers, buying insurance is little more than a necessary task, one of the many documents that has to be scanned, dated, and signed. After the dust has finally cleared, the boxes have been unpacked (most of them, anyway!), and you’ve spent a few nights in your brand new home, you’re likely to forget all about your insurance until it’s time to renew your policy, or until an emergency of some kind requires you to make a claim. What’s Not Covered? Some homeowners come up against an unwelcome fact when they talk to their insurance agent about filing a claim for damage. That fact is that some major categories of damage are not covered under standard homeowners insurance sc . Those potentialities must be addressed separately through specialized policies or umbrella policies, or you as the homeowner could be left footing the bill for repairs out of pocket. Here are the top five things that you should know about that probably aren’t covered by your standard insurance policy. 1. Business Related Losses If you operate a small business out of your home, things get very complicated. For example, if you have a commercial kitchen license and use your kitchen at home to cater special events, an emergency like a stove fire or flooding water fixtures could occur. This damage may not be covered by your homeowners insurance in SC, depending on exactly how your policy is set up. As you set up your small business, make sure you have the guidance of a knowledgeable insurance expert to help you establish both homeowners and commercial insurance and protect you from business related losses in your home. 2. Limits On High Value Items A homeowners insurance typically covers all of the items in your home, but it might not cover the full value of all of those items. For high value possessions, your insurance policy probably has an upper limit on how much you can claim in the case of theft or an accident. This most commonly applies to jewelry, but items like artwork, musical instruments, and collectible items are also important to consider. You can make specific updates to your policy to ensure that the full value of your possessions are covered. 3. Mold Damage Few types of damage are as costly to a homeowner as mold and mildew infestations. It takes intensive measures to remove mold completely, clean the area and replace carpet, flooring, and other materials, and resolve the issue that allowed the infestation to occur in the first place. A mold infestation may be covered by a standard homeowners insurance policy if it is the direct result of an incident included in the policy, but if it is simply a result of years of humid, warm conditions in a basement, attic, or garage, it most likely is not covered. 4. Damage From Neglect/Lack of Maintenance You’re probably already familiar with the fact that your auto insurance policy does not cover the replacement of worn tires and brakes. Maintenance issues are typically excluded from insurance policies, and the same goes for standard homeowners insurance in SC. Your insurance provider assumes that you will conduct regular maintenance on the roofing, plumbing, electrical, HVAC, and other systems of your home. Simply neglecting these parts of your home’s infrastructure for years doesn’t mean that you can make an insurance claim when they finally fail! 5. Flood and Other Water Damage This is a huge area of confusion for homeowners. Flooding from natural waterways is not a major concern in normal circumstances for most homeowners, except for those living near a lake or river. However, other types of water damage are often assumed to be covered by homeowners. Flooding from rain. If a once-in-a-century rainstorm floods your backyard and brings water into your basement, that water damage is most likely not covered under a standard policy. Sewer/drain backups. This may feel like an unforeseen and unpreventable emergency to you as the homeowner, but your insurance provider will most likely categorize it as a maintenance issue, and you will need to pay for cleanup and repair on your own. Water leaking through foundation cracks. If your foundation or basement walls are cracking, groundwater could leak through the cracks slowly over time, leading to water damage, mold, mildew, and other issues. The Solution: Expert Insurance Advice From Priority Insurance If you’re thinking you need to take a closer look at your homeowners insurance policy, that’s a very good idea! It’s easy to set your mind at ease and make sure that you are ready to withstand whatever emergencies the world throws at your home. Just make an appointment to consult with one of the insurance experts at Priority Insurance and we’ll go over your policy with you, explain what’s covered and what’s not covered, and help you fill in any gaps that you’re concerned about. Of course, we’ll also do the research and let you know if you can get a better deal on homeowners insurance through the many options that are available in our agency. There may be opportunities out there for you to save money and get better coverage, but no one’s going to knock on your door and tell you about them! Working with expert insurance agents like Priority Insurance, LLC, who know the industry well, is the best way for you to uncover those opportunities and protect your assets at the best monthly rates. We’ll even help you work through the complicated relationship between your homeowners insurance and your small business , if that comes into play. As you launch your own business, it’s important to know from the start how it will affect your coverage for your home, your vehicles, and anything else you use in the course of business. Make your appointment with our experts today!
Insurance is the most overlooked factor for new business owners. Find out why it matters and how to safeguard your business from day one.