Insurance: The Factor That New Business Owners Always Overlook
April 22, 2026

Starting a new business is incredibly exciting! Before the ribbon-cutting and opening the doors to the public, there is obviously a lot that has to be done by the business owner in order to make sure everything is ready. There is one factor, however, that escapes many business owners at the outset of their new endeavor, and it can come back to cause real problems later on.


Getting your commercial insurance needs squared away as soon as possible is the best way to make sure that you are ready to succeed, not only on day one, but long into the future as well, no matter what opportunities or challenges come your way.


General Liability Insurance


Perhaps the most familiar type of small
business insurance south carolina is general liability insurance. New business owners are usually aware of this insurance and their need for it, although their specific types of coverage and coverage levels will vary based on what type of business they are launching or buying.


Just as with an individual homeowner’s insurance policy, a business owner could end up wasting money over years paying for a policy that includes features and limits that they don’t need. Even worse, they could find themselves in a financially dangerous position if their insurance is not well matched to their business and an accident or other negative event occurs. It’s important to have an expert agent handling your business insurance needs, not just at the outset, but on an ongoing basis as the nature and needs of your business change.


Worker’s Compensation


The area of worker’s compensation insurance is very complex, and your business’s specific needs will depend on how many employees you have and what type of work they do. Once again, you need to have this insurance policy closely tailored to your unique organization, or you could either spend too much money on premiums or leave your employees and yourself vulnerable in the event of a claim.


Other Commercial Insurance Types


One type of commercial insurance that business owners don’t always anticipate needing is a commercial auto insurance policy. Having employees drive their own vehicles to accomplish work tasks may seem intuitive, but when an incident occurs, it quickly becomes clear that without the right type of insurance coverage in place, that is a disaster! 


Most personal auto insurance policies actually specifically exclude use of the vehicle for commercial purposes. That means that if an employee is making a delivery or driving to a service call for your business and has an accident, their personal policy will most likely not cover the claim, leaving your business responsible for costs. A commercial auto insurance policy ensures that you have the right coverage for not only company-owned vehicles, but also for employees’ personal vehicles while they are being used for business purposes.


Cyber Liability Insurance


With more and more commerce, communication, and activities of all types happening online, cyber security is more important than ever before, particularly for a small business. Many hackers are well funded and have access to very advanced tools, and your business needs to be protected in the event that a network breach, ransomware attack, or other incident happens.


Adding cyber liability to your small business insurance in South Carolina is important. It’s not just for e-commerce retailers and companies that operate primarily over the internet; if you handle personal information for clients or customers, or if you process payments via credit card, that information could be targeted by a cyber attack. Avoiding the enormous costs associated with a data breach depends on having the right type of insurance.


Business Owners Policy Insurance


These aren’t the only types of insurance that your small business may need. As your agent assesses your business and explains what it will take in order to protect it, you may well start to feel overwhelmed. To simplify the process of insuring your business, and to save you money on your monthly premium, Priority Insurance offers Business Owners Policies (BOPs) that bundle many different types of insurance into a single policy.


As you work with your expert commercial insurance agent at Priority, you’ll get all the different types of coverage that your business needs, and at the optimal levels to keep you as the owner, your employees, and your guests cared for. As your business grows, expands into new areas, and adds employees, your agent will keep in touch and advise you on how your insurance policies should change along with your business.


Pitfalls to Avoid


Sadly, many new business owners jump into the process without adequately assessing what their insurance costs will be. It’s possible to go through the entire process of buying a business from a previous owner, for instance, without closely examining what the overall insurance costs are. Here at Priority Insurance, we have seen business owners shocked to discover what those costs are after the fact.


A very common situation involves a new
business owner seeking to contract with another business for services. As part of that process, the prospective business partner requests a certificate of insurance (COI) to verify that the business holds the appropriate insurance coverage. When the new business owner reviews that COI closely for the first time, the numbers on the sheet may not be what he or she anticipated!


Avoiding these and other issues is as easy as having Priority Insurance handle your small business insurance in South Carolina. Our agents will take the time necessary to learn about your commercial needs, then do the legwork of finding the ideal methods of coverage for you. You’ll be able to focus on developing your business and reaching new customers, rather than worrying about whether your company is protected and your employees have all the support they need.


Contact our office today to get the right insurance for your small business in Greenville, Spartanburg, Anderson, or elsewhere in the Upstate. We provide expertise in worker’s compensation, commercial auto, general liability, and other important commercial categories.

Woman behind a café counter with glass pastry display and coffee equipment
October 13, 2026
Buy-sell agreements, key person insurance, and executive bonus plans for Upstate SC business owners. Protect your family, partners, and key people.
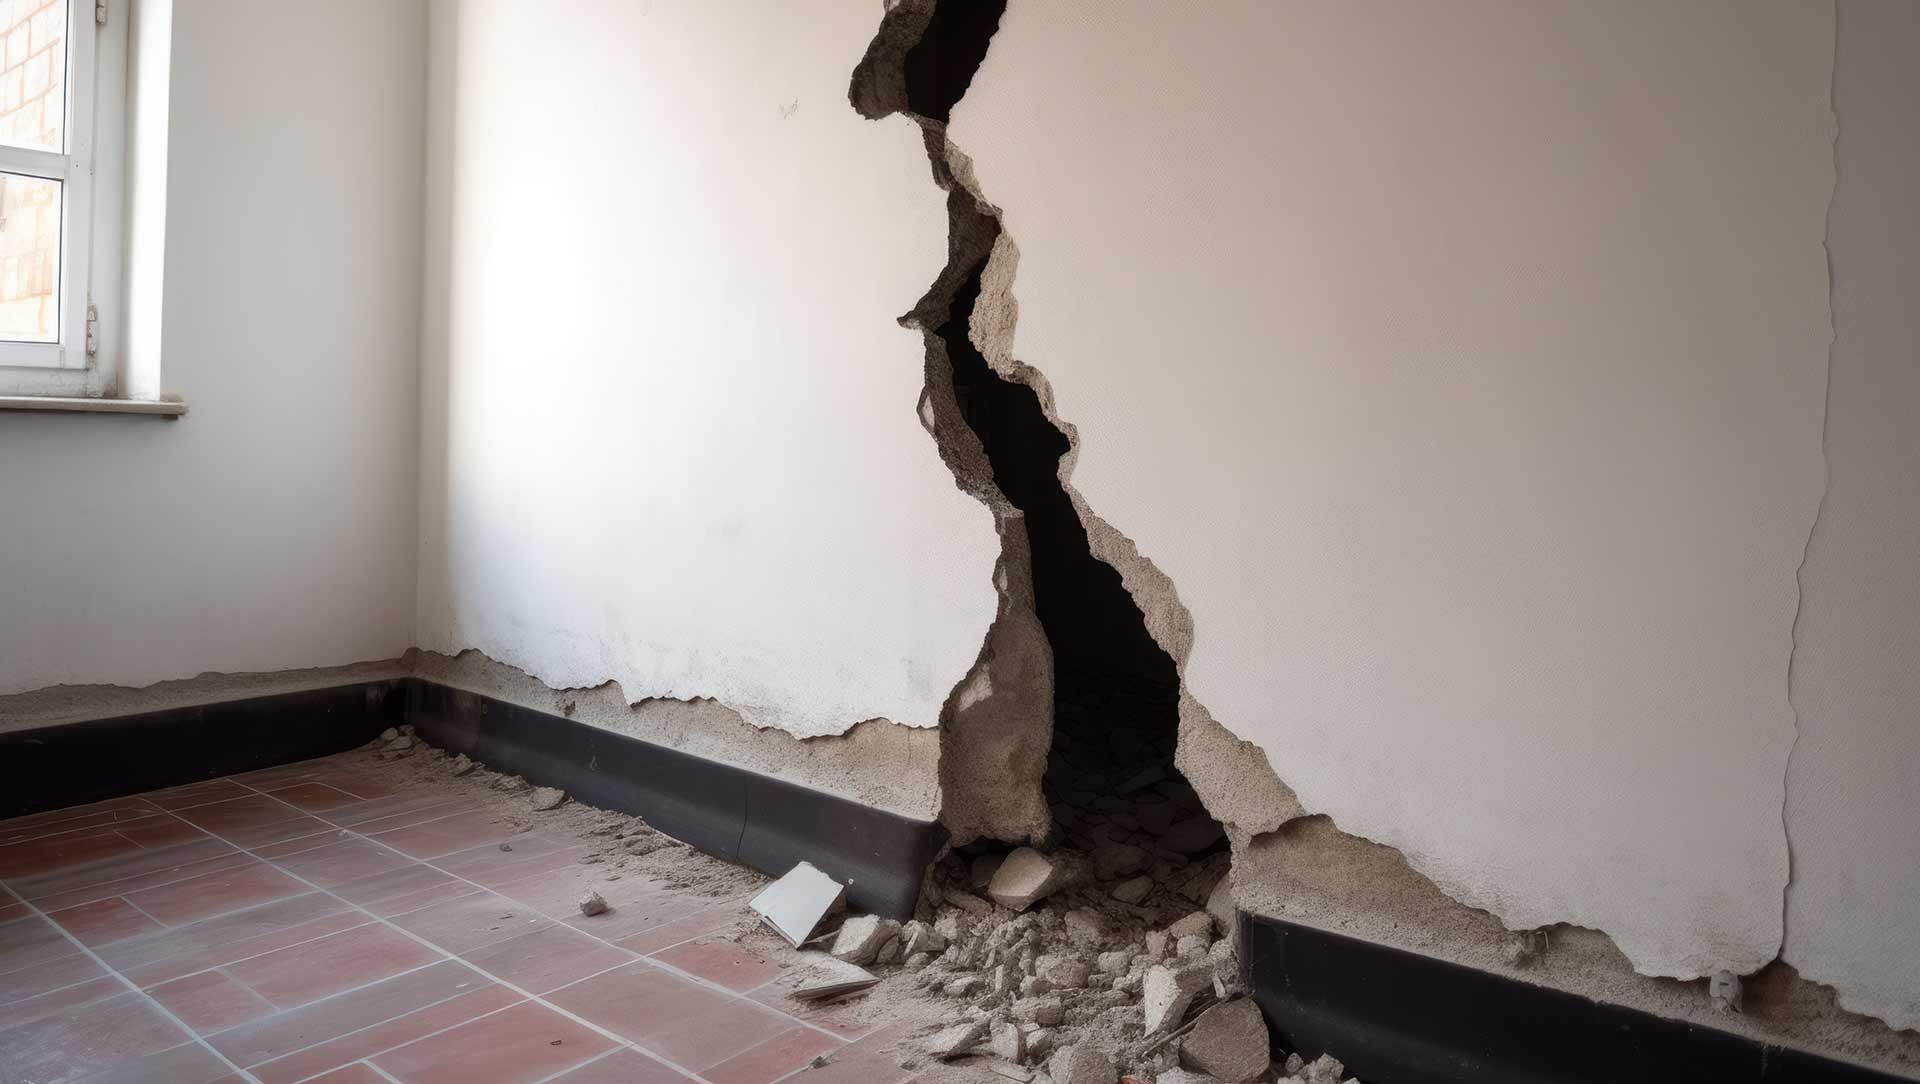
Interior wall with a large vertical crack and crumbled plaster exposing damage near the floor.
October 8, 2026
Most homeowners I sit down with in Greenville can tell me their deductible and roughly what their house is insured for. Very few can tell me whether they're covered if the ground shakes, or if the sewer line backs up into the house. That's not a knock on anybody — these are two coverages almost nobody thinks about until the day they need them. And on that day, a lot of people find out the answer is no.  Both earthquake damage and sewer or water backup are excluded on a standard homeowners policy. Both can usually be added back, often for a modest cost. Here's what I want every homeowner in the Upstate to understand about each one.
By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Night-lit two-story brick house with a balcony and warm exterior lights at night
September 17, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
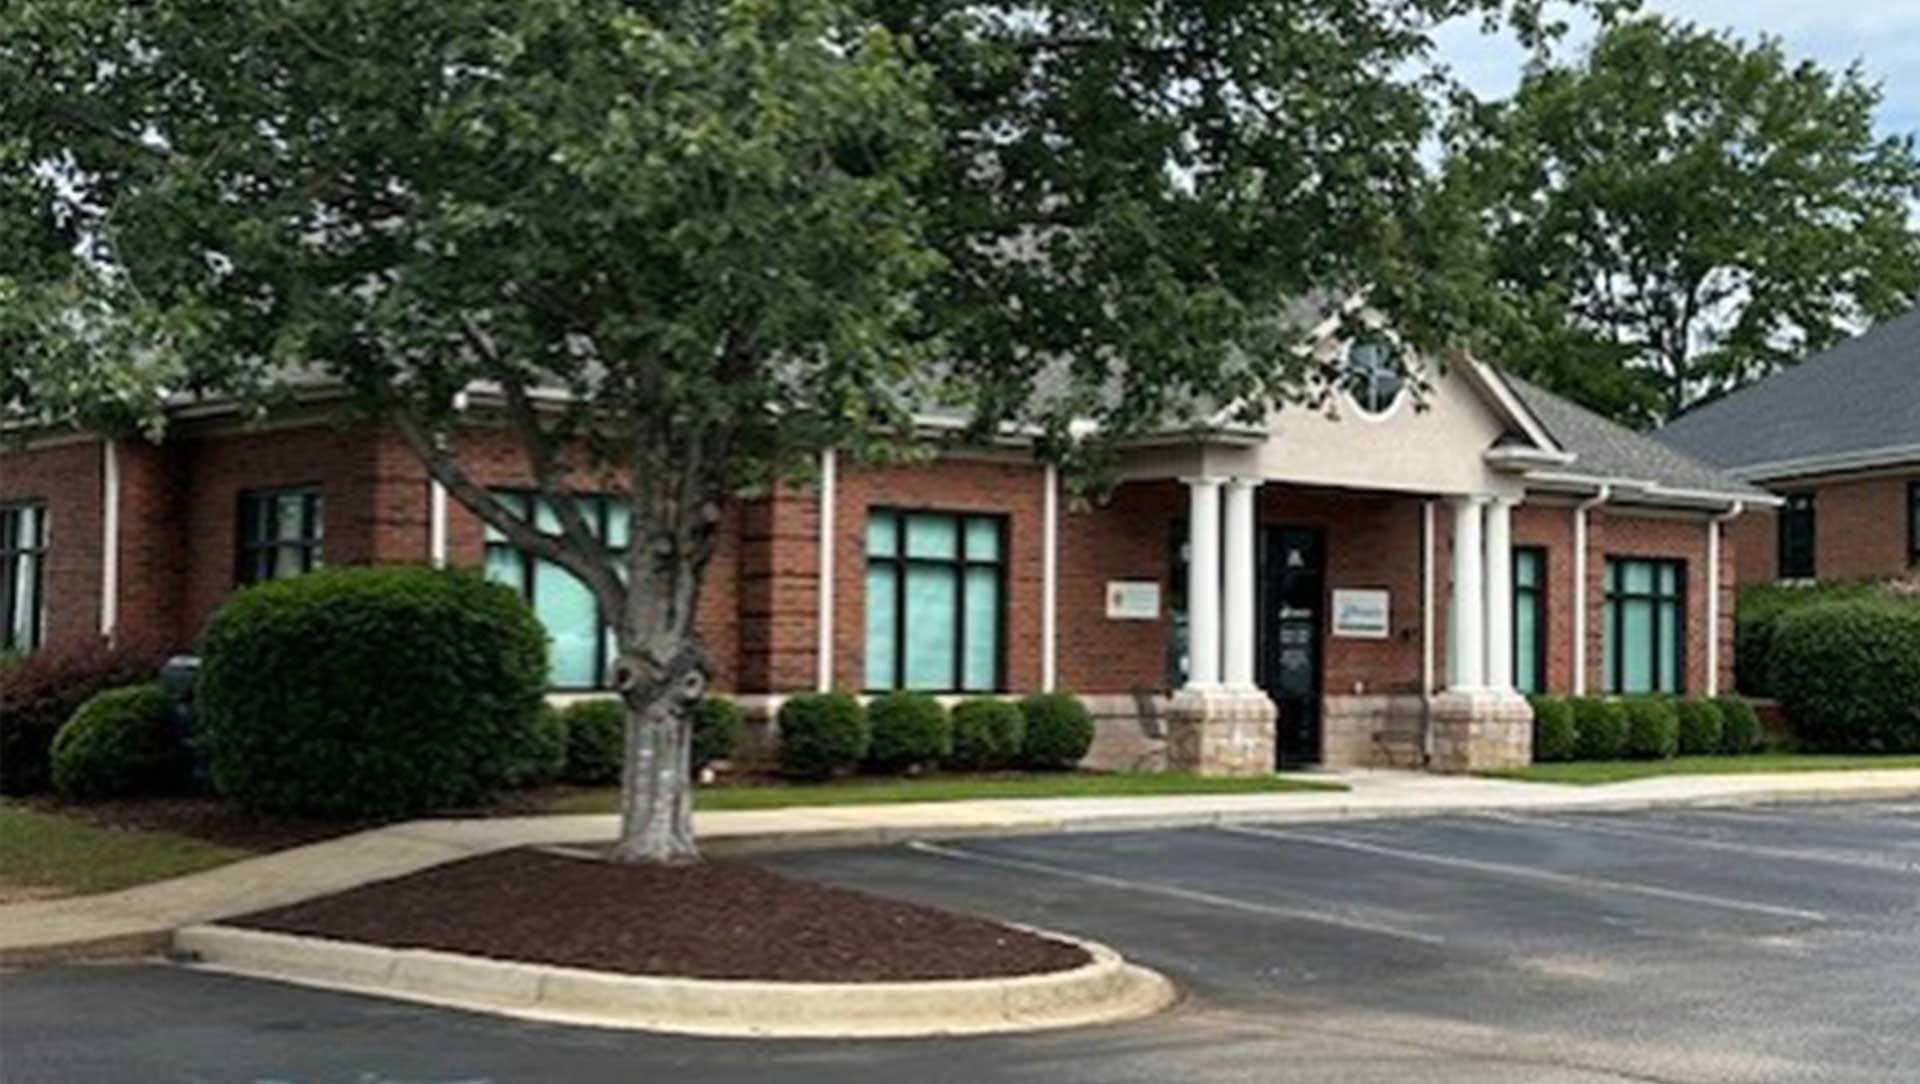
Brick office building with white columns, green awnings, and a tree-lined parking lot
By By Mark Turley, Owner — Priority Insurance LLC • August 11, 2026
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Show More