Earthquake & Water Backup Coverage: The Homeowners Gaps Most People Miss Greenville, SC & the Upstate
October 8, 2026

Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA

Licensed in South Carolina · North Carolina · Georgia

By Mark Turley, Owner — Priority Insurance LLC

Independent agent serving the Upstate since 2011 · Published October 7, 2026


Most homeowners I sit down with in Greenville can tell me their deductible and roughly what their house is insured for. Very few can tell me whether they're covered if the ground shakes, or if the sewer line backs up into the house. That's not a knock on anybody — these are two coverages almost nobody thinks about until the day they need them. And on that day, a lot of people find out the answer is no.


Both earthquake damage and sewer or water backup are excluded on a standard homeowners policy. Both can usually be added back, often for a modest cost. Here's what I want every homeowner in the Upstate to understand about each one.

Yes, South Carolina has earthquakes — plenty of them

When people hear "earthquake insurance," they think California. But South Carolina sits on several fault systems, and according to the South Carolina Emergency Management Division, the state records roughly 10 to 15 earthquakes a year, with three to five of them felt by people. By some rankings, South Carolina carries the highest earthquake risk of any state on the East Coast, and state officials consider the entire state to be at moderate to high risk.


The history backs that up. The 1886 Charleston earthquake was the most damaging quake ever recorded in the eastern United States, felt as far away as Chicago and Cuba. And the Upstate isn't off the hook: in 1913, an earthquake centered in Union County was strong enough that it would likely register around a 5.5 by today's standards. Our corner of the state also sits in the Southern Appalachian seismic zone, which produces frequent small quakes, and the swarm of earthquakes near Elgin a few years ago was felt as far north as Rock Hill.


To be fair, scientists will tell you a Charleston-sized event is rare. I'm not telling you the big one is coming next week. But insurance exists for exactly this kind of risk — the unlikely event that would be financially devastating if it happened to you.

Your homeowners policy almost certainly excludes it

A standard homeowners policy contains what's called an earth movement exclusion. If a quake cracks your foundation, drops your chimney, shears your brick veneer, or shifts your framing, that damage is generally on you. A fire that breaks out afterward is typically still covered, but the shaking damage itself is not.


Very few South Carolinians have closed that gap. In 2020, the state Department of Insurance reported about $48 million in earthquake premiums written, compared with nearly $2 billion in homeowners premiums. In other words, for every dollar spent insuring homes here, only a couple of cents went toward earthquake coverage.

How earthquake coverage actually works

There are two ways to get it. An earthquake endorsement is an add-on to your existing homeowners policy and is often the simpler, lower-cost option. A standalone earthquake policy is a separate contract with its own premium and deductible, and it can offer higher limits and more flexibility.


The part you need to understand going in is the deductible. Earthquake deductibles are usually a percentage of your coverage limit, not a flat dollar amount, and the South Carolina Department of Insurance notes 10% to 20% is typical. On a home insured for $300,000, a 10% deductible means you'd cover the first $30,000.


That's a big number, and I'll be honest — it's the reason some people pass on this coverage. But earthquake coverage isn't meant for a few hairline cracks in the drywall. It's meant for the loss that would otherwise wipe out your equity, or leave you paying a mortgage on a house you can't live in. A few more things worth knowing:

  • One event, one deductible. Typically, all quakes within a 72-hour window are treated as a single event.
  • Report damage even if you think it's under the deductible. Structural damage isn't always visible right away.
  • Buy it before you need it. Some carriers restrict adding earthquake coverage right after seismic activity, so waiting until the ground moves can mean waiting too long.

Earthquake exclusions worth checking on your policy

Adding earthquake coverage doesn't mean everything is covered. These endorsements carry their own exclusions, and the biggest one around here is easy to miss.


Masonry veneer. Many earthquake endorsements exclude exterior masonry veneer — the brick or stone facing on the outside of your walls — and that's how a number of carriers write it. Brick veneer is one of the most common exteriors on homes across the Upstate, and it's also one of the first things to crack or fall away in a quake. On the standard industry form, the value of that veneer is also taken out of the picture before the deductible is figured. Stucco generally isn't treated as masonry veneer. Some carriers will cover veneer for an additional premium, so if your home has brick or stone on the outside, ask whether yours is included.


A few other exclusions to look for:

  • Flood caused by the quake. Water damage from flooding or a tidal wave set off by an earthquake is typically excluded from the earthquake coverage itself.
  • Land and soil. The cost of filling, stabilizing, or replacing the land under your home generally isn't covered.
  • Separate deductibles. The percentage deductible may apply separately to your dwelling, other structures, and belongings, which can make your out-of-pocket share larger than you expect.

Water backup: the claim nobody wants to have

If you've ever had sewage back up into your home, you know it's one of the worst messes a homeowner can face. What makes it worse is the discovery that often comes next: your homeowners coverage for it may be limited or nonexistent.


Here's what I did at my own house. I had a check valve — often called a backwater valve — installed on my sewer line. It works in one direction only: wastewater flows out of my house to the sewer, and nothing, not even an air pocket, can come back up the line into the house.


If you're considering one, a few practical notes. Have a licensed plumber do the work, since a permit may be required. It isn't something you install and forget; the valve needs periodic inspection to keep working. And while the valve is closed during a backup, your own drains can't empty either, so hold off on running water until things clear. A valve lowers your odds of a backup a great deal, but it doesn't replace having the right coverage.

Why standard policies leave you exposed

Insurance treats water damage in three very different ways, and the differences matter:

  • Sudden water from inside the house — a burst supply line or a failed water heater — is generally covered by your base policy.
  • Water or sewage that backs up through sewers or drains, or overflows from a sump pump, is excluded unless you add a water backup endorsement.
  • Flood and surface water require a separate flood insurance policy altogether.


Backups happen more often than people think. A heavy summer thunderstorm can overload municipal lines, and tree roots, grease buildup, or an aging sewer lateral can do the same thing on a clear day. Homes with finished basements or lower levels — common on the hillside lots you see in Greer, Taylors, and Travelers Rest — have the most to lose, because that's where the water shows up first.

Sewer backup vs. water backup: read the fine print

This is the part I most want you to take away. Not every "water backup" endorsement is the same, and carriers don't all use the same language. Some cover sewer and drain backup but treat sump pump overflow differently. Some limited versions only pay if the water originates within the dwelling, while broader versions remove that requirement. Many come with a small fixed limit and their own deductible, which may not come close to covering a finished basement, flooring, drywall, and professional cleanup.


It's best to check with your insurance company to see whether there's a difference between sewer backup and water backup on your policy. Questions worth asking:

  • Does my coverage include sewer backup, drain backup, and sump pump overflow?
  • Does the water have to start inside my home for the coverage to apply?
  • What's my limit, and is it realistic for my lower level and belongings?
  • Is there a separate deductible for this coverage?
  • Would a backwater valve or a sump pump battery backup lower my premium?

What these cost — and how we help

For most Upstate homeowners, both of these options are modest additions compared with the cost of the loss they protect against. Your price depends on where you live, how your home is built, and the limit and deductible you choose. As an independent agency, we can compare earthquake and water backup options across our large carrier partner network and walk you through the tradeoffs plainly, so you can decide what's worth it for your home.


If you own a home in Greenville, Greer, Simpsonville, Mauldin, Taylors, Fountain Inn, Travelers Rest, Easley, Anderson, Spartanburg, or anywhere in the Upstate, let's take a few minutes to look at what your policy does and doesn't cover. It's a lot easier to answer that question now than after the ground shakes or the floor drain overflows.

Find out what your homeowners policy leaves out

A quick review now beats a surprise at claim time. We'll compare earthquake and water backup options across our carrier network and explain the tradeoffs plainly.

Mark Turley is the owner of Priority Insurance LLC, an independent insurance agency in Greenville, SC serving the Upstate since 2011. Priority shops a large network of top-rated carriers across South Carolina, North Carolina, and Georgia, and has a CLU · ChFC–credentialed advisor on staff for life and financial planning. Office: 140 Milestone Way, Suite A, Greenville, SC 29615. Phone: (864) 297-9744.

This article is general education, not personalized financial, legal, or tax advice. Coverage terms, limits, exclusions, deductibles, and availability vary by policy and carrier. For guidance on your specific home, reach out and we'll review your coverage with you.


Related coverage from Priority Insurance


Home Insurance | Flood Insurance | Umbrella Insurance | Renters Insurance

By Mark Turley • November 17, 2026
A business owner who needs to get workers’ compensation insurance for the first time is likely to have lots of questions. This is a large area of insurance that has the potential to make the difference between a company surviving or failing in the event of a work-related accident. SC generally requires this coverage for a company with four or more employees, and employers with an annual payroll of less than $3,000 are exempt regardless of employee count. Part-time workers count toward the threshold, and so do corporate officers who haven’t rejected coverage. This often catches small corporations off guard! Here are three answers to some of the common questions that come up related to workers’ compensation insurance in Greenville, SC. If any of these topics prompt more questions in your mind about your current insurance coverage, or if you aren’t sure whether workers’ compensation is required by law for your business, schedule a consultation with one of our South Carolina insurance experts here at Priority Insurance.
Woman behind a café counter with glass pastry display and coffee equipment
October 13, 2026
Buy-sell agreements, key person insurance, and executive bonus plans for Upstate SC business owners. Protect your family, partners, and key people.
By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Night-lit two-story brick house with a balcony and warm exterior lights at night
September 17, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
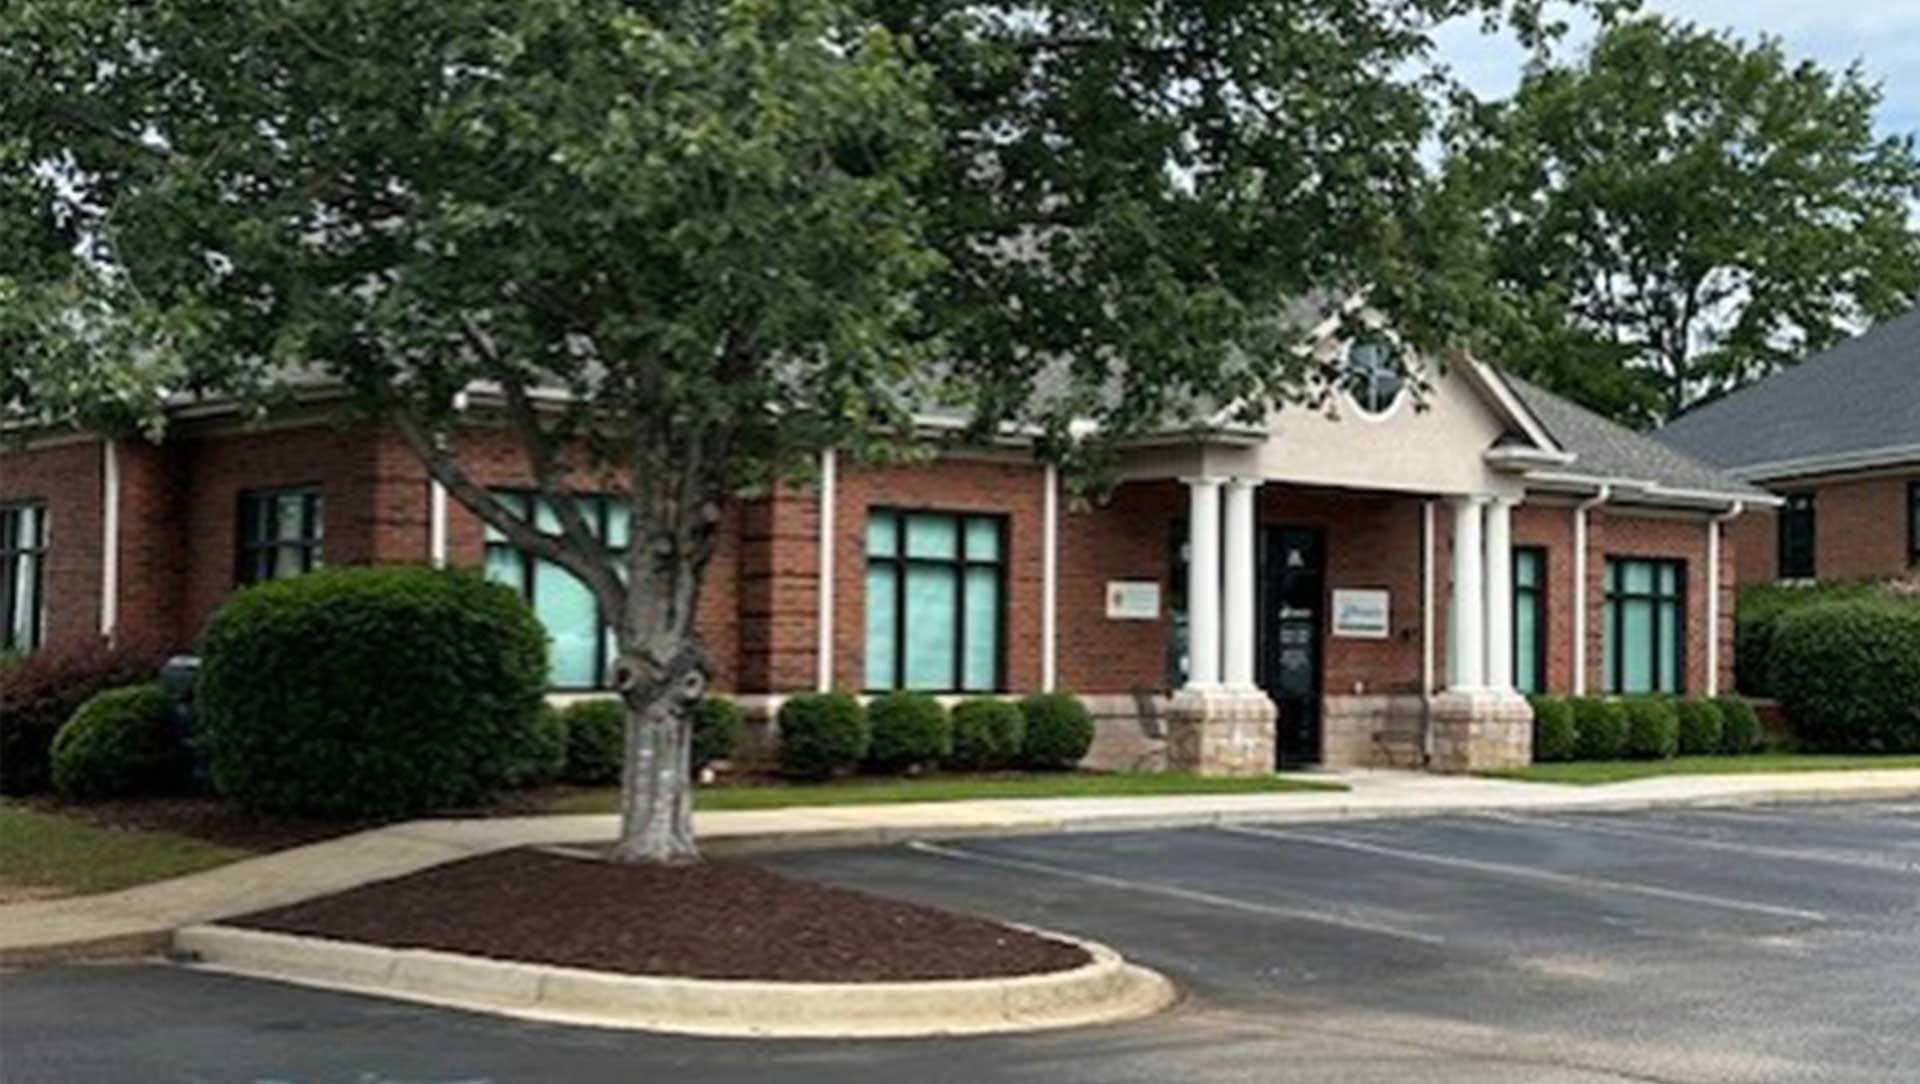
Brick office building with white columns, green awnings, and a tree-lined parking lot
By By Mark Turley, Owner — Priority Insurance LLC • August 11, 2026
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Show More