Two Wheels Or Four? Key Differences Between Motorcycle And Auto Insurance
March 20, 2025
FJ Cruiser with rooftop tent, man sitting on front, motorcycle nearby, mountain backdrop.

When it comes to insuring your vehicle, whether it's a motorcycle or a car, it’s essential to understand that motorcycle insurance and auto insurance are not created equal. While both types of coverage provide protection in the event of an accident or damage to your vehicle, there are distinct differences between the two that can affect how much you pay, what you're covered for, and what kind of risks you're insured against.

In this blog, we’ll explore the key differences between motorcycle and auto insurance, so you can make informed decisions about the coverage that best suits your needs.

Coverage Requirements

The basic principles of insurance are similar for both motorcycles and cars: you need coverage for liability (injuries and damages you cause to others), collision (damage to your own vehicle), and comprehensive (non-collision incidents like theft or weather damage). However, the specific requirements for each type of insurance can differ.

Motorcycle Insurance:

Motorcycle insurance is typically less expensive than auto insurance, but this doesn’t mean that it's any less important. Motorcycle riders are more exposed to risks due to the nature of riding on two wheels. Because motorcycles are harder to control and less visible than cars, they have a higher rate of accidents per mile driven. As a result, many states require basic liability insurance for motorcycles, though some states may require additional coverage depending on the rider's experience or the value of the bike.

  • State Requirements: Some states require motorcycle insurance to include liability, while others may require comprehensive and collision coverage for more extensive protection.

  • Helmet Laws: In some states, having coverage that includes personal injury protection (PIP) may be required, especially if you’re not wearing a helmet, which can be a major factor in injury claims.

Auto Insurance:

Car insurance is generally more expensive than motorcycle insurance due to the higher level of risk associated with car accidents. Car owners are usually required by law to carry a minimum amount of insurance coverage that includes liability, collision, and comprehensive coverage. However, depending on the state, car owners may be required to have additional coverages like personal injury protection (PIP) or uninsured motorist (UM) coverage.

  • State Requirements: Most states have mandatory minimum coverage for vehicles, which includes bodily injury and property damage liability, though additional coverages may be optional.

Cost of Insurance

One of the most noticeable differences between motorcycle and auto insurance is the cost. Generally speaking, motorcycle insurance tends to be less expensive than car insurance, although there are exceptions based on factors like the type of bike, the rider’s experience, and the area in which they live.


Factors Affecting Motorcycle Insurance Costs:

  • Type of Motorcycle: High-performance motorcycles or luxury brands may have higher premiums due to their increased risk of theft and higher repair costs.

  • Rider Experience: Inexperienced riders often face higher premiums due to the increased likelihood of accidents.

  • Safety Features: Bikes with anti-lock braking systems (ABS) or other safety features may receive discounts for being less likely to be involved in accidents.


Factors Affecting Auto Insurance Costs:

  • Type of Vehicle: The make and model of the car play a significant role in determining the cost of auto insurance. Sports cars, luxury vehicles, and cars with high repair costs generally carry higher premiums.

  • Driver History: Just like motorcycle insurance, a driver’s age, driving record, and claims history will affect the premiums. Younger drivers and those with a history of accidents or traffic violations will face higher rates.

  • Usage: How often and how far you drive also impacts your auto insurance costs. People who use their cars for commuting or long-distance driving are likely to face higher premiums.


Personal Injury Protection (PIP)

Personal Injury Protection (PIP) is a component of auto and motorcycle insurance that covers medical expenses for injuries sustained in an accident, regardless of who is at fault. While PIP is commonly included in auto insurance policies, its inclusion in motorcycle insurance policies is less common and often optional.

  • Motorcycle Insurance:
    Motorcycle riders are much more exposed in the event of a crash because they don’t have the protection of a metal frame around them. As a result, injuries tend to be more severe, and medical bills can quickly add up. PIP coverage is not as universally available for motorcycles, and riders may need to purchase additional medical coverage or opt for an accident medical payment rider. Riders can also consider health insurance or disability insurance to cover medical costs in the event of a serious accident.

  • Auto Insurance:
    For cars, PIP is more common, especially in no-fault states, where it is required by law. In these states, regardless of who is at fault in an accident, PIP coverage ensures that each driver’s medical expenses are covered. Even in states without a no-fault system, PIP or similar medical coverage can still be purchased to provide more extensive medical benefits in the event of an accident.


Collision and Comprehensive Coverage

Both motorcycle and auto insurance policies offer collision and comprehensive coverage, but the coverage details can differ.

Motorcycle Insurance:

  • Collision Coverage: Covers damage to your bike resulting from a crash, even if you are at fault.
  • Comprehensive Coverage: Protects against non-collision incidents such as theft, vandalism, natural disasters, or fire. Motorcycles are often more vulnerable to theft, so comprehensive coverage is particularly important.
  • Custom Parts and Equipment Coverage: Many motorcycle enthusiasts add custom parts to their bikes. Standard policies often don’t cover these, so additional coverage may be necessary.

Auto Insurance:

  • Collision Coverage: Covers damage to your car in the event of an accident, regardless of fault.
  • Comprehensive Coverage: Similar to motorcycle insurance, it protects against non-collision damage to your vehicle, such as theft, vandalism, or natural disasters.
  • Uninsured/Underinsured Motorist Coverage: Covers damage and medical costs if you're hit by a driver without sufficient insurance.


Risk Factors and Liability

The risks faced by drivers of motorcycles and cars vary, and these differences are reflected in the insurance coverage.


  • Motorcycle Insurance:
    Motorcycles are inherently riskier than cars. They have less stability on the road, are more difficult to control, and offer less protection in the event of a crash. As a result, motorcycle riders face higher risks of injury, and insurance companies often charge higher premiums for full coverage. The greater risk factor also means that liability insurance for motorcycles is often priced higher than for cars.


  • Auto Insurance:
    While cars are generally safer than motorcycles, the risks still exist. Cars are larger, offer more protection in crashes, and tend to have better road stability. However, insurance costs can be high depending on the type of car, driver history, and location. The addition of features such as collision detection and lane-keeping assistance can lower premiums due to reduced risk.

Conclusion

When it comes to motorcycle vs. auto insurance, the fundamental coverage types are similar, but the specifics can vary greatly. Motorcycles typically require less expensive insurance, but due to the higher risks involved, they may need additional coverage, especially for medical costs. Cars, on the other hand, usually have more comprehensive coverage options and higher premiums due to the larger risks associated with vehicle accidents.

Ultimately, whether you’re insuring a motorcycle or a car, understanding the differences in coverage and risks will help ensure that you have the right protection for your needs. Be sure to review your policy regularly and speak with an insurance provider to ensure you’re getting the best coverage at the right price. Safe driving, whether on two wheels or four, starts with knowing that you’re properly covered. 


At Priority Insurance LLC, we put our clients first by offering them policies that they can afford. Having insurance is a necessity nowadays, and we're here to help you out. Learn more about our products and services by calling our agency at 
(864) 297-9744. You can also request a quote by CLICKING HERE.

Disclaimer: The information presented in this blog is intended for informational purposes only and should not be considered as professional advice. It is crucial to consult with a qualified insurance agent or professional for personalized advice tailored to your specific circumstances. They can provide expert guidance and help you make informed decisions regarding your insurance needs.​

By Palmetto Soft • September 18, 2026
Does your small SC business need cyber liability insurance? Learn why hackers target small businesses and how Priority Insurance can help protect you.
Night-lit two-story brick house with a balcony and warm exterior lights at night
September 17, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Hands typing on a keyboard with a glowing blue cybersecurity shield interface overlay.
September 15, 2026
I'm going to start this one with a story I'd rather not have to tell, because it happened to me — right here in my own agency. I had an administrator on my team who had access to all of our business banking and a lot of sensitive information. One day a notice popped up on her email that looked like it came from Microsoft, asking her to re-enter her password to log back in. She did what any of us might do in a busy moment. It wasn't Microsoft. It was cyber fraud, and that one password was all it took. From there, the criminals got into our system. They stole her bank account information, redirected her direct deposit to a fraudulent account, and took two of her paychecks before we caught it. We were lucky in one important way: our client files weren't touched. But because an intruder had been inside a system that held personal information, South Carolina law kicked in and required us to follow a specific protocol to protect everyone involved. Handling that the right way — through a cyber law firm, with all the steps the state requires — cost more than $50,000. I didn't pay that out of my own pocket, because I carry Cyber Liability insurance and it covered the response. Without it, that would have been a $50,000-plus bill landing on my desk with no warning. That's why I'm writing this to my clients. This really happened, and it happened to me. Here's what every Upstate business owner needs to understand about it.
Man in a blue arm sling talking on a phone at a desk in an office
August 26, 2026
Independent since 2011 · Large Carrier Partner Network · CLU · ChFC · SC · NC · GA
Family sitting on grass outside a house, smiling and pointing at something in the sky.
August 26, 2026
Most of the insurance I write is about protecting things — a house over in Cleveland Park, a work truck, a small business off Woodruff Road. Life insurance is different. It's the one policy that isn't really for you. It's for the people who depend on you, on the day you're no longer there to provide for them. In the years I've spent serving families across Greenville, Greer, Simpsonville, and the rest of the Upstate, I've learned that this is the coverage people put off the longest — and the one their families are most grateful someone talked them into.  So let me talk you into thinking about it clearly. Not with fear, and not with a sales pitch — just with the plain math of what your family would actually face.
By Mark Turley • August 21, 2026
Every August, I watch families all over the Upstate pack up the car and drop a son or daughter off at college — Furman here in Greenville, Bob Jones, North Greenville University up in Tigerville, USC Upstate over in Spartanburg, or Clemson just down the road. It's a proud week. It's also the week that, a few days later, brings the same phone call to my office: "Mark, somebody broke into my daughter's apartment and took her laptop and her bike — are we covered for that?" The honest answer depends on a decision most families never realize they needed to make before move-in day. So let me walk you through it, because renters insurance for a college student is one of the least expensive and most overlooked protections I write.
By Palmetto Soft • August 21, 2026
General liability pays first, umbrella covers the rest. See how these SC business insurance policies work together to protect you from big claims.
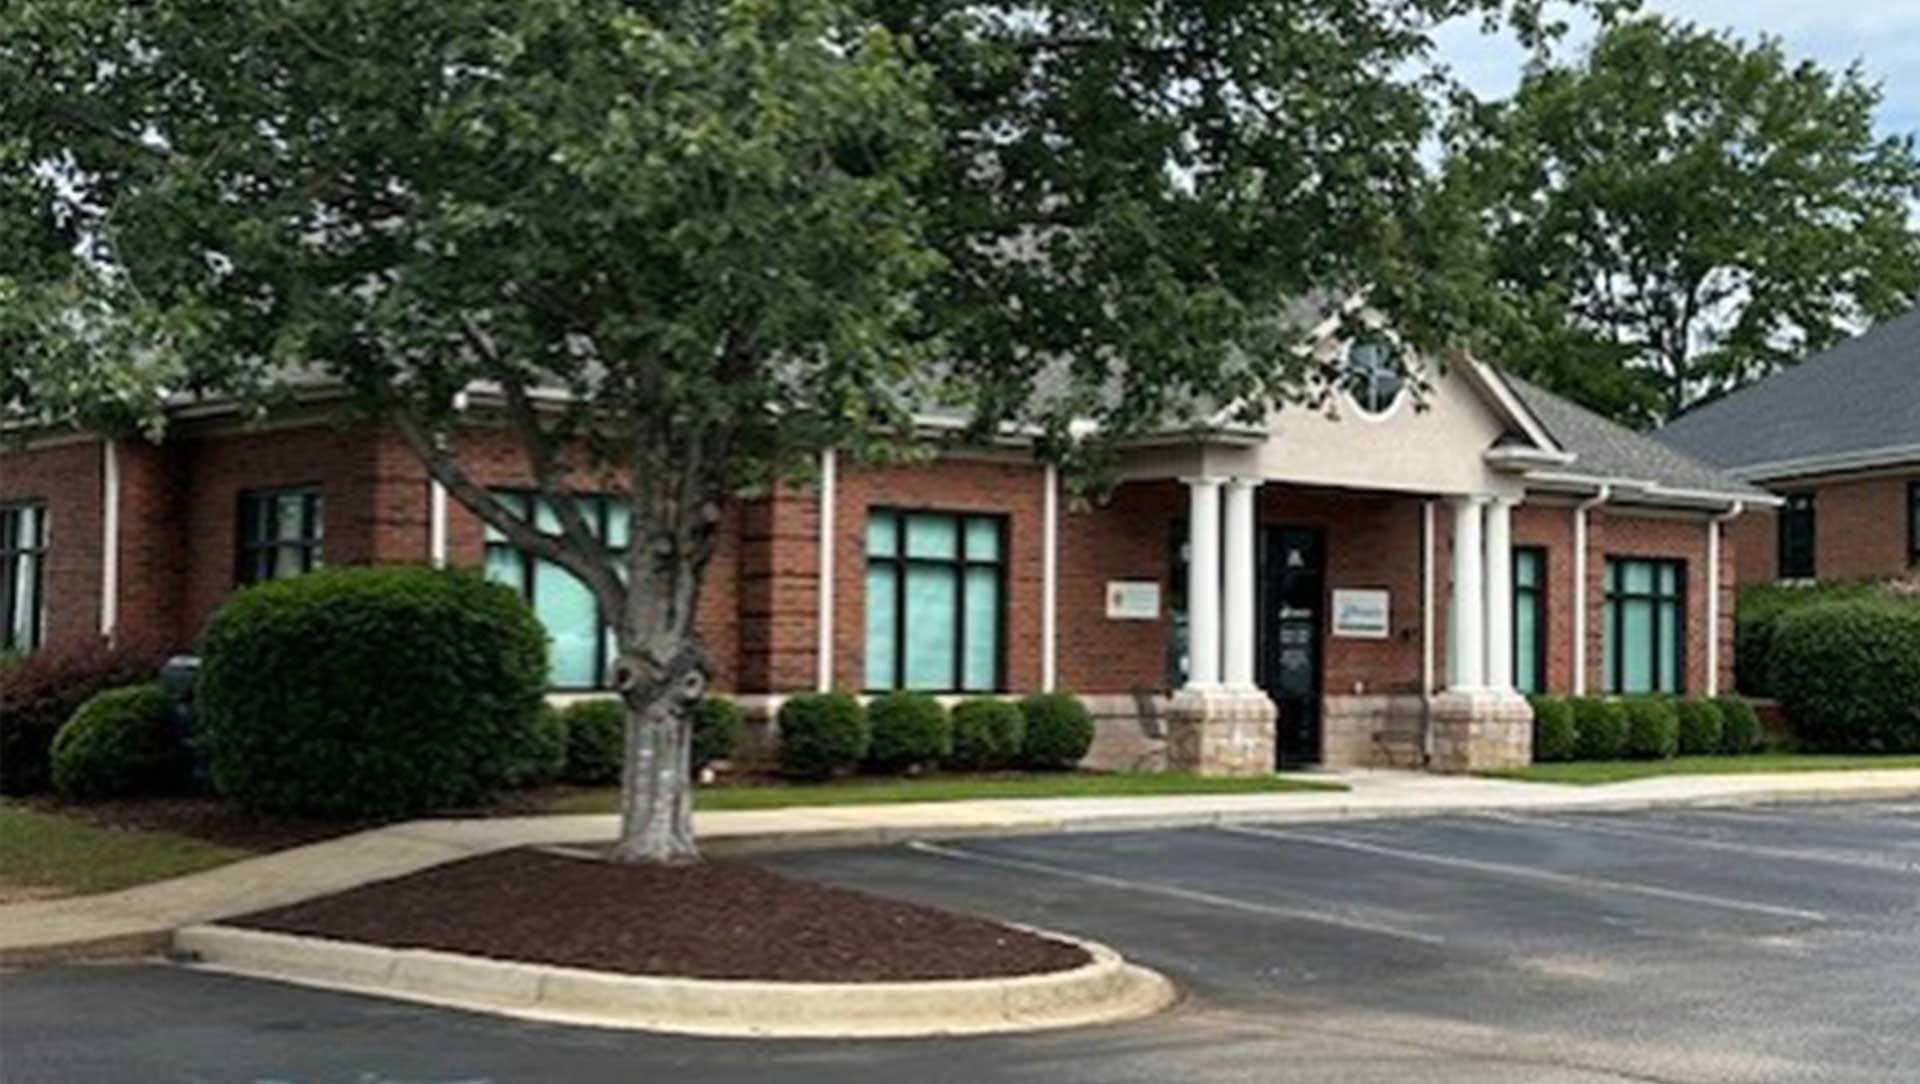
Brick office building with white columns, green awnings, and a tree-lined parking lot
By By Mark Turley, Owner — Priority Insurance LLC • August 11, 2026
The Priority Insurance office in Greenville, SC — owner Mark Turley protects his own building with the same Business Owners Policy coverage he recommends to Upstate businesses.
Dark blue luxury SUV parked outside a building on a patterned driveway
By By Mark Turley, Owner — Priority Insurance LLC • August 4, 2026
Mark Turley, owner of Priority Insurance LLC, outside the agency's Greenville office.
By PalmettoSoft • July 17, 2026
As insurance agents, it’s our job at Priority Insurance to think about the worst case scenario. Most of the businesses that partner with us for their commercial insurance needs enjoy long stretches of “business as usual,” without much in the way of emergencies, injuries, or other events that would trigger an insurance claim. However, when that rare event does occur, the specific parameters of their business insurance could make the difference between recovering and going bankrupt. Umbrella liability insurance for business owners is a powerful product that provides peace of mind about those unexpected events. To let you know just how valuable this insurance is, here are a few examples of “worst case scenarios” that are more common than you might think. Each example is an event that would not be covered under more traditional types of commercial insurance, so a business owner without an umbrella insurance policy could end up facing thousands of dollars in costs out of pocket. Non-Employee Injury Most business owners are familiar with how workers compensation insurance works, and even with a small business employing only a few people, it’s likely to be in place to protect the owner if an employee is hurt while on the job. But what if someone who doesn’t work at your company is injured on the property? Even if your business is not a public-facing company like a grocery store or restaurant, you most likely have members of the public at your location occasionally. Service providers such as custodial and delivery workers are in and out on a regular basis, and the area outside your building comes into play as well. If one of these people happens to slip and fall while working in your building, or if a passerby is injured by a falling tree limb on your property, things can get complicated very quickly. Avoiding a prolonged legal proceeding is in the business owner’s best interest, and umbrella liability insurance for the business can ensure that the organization can continue to focus on growth, rather than getting sidetracked and having resources drained by a lawsuit. Intellectual Property Lawsuit Copyright infringement is most familiar to the public in the field of entertainment. Occasionally one pop music star will sue another for releasing a song that is suspiciously similar to one of their own. But this situation is not limited to the arts. Small businesses sometimes attract the attention of other organizations when they unwittingly publicize a new logo, slogan, or company name that closely resembles that of the larger company. In order to control their own reputation, these organizations will go after even small businesses to force them to change their intellectual property. In the worst case scenario, they may seek restitution for damages that they perceive. Even if the infringement was unintentional, unraveling the problem could cost a lot of money, which a larger organization may be able to spare but the small business cannot. This type of situation can be avoided with an umbrella liability insurance policy, and your agent at Priority Insurance can help you make sure you’re covered if an event like this ever comes up in connection with your business’s intellectual property. Unexpected Employee Actions Human beings are unpredictable, and that unpredictability can lead to any number of worst case scenarios for a small business. Even though you may have thoroughly vetted each employee on your company’s payroll, there’s no guarantee that those employees won’t someday do something that reflects back negatively on your organization. It could be something as simple as an innocent traffic accident while the employee is driving a company owned car. If another driver is injured in the accident, or if there is damage to a property where the employee is making a delivery, your company could be held liable for the expenses. Depending on the circumstances, the costs may or may not be covered by your company’s commercial auto policy. An umbrella liability insurance policy includes situations that are excluded by your auto policy to make sure that you don’t get stuck paying for damage out of pocket. Unfortunately, much larger issues can arise if an employee unexpectedly commits intentional damage while on your payroll. This is a true worst case scenario, and we all hope that the people we work with every day have one another’s best interests in mind. But it is not unheard of for an employee to suddenly act in a hostile, irrational manner and cause damage or injury to others. As catastrophic as the effects of such an action are to the people involved, they can also be catastrophic for the business that employs the individual. Although we hope none of our clients ever have to face this type of event, we help them make sure they are protected against it with umbrella liability insurance for business owners. Other Threats To a Business It would be impossible, of course, to list all the worst case scenarios that could crop up in the life of a business. That’s exactly why umbrella liability insurance was developed in the first place: to give business owners peace of mind as they begin investing in their organization. Without worrying about the possibility of a once-in-a-century weather event, an unpredictable action by someone, or an unintentional infringement on a powerful company’s intellectual property, a business owner is free to focus on advancing the company’s interests. How confident are you that your organization is ready to withstand whatever comes your way? You can increase that level of confidence by reviewing your business insurance policies with an expert at Priority Insurance. We’ll take a look at all aspects of your business and give you our best advice about what kind of insurance you should hold, what coverages you should have, and what you can do to avoid these and other worst case scenarios in the life of your business. In the Upstate region of South Carolina, contact Priority Insurance today to set up a consultation with a business insurance professional.
Show More